Alaska Qualifying Income Trust Requirements Guide — Qualify a Family Member for Medicaid Before the Next Billing Cycle
For adult children, spouses, and the attorneys, paralegals, and care managers who help them — before another $8,152–$8,517 month of private-pay care goes by.
An Alaska Qualifying Income Trust (also called a Miller Trust or Qualified Income Trust) is an irrevocable trust used to qualify a Medicaid applicant whose monthly income exceeds the Alaska long-term-care income cap of $2,982 per month (figures effective 2026; trust rules effective July 2007). Alaska does not publish a fill-in QIT form — the trust must be drafted (by an attorney, or by you where permitted) to meet DPA's published requirements (7 AAC 100.604 ("Recognized Medicaid trusts") and 7 AAC 100.610 (qualifying-income-trust requirements); DPA's Aged, Disabled and Long Term Care (ADLTC) Eligibility Manual § 526 (Qualifying Income Trusts)). Medicaid eligibility can't start before the month the trust is signed and funded (the trust can't be back-dated), and every month of delay is another month of full private-pay care ($8,152–$8,517/mo in Alaska). This guide is the requirements checklist and operational walkthrough most families need: $97, instant download, money-back if DPA rejects the trust for a reason traceable to following the guide.
It applies when the person who needs care has gross monthly income over Alaska's income cap of $2,982, whether you're their child, their spouse, or a professional helping them.
Spouse staying at home?
Only the applicant's own income counts toward this cap, not yours. Separate federal protections keep you from being left without enough to live on: a resource allowance and, when your own income is low, a monthly income allowance. See Medicaid spousal impoverishment protection.
Alaska doesn't publish a fill-in Qualified Income Trust form, so an attorney drafts it — this is the playbook that keeps that engagement to drafting alone instead of research-plus-drafting: the exact requirements checklist, cited to DPA's own published policy, plus the funding and bank-account mechanics once the trust is signed. Informational only — not legal advice. Every requirement is drawn straight from DPA's own published policy, with the citation behind each claim.
What usually happens
Alaska doesn't publish a fill-in form, so the trust has to be drafted to DPA's requirements, and an elder-law attorney quotes $1,000–$2,500 to research and draft it. Once it's signed, you take it to the bank, where the branch has never opened one of these and says no. Meanwhile the month is running out. Coverage can't start before the month the trust is funded, so a month that slips is another $8,152–$8,517 of private-pay care. (Source for the funding rule: DPA, 7 AAC 100.604 ("Recognized Medicaid trusts") and 7 AAC 100.610 (qualifying-income-trust requirements); DPA's Aged, Disabled and Long Term Care (ADLTC) Eligibility Manual § 526 (Qualifying Income Trusts).)
Much of the attorney's fee is research into what DPA requires. This guide is that research, already done: the 9-item required-provisions checklist, cited to DPA's own policy, so the attorney's time goes to drafting. It also covers what comes after signing. Alaska's rules don't say whether the account needs its own tax ID; these accounts are commonly opened with the applicant's Social Security number. Inside: a word-for-word reply for each bank refusal and a printable letter for the branch manager, a funding worksheet built on the 2026 Alaska income cap, and the 6 reasons DPA most often denies these, each cited.
You stay in control: you open the account at your own bank, and we never see or touch a dollar of your family's income. Money-back if DPA rejects it, or for any reason within 7 days.
Questions about the guide before you buy? Email support@millertrustguide.com.
- Built on DPA's own published policy
- Every claim cited to DPA policy
- Last verified against DPA on August 29, 2026
- We never collect your family member's details
- Secure checkout by Stripe
- Money-back if the trust is rejected
What buyers say
A review from a different state — because it's real, and we'd rather show a genuine reader than fill this page with something invented. Retired attorney & CPA is exactly the kind of reader who'd catch it if this guide were sloppy, which is why we lead with it. We only publish verified customers who gave permission — no invented reviews, no stock quotes.
Your Setup Kit turned out to be extremely useful. It got us to the New Jersey QIT template right away, and that was big. We used the Kit to work through the template and the practical questions about how a QIT actually works, and we were able to draft it, get it executed, open a bank account, and submit it with the application in just two or three days. It was an essential need for us, and the Kit helped us accomplish it very quickly.
Not the only one deciding? Send them this page before you dive in.
$8,152–$8,517 a month, Alaska private-pay care
Why this can't wait: until the trust is set up correctly, an over-income applicant can't be approved for Medicaid — so the private-pay bill keeps landing on your family, and your family member's place in care can depend on it. Coverage begins the calendar month the QIT is signed and funded — there is no back-dating — and Alaska private-pay care runs $8,152–$8,517 a month, so every 30 days of delay is another full month of private-pay bills out of pocket.
The 2026 Alaska income cap
- Income cap, single applicant
- $2,982/mo
- Personal needs allowance
- $200/mo
- Alaska private-pay care
- $8,152–8,517/mo
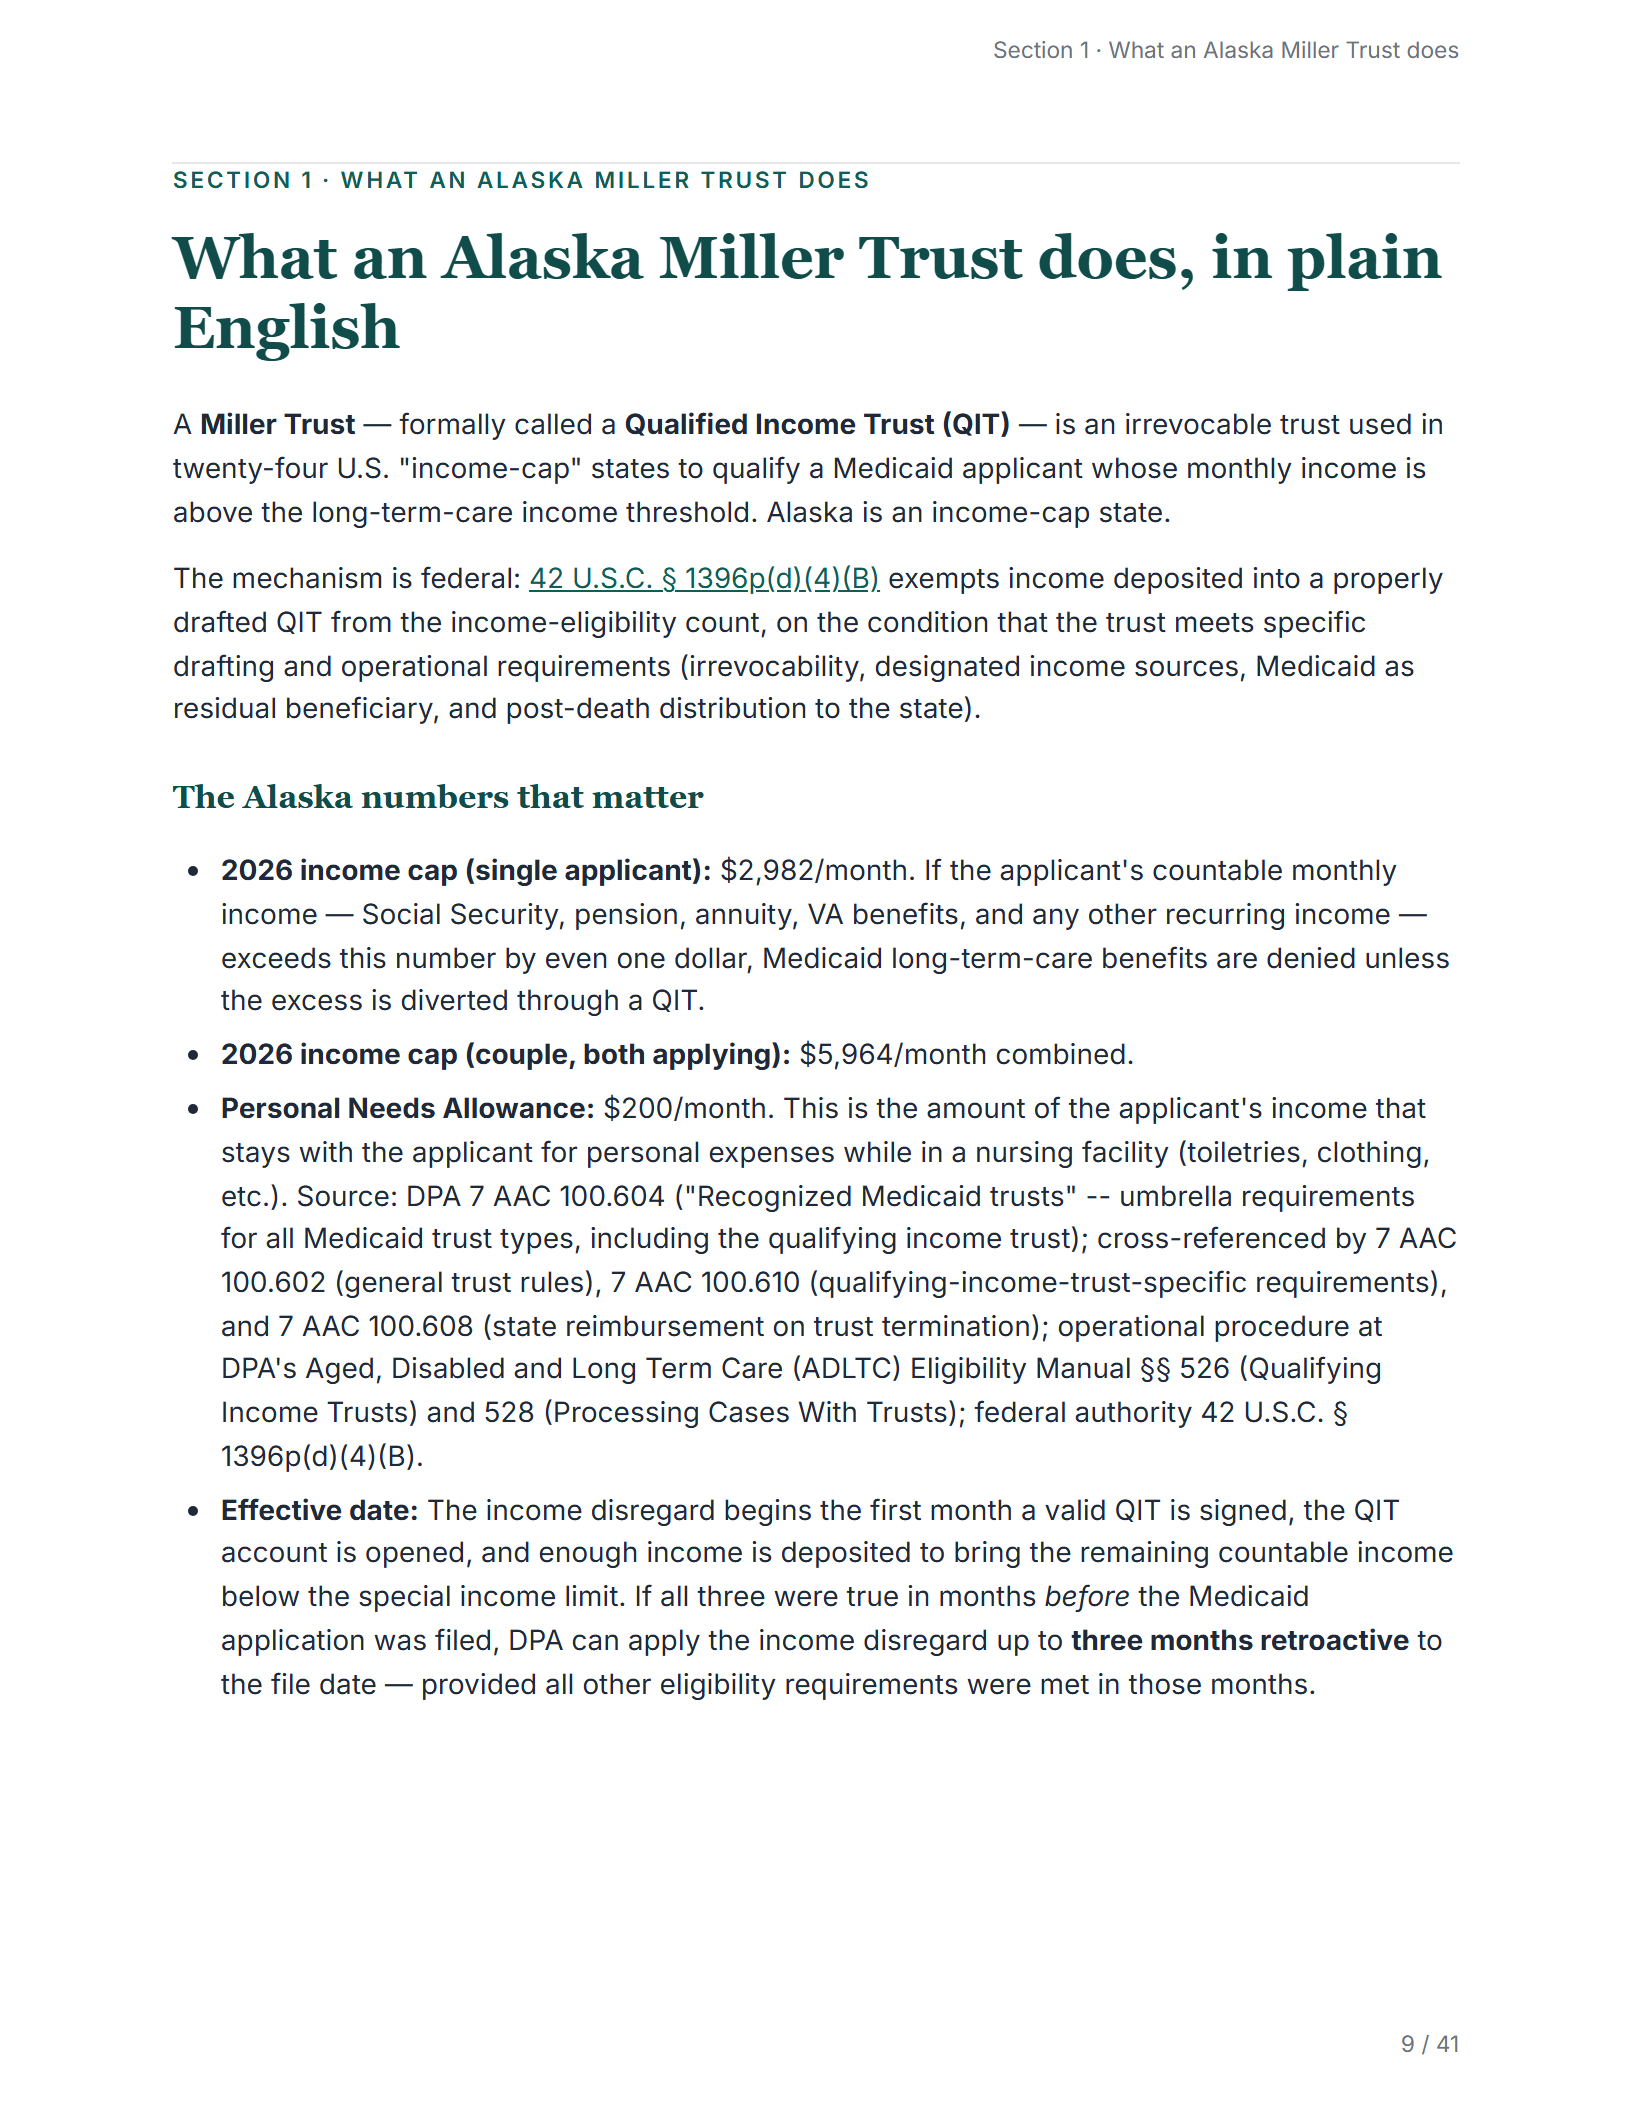
Setting up a Miller Trust in Alaska starts with one number — the income cap. The Alaska 2026 Medicaid long-term-care income limit is $2,982/month for a single applicant. If your family member's countable monthly income exceeds this limit, a properly drafted, signed, and funded QIT diverts the excess and brings countable income below the cap. The applicant's Personal Needs Allowance in Alaska is $200/month. Source: DPA 7 AAC 100.604 ("Recognized Medicaid trusts") and 7 AAC 100.610 (qualifying-income-trust requirements); DPA's Aged, Disabled and Long Term Care (ADLTC) Eligibility Manual § 526 (Qualifying Income Trusts) [1].
What's in the Alaska guide
10 operational sections and 3 reference appendices. Here are the six pieces buyers tell other buyers made the difference:
“If I'm hiring a lawyer anyway, why do I need this?”
Because Alaska doesn't publish a fill-in form, the attorney has to draft the trust either way — the question is whether they research DPA's requirements on your bill, or you hand them the requirements up front. This guide is the research: the 9-item checklist, the funding rule, the bank-refusal script, and the 6 DPA denial traps with the citation behind each — everything that turns a research-and-draft engagement into drafting alone.
If your spouse is the one entering care: this guide covers the Qualified Income Trust — the income side of qualifying — in full. If you're the spouse staying at home (the "community spouse"), the guide also walks you through the trust itself, and Section 9 orients you on the separate resource-allowance rules that protect your home and savings. Those resource rules are fact-specific, so for them you'll likely still want an Alaska elder-law attorney — but the guide's job is to make that a short, cheaper meeting instead of a $1,000–$2,500 one: you walk in with the trust already set up, the resource questions already identified, and the documents already gathered, so you're paying for answers, not for someone to explain the basics to you.
Before you buy
Who this guide isn't for
We'd rather you not buy something you don't need. Skip it if:
- The income is at or under $2,982/month. A Qualifying Income Trust usually isn't needed. Check the number with the free income-cap check.
- The obstacle is savings or property, not income. A Qualifying Income Trust only deals with income. See Medicaid asset protection trusts for the asset side.
- Money or property was given away in the last five years, or other trusts are involved. That needs an Alaska elder-law attorney.
- You want someone to handle the whole thing for you. An attorney drafts the trust either way in Alaska. This guide makes that engagement shorter; it doesn't replace it.
How it works in Alaska
- Confirm income is over the $2,982 cap Gross monthly income, from every source.
- Have the trust drafted to DPA's requirements Alaska doesn't publish a fill-in form.
- Name a trustee and open the trust account A dedicated bank account titled to the trust.
- Fund it in the same calendar month Eligibility starts that month, never earlier.
Full step-by-step walkthrough →
The funding-month rule
- September Trust not funded Private pay: $8,152–$8,517 for the month.
- October Sign, open, deposit Trust signed, account opened and income deposited, all this month. Eligible from October.
- November onward Deposit every month The income goes into the trust account every month to keep eligibility.
There is no back-dating. Funding in October can't cover September.
What it actually looks like
Sample pages from the guide
Real pages from the Alaska guide PDF. Click any page to enlarge.
-
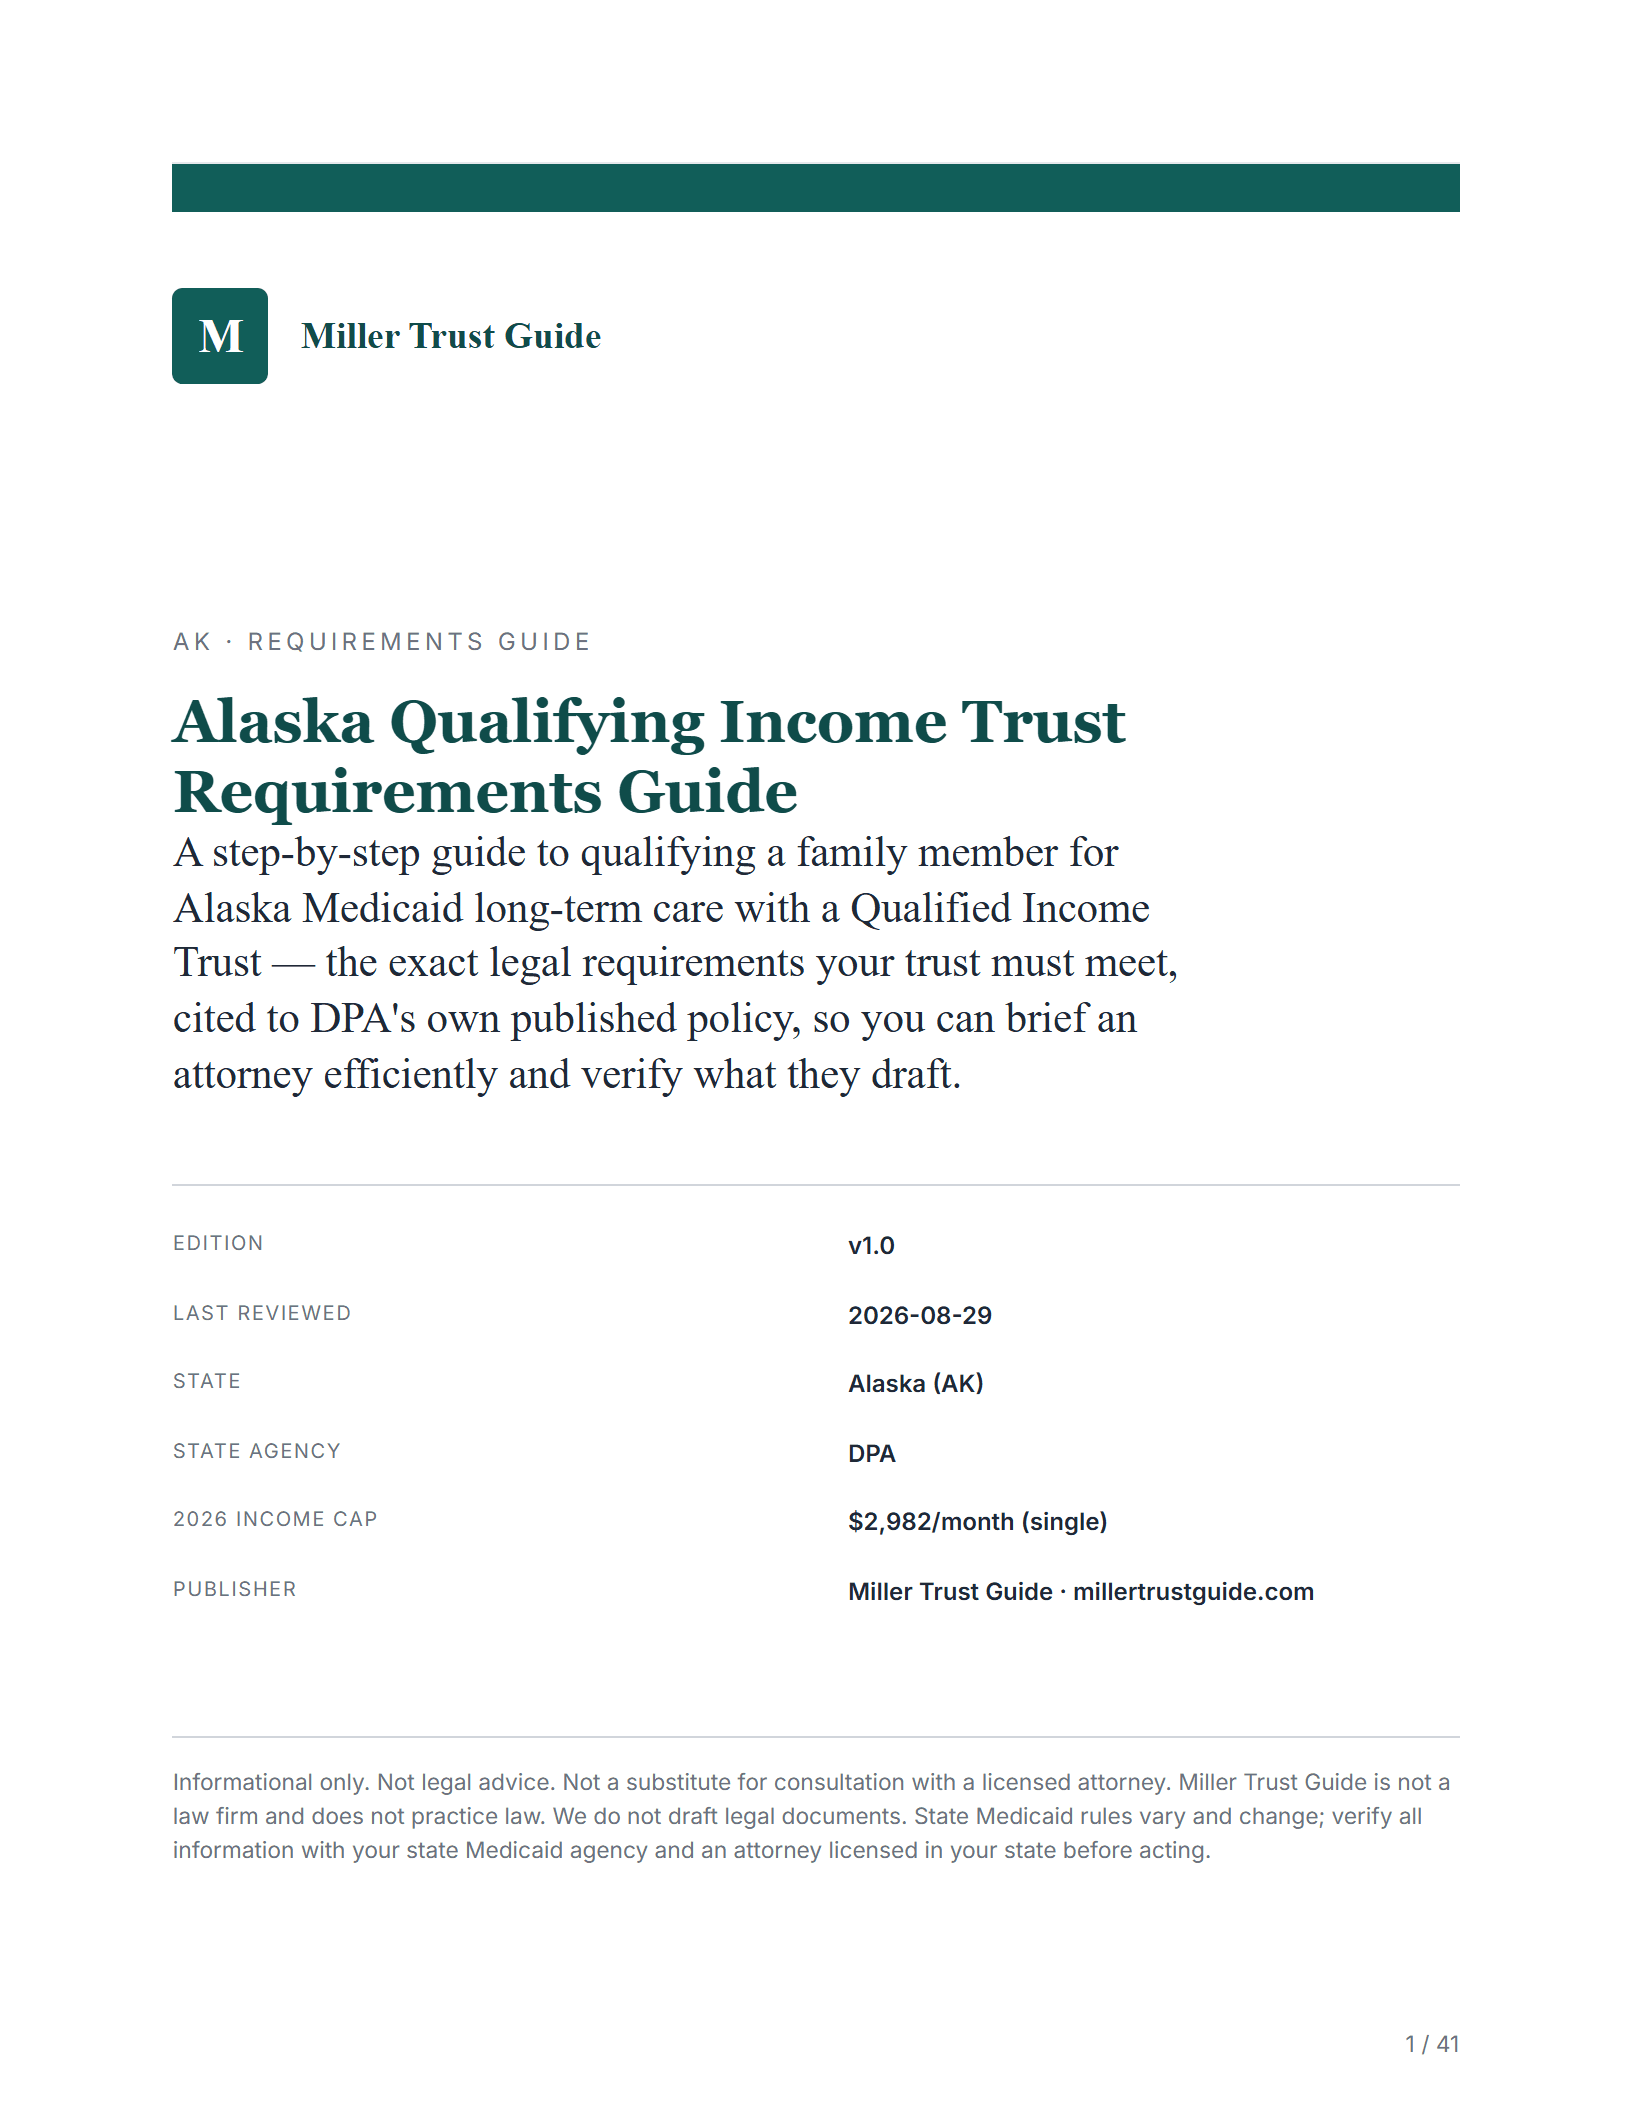
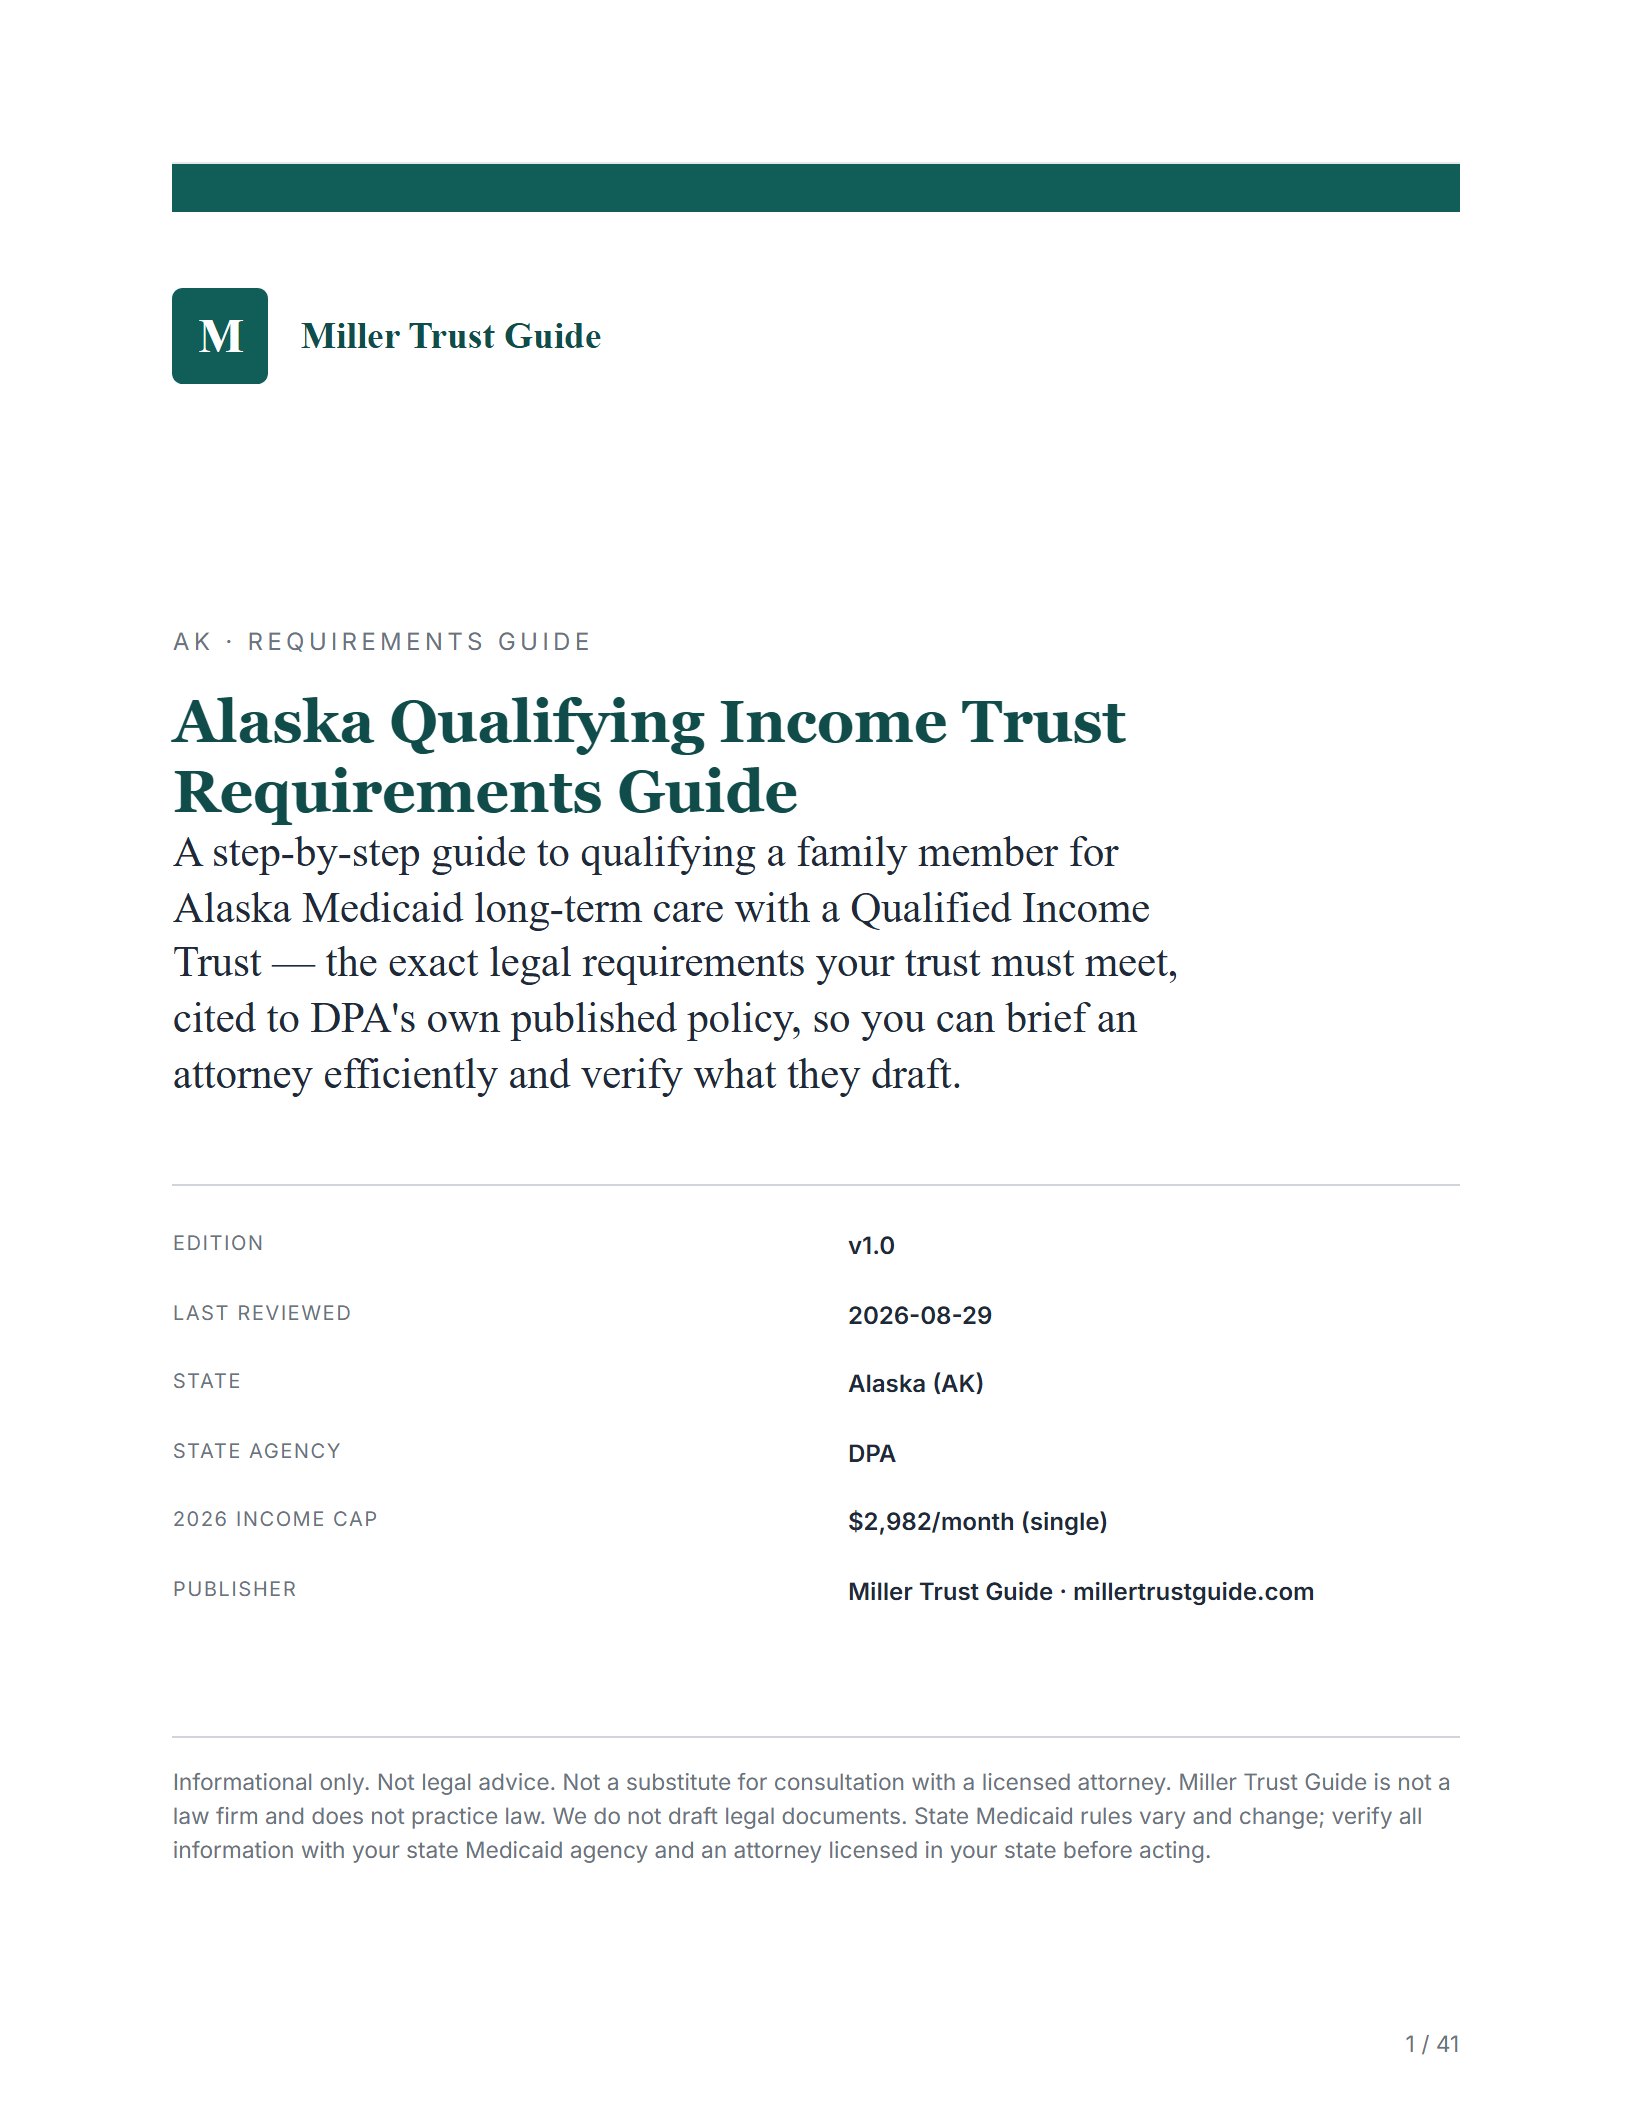
Cover & key facts
Version, last-reviewed date, the 2026 income cap, and the disclaimer — all on page 1.
View page -
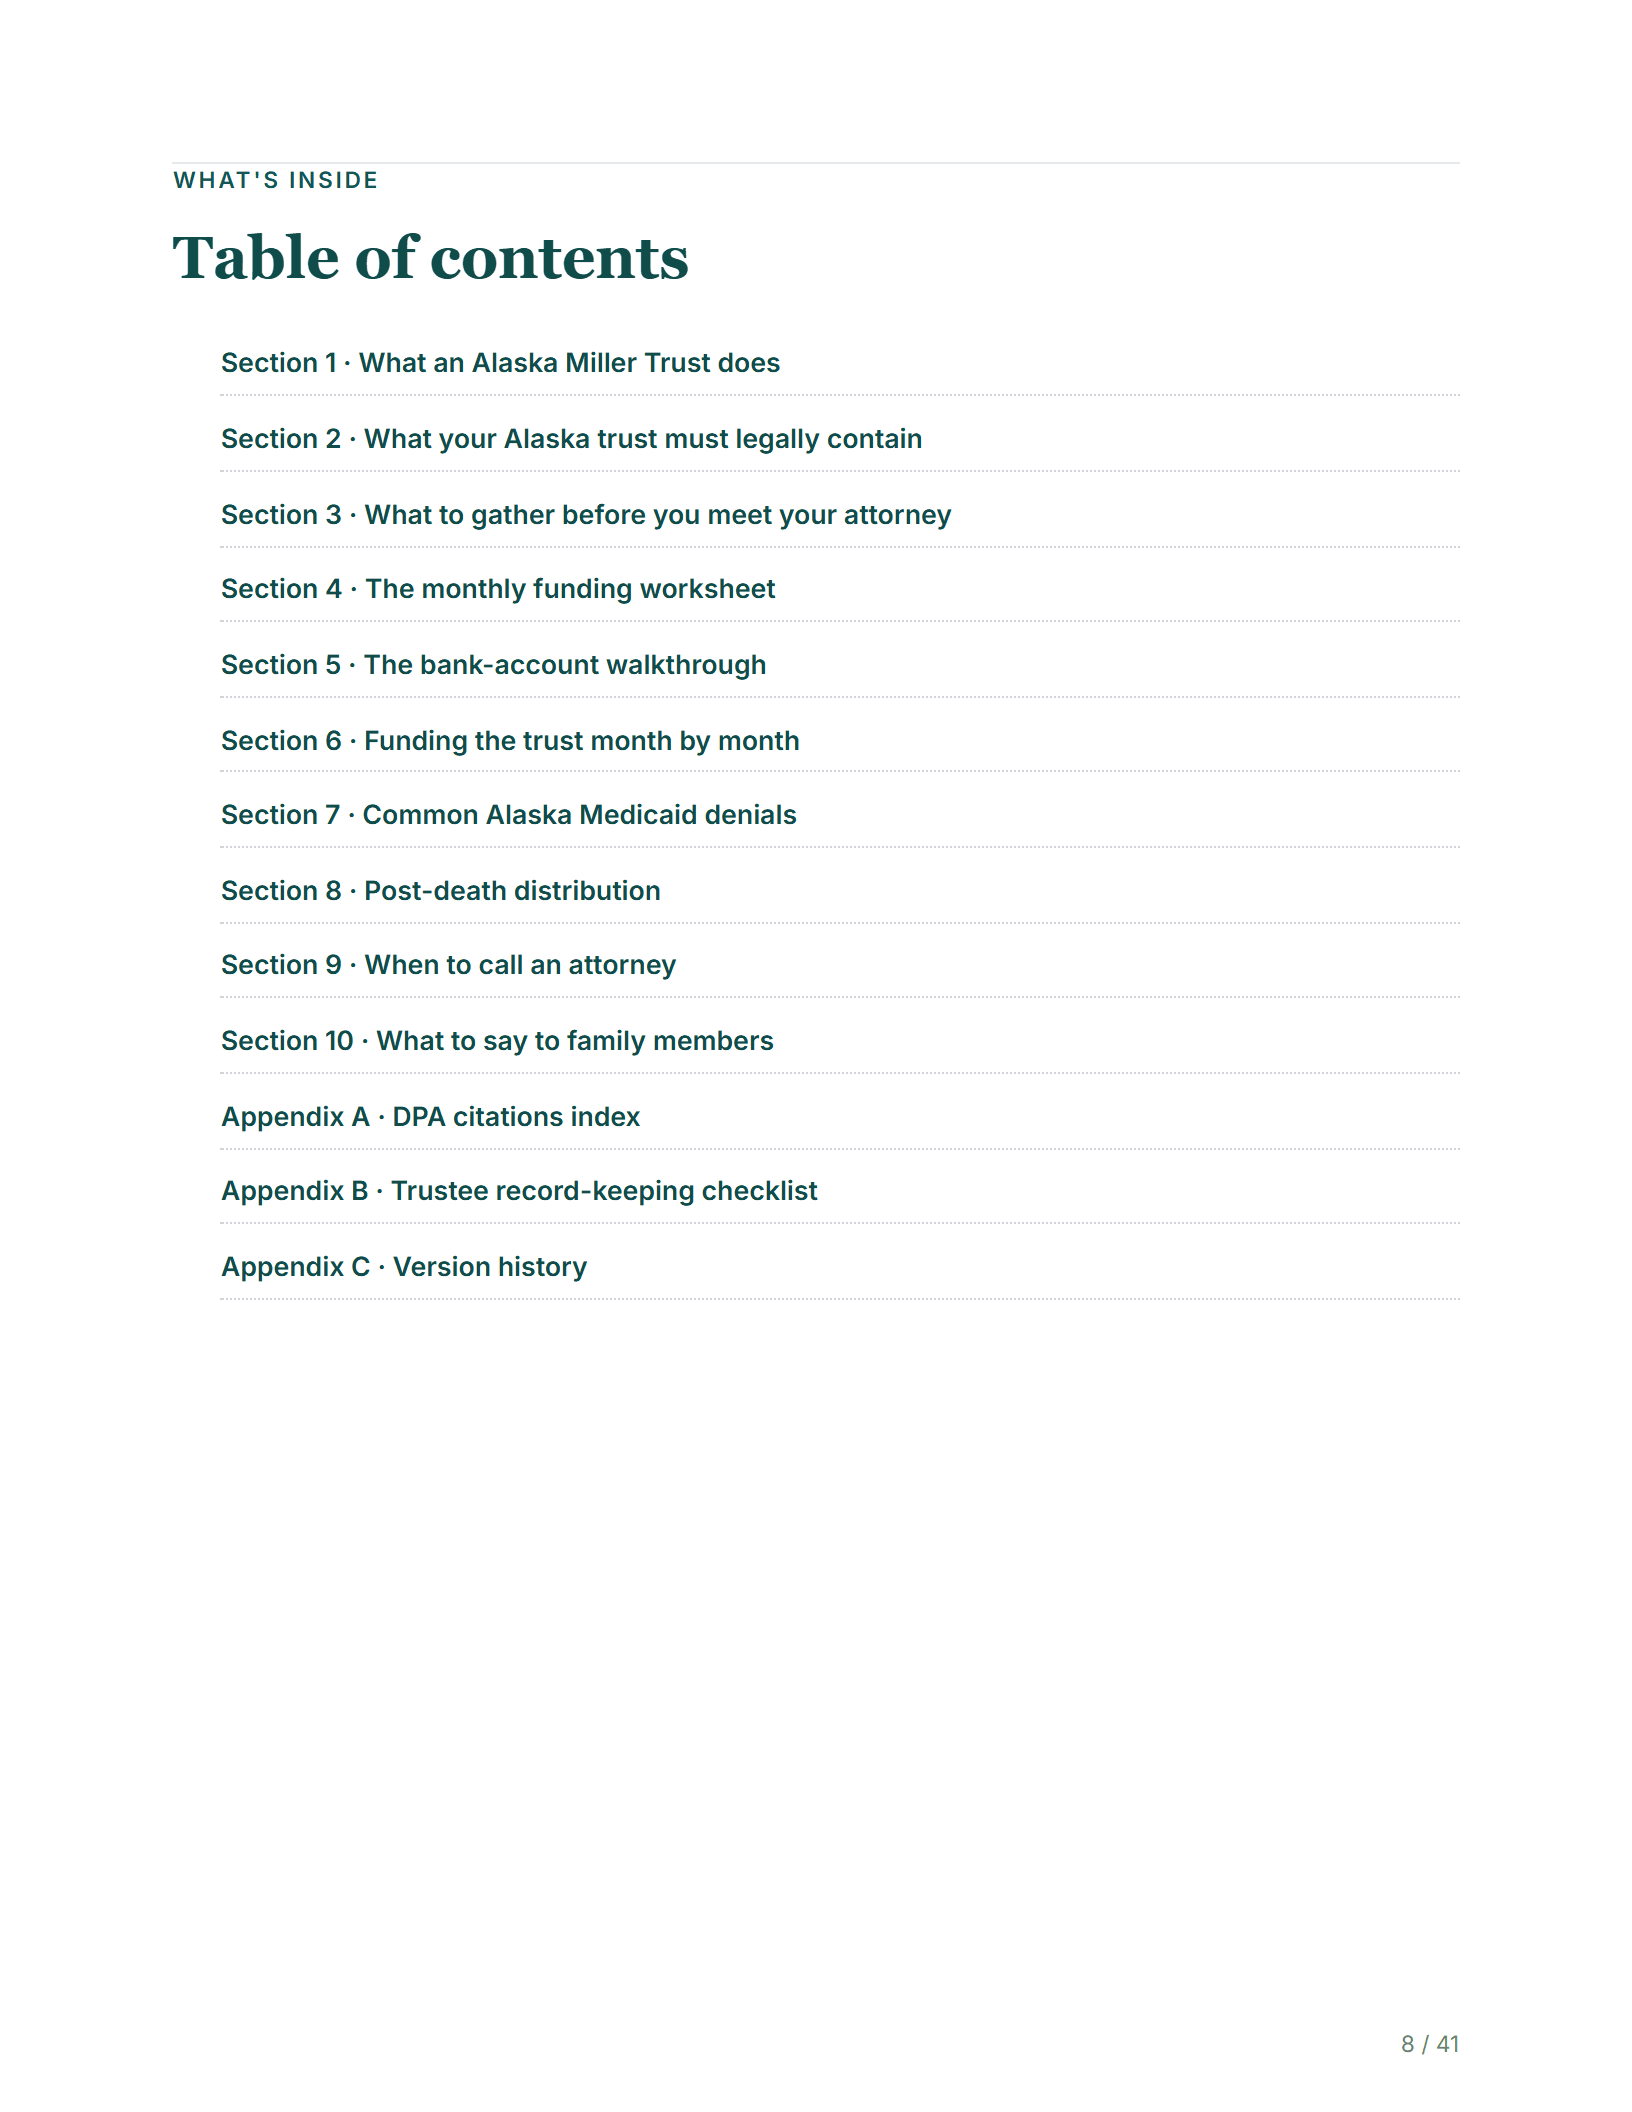
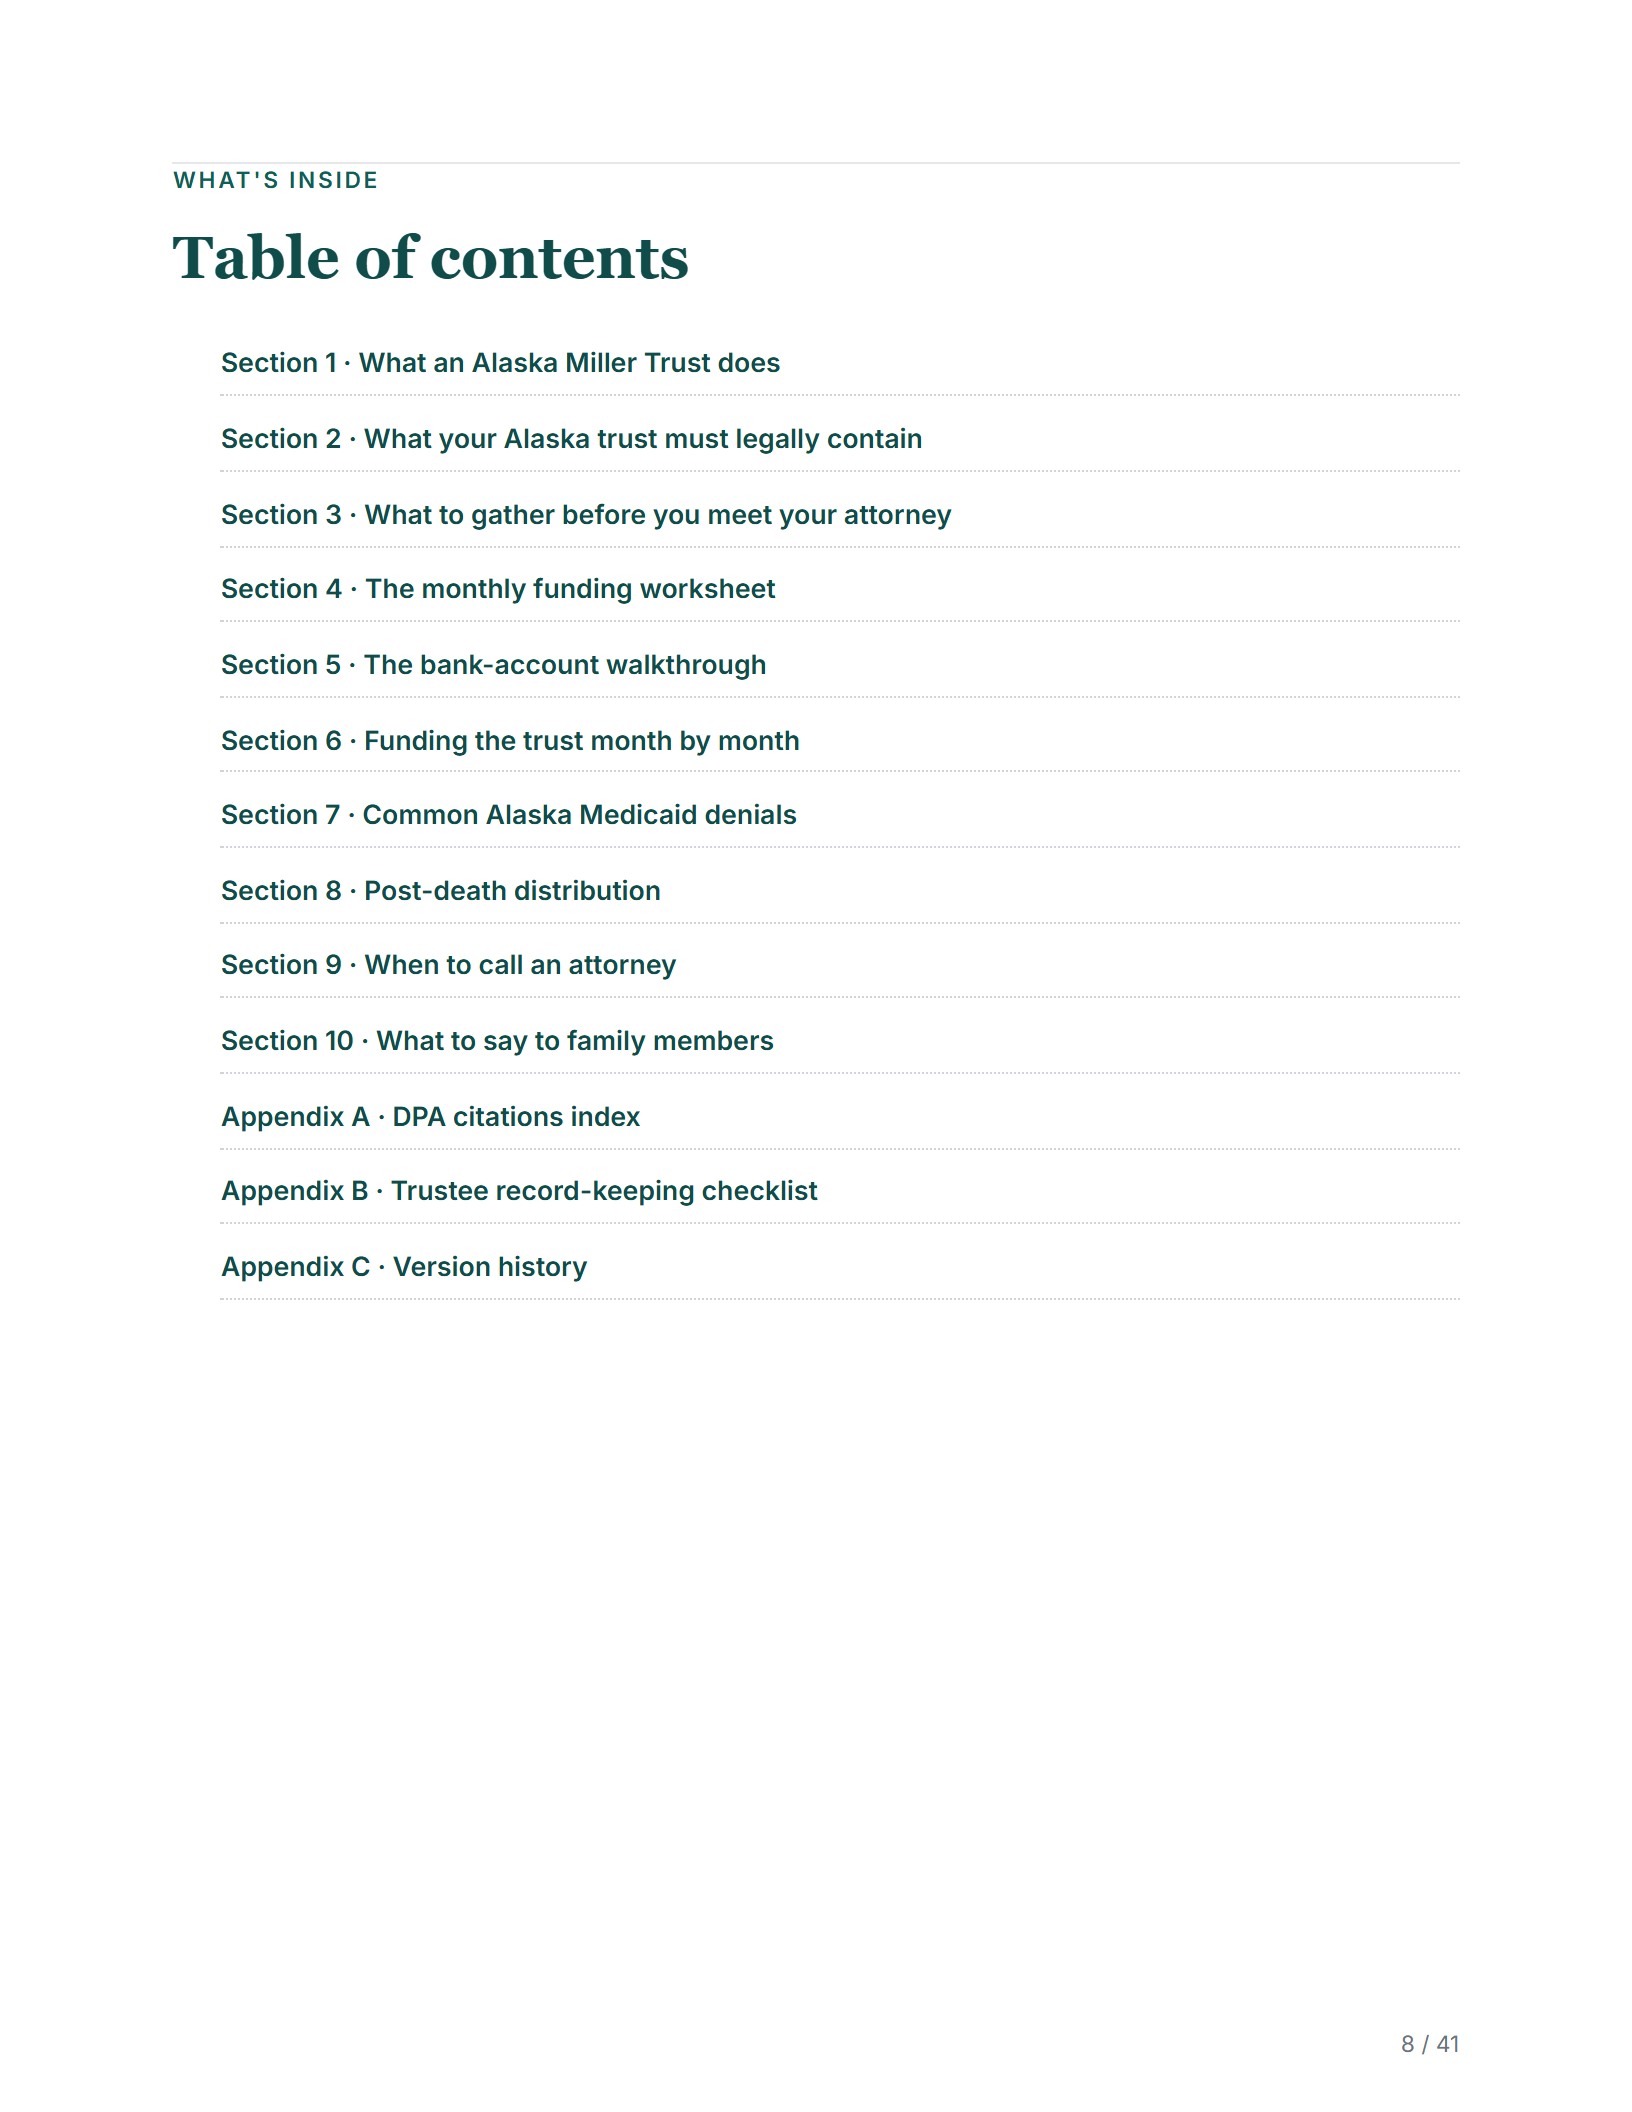
Table of contents
Ten operational sections plus three reference appendices. Every section in the order you'll use it.
View page -
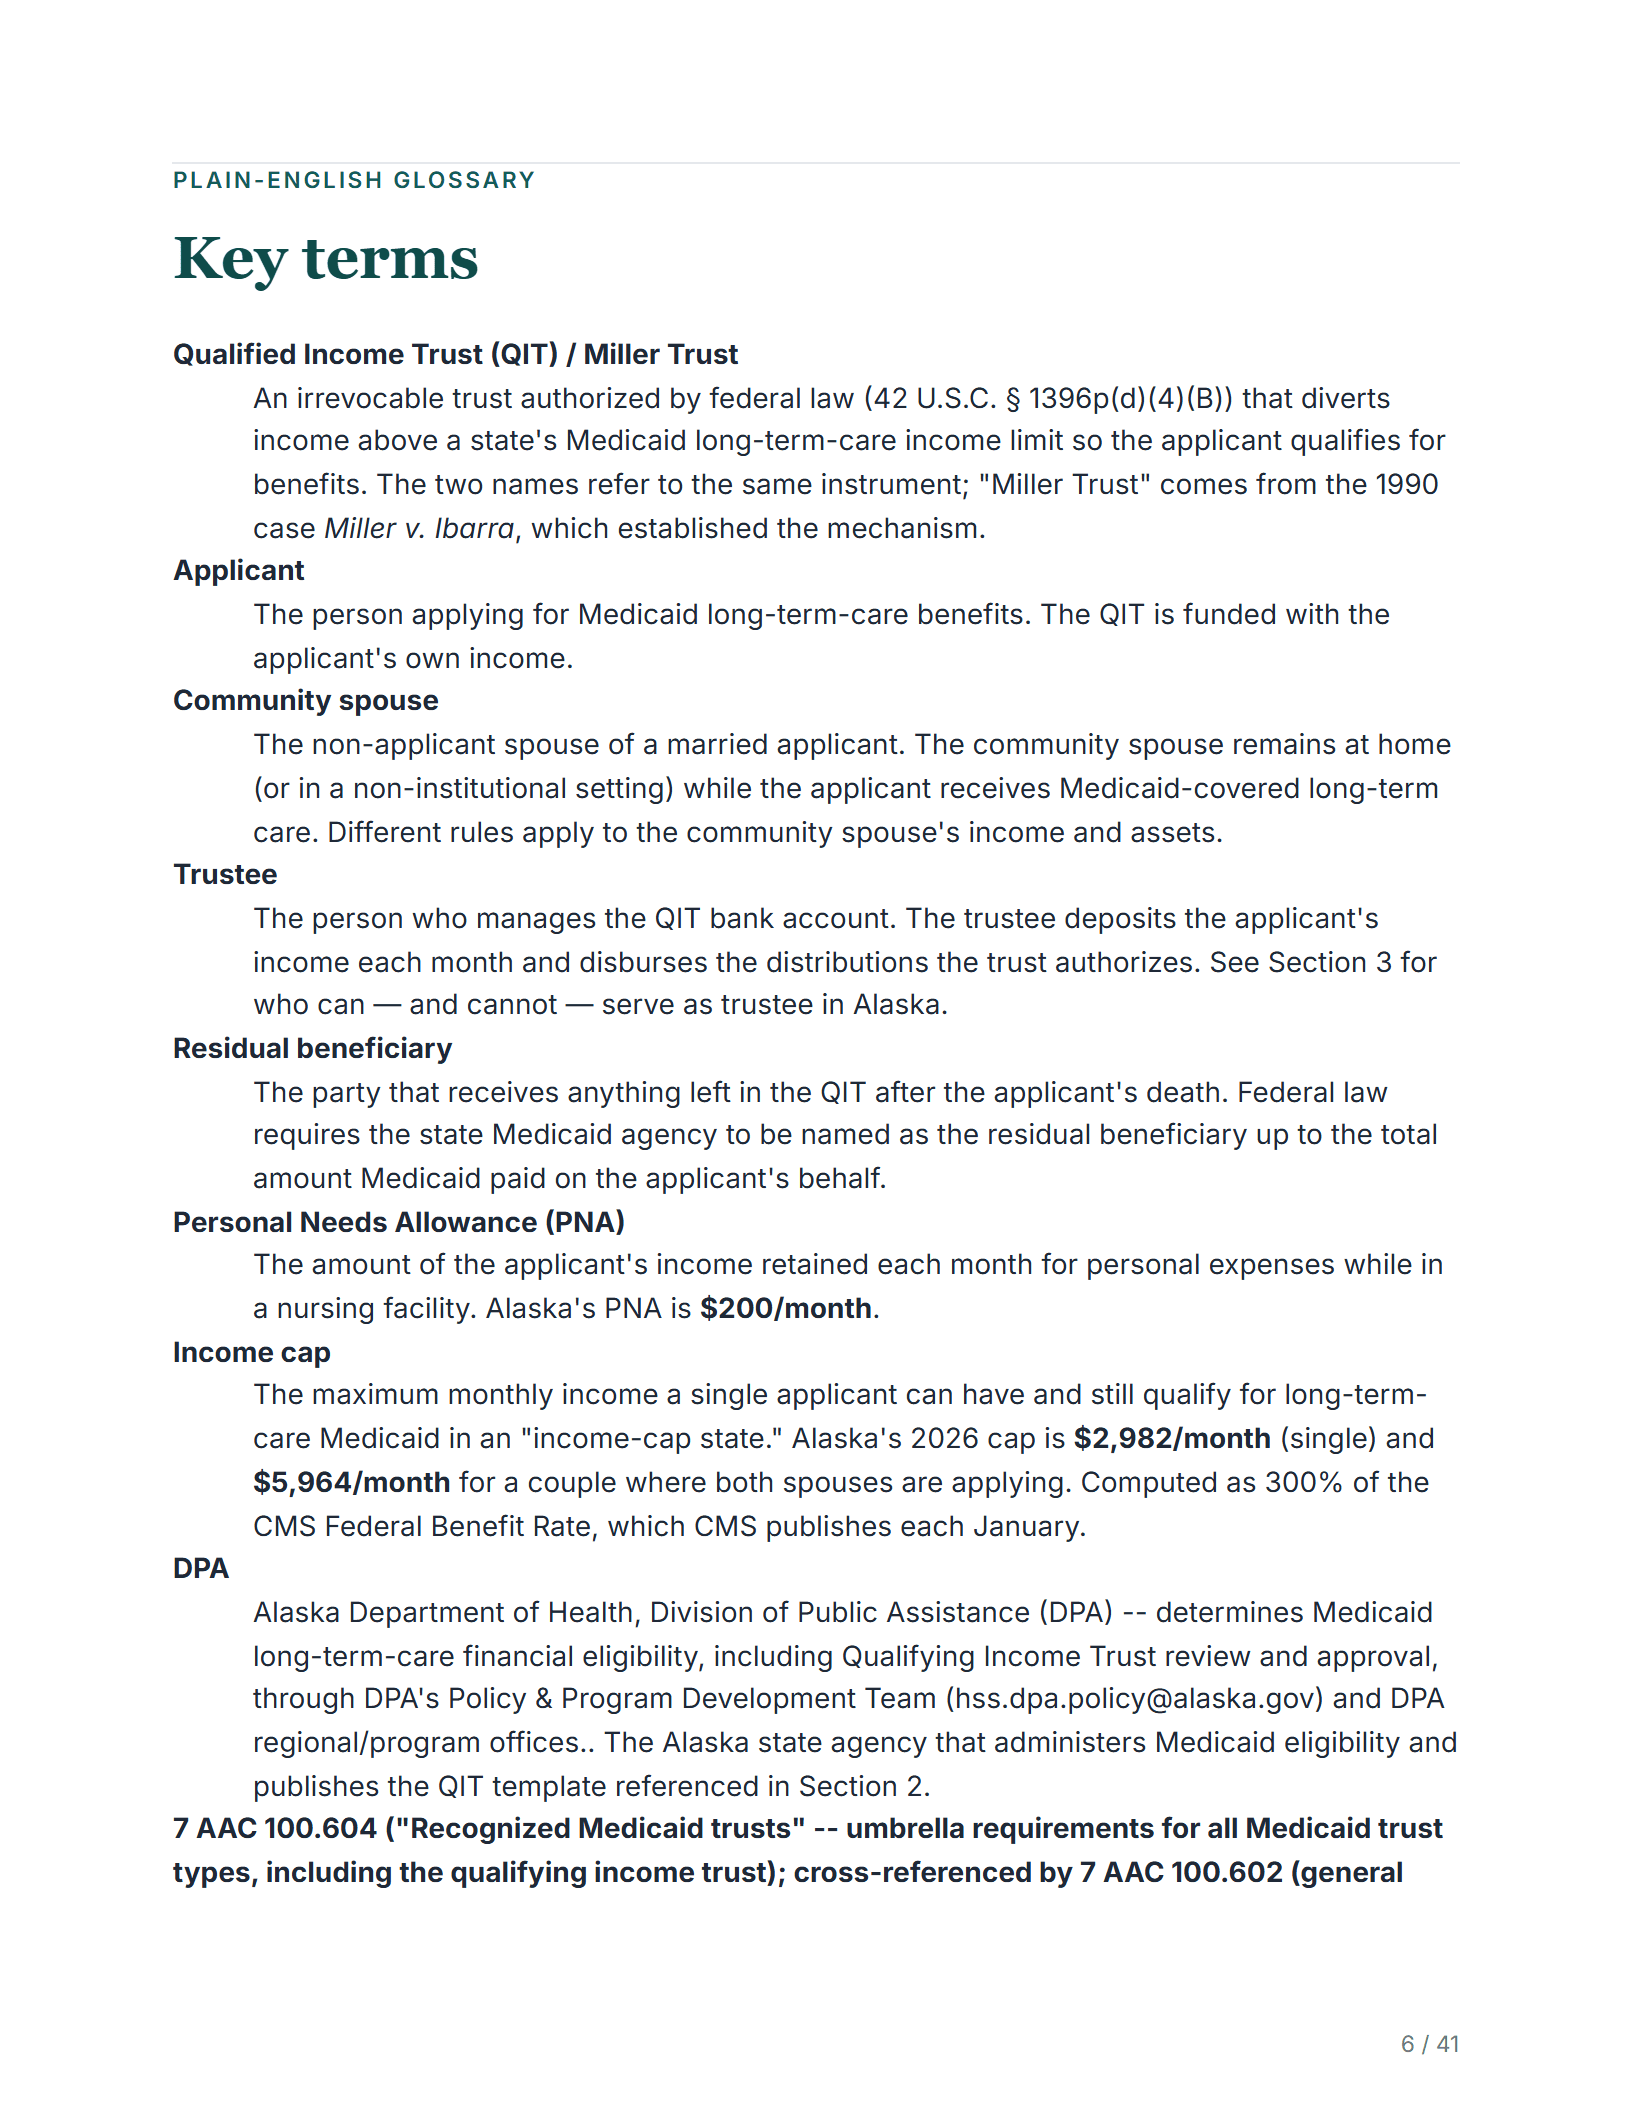
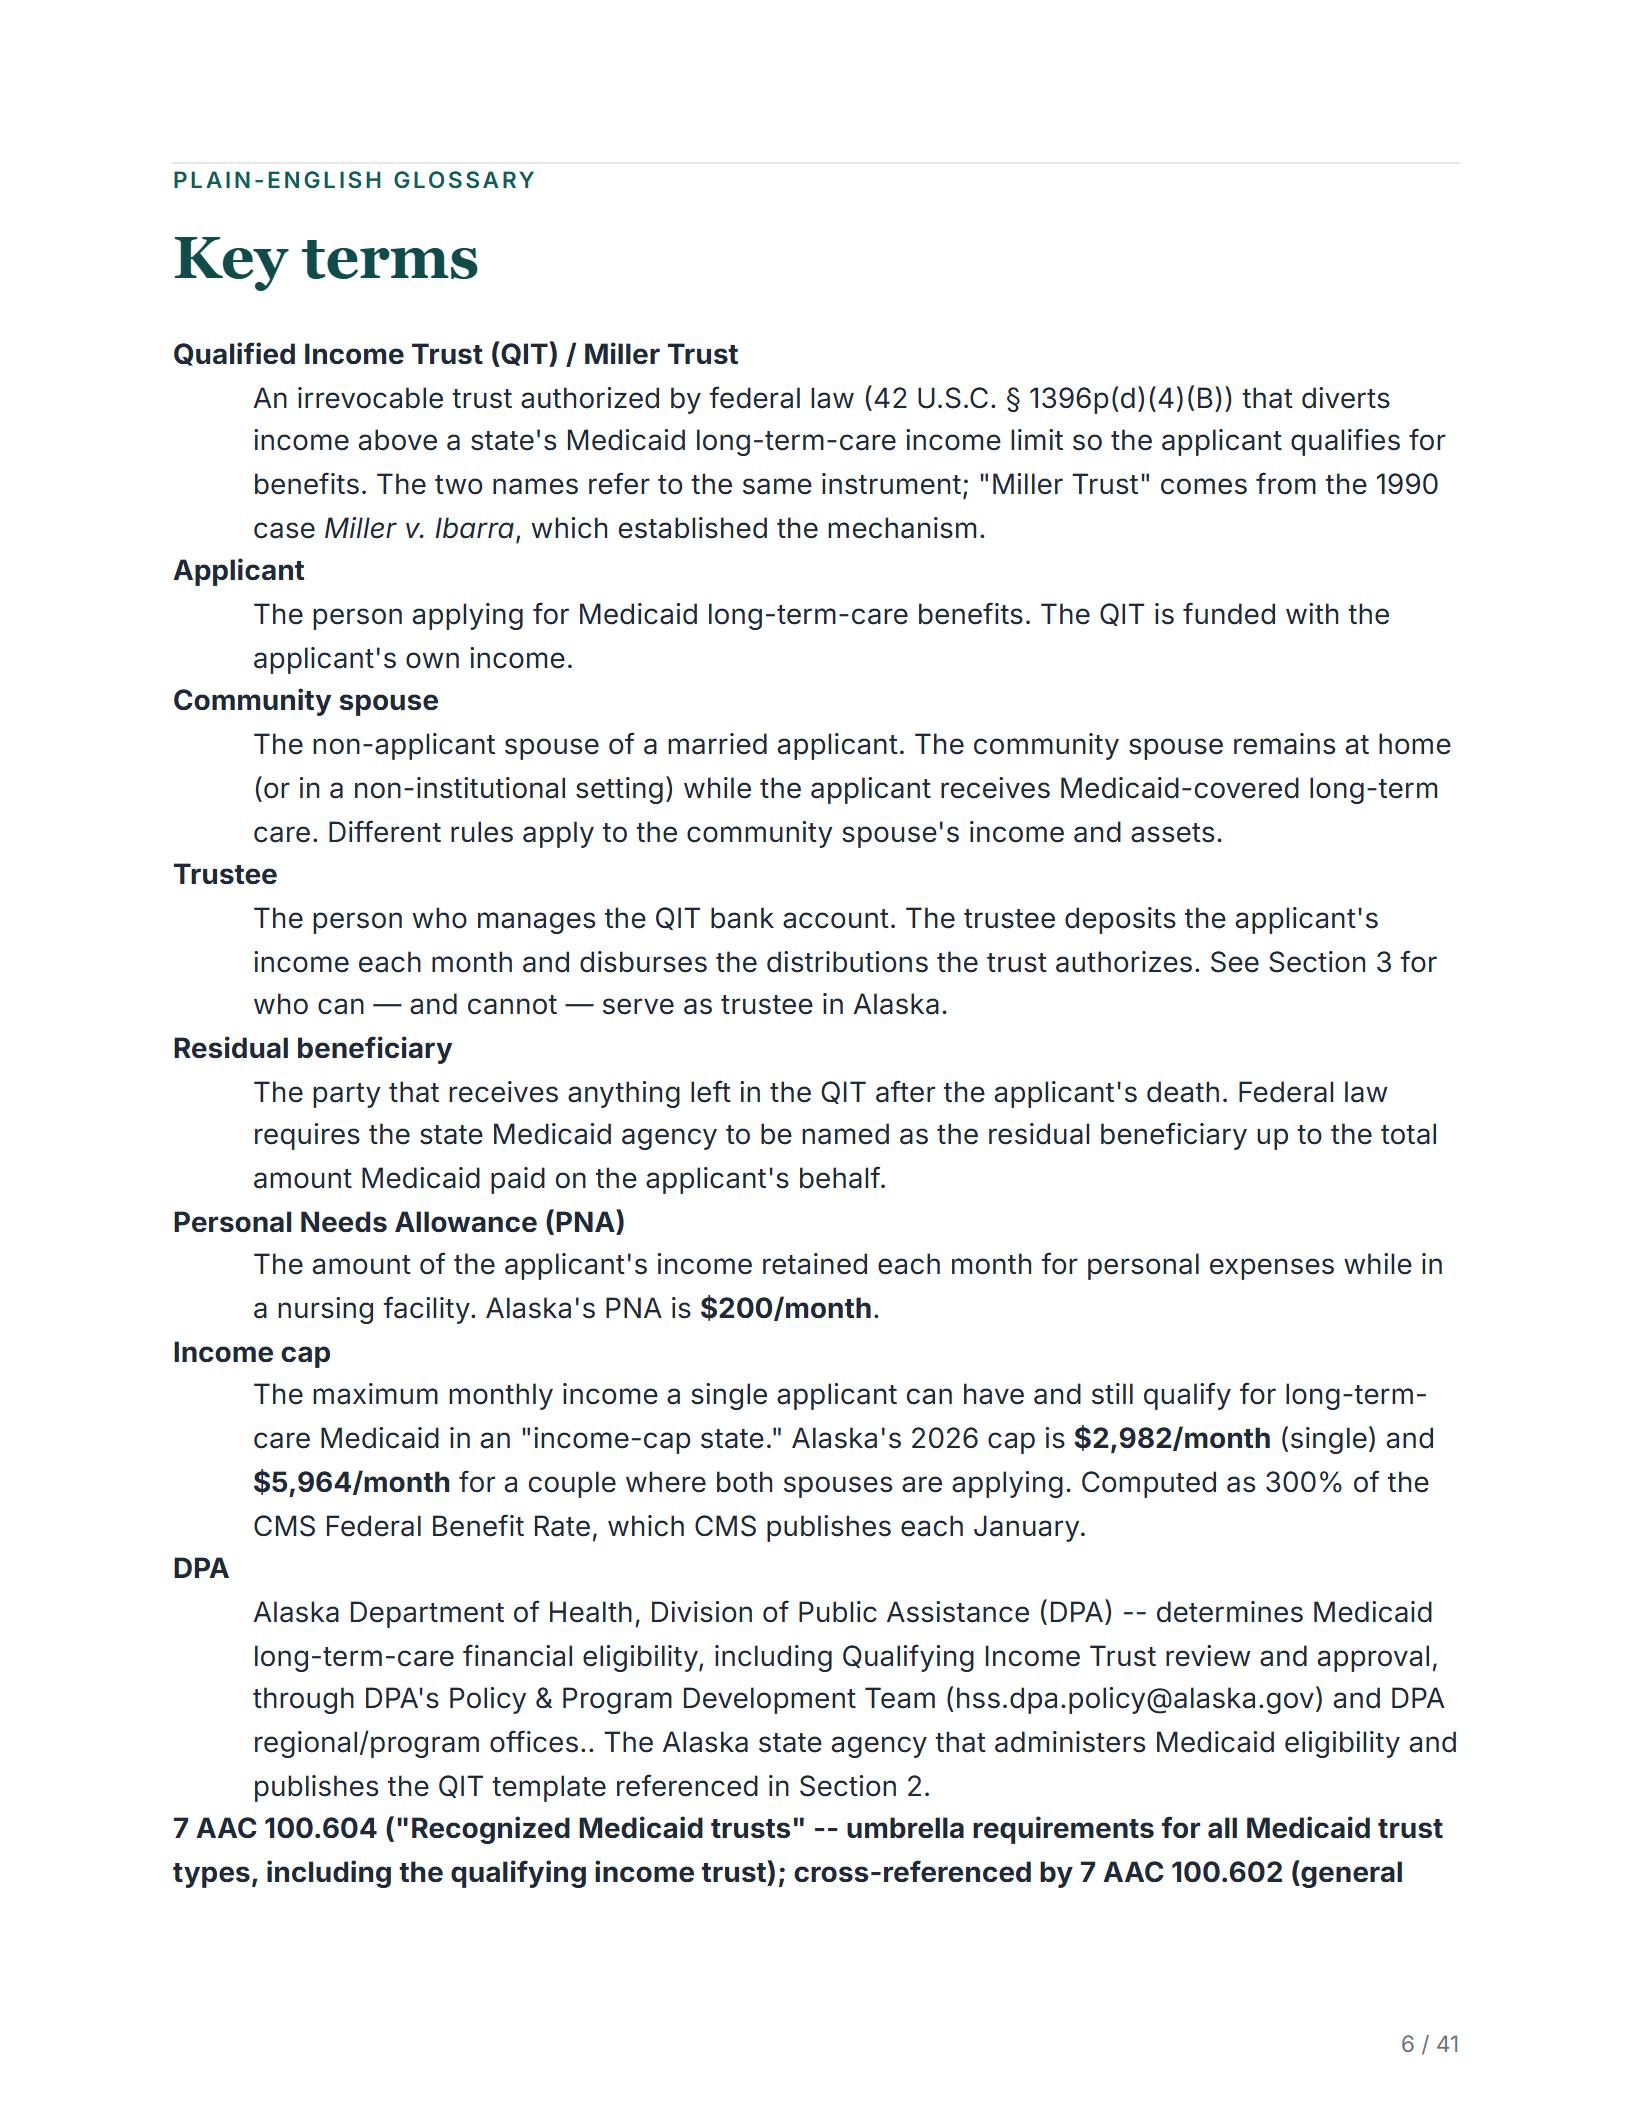
Plain-English glossary
Eleven key terms translated for a non-attorney reader. The vocabulary the rest of the kit assumes.
View page -
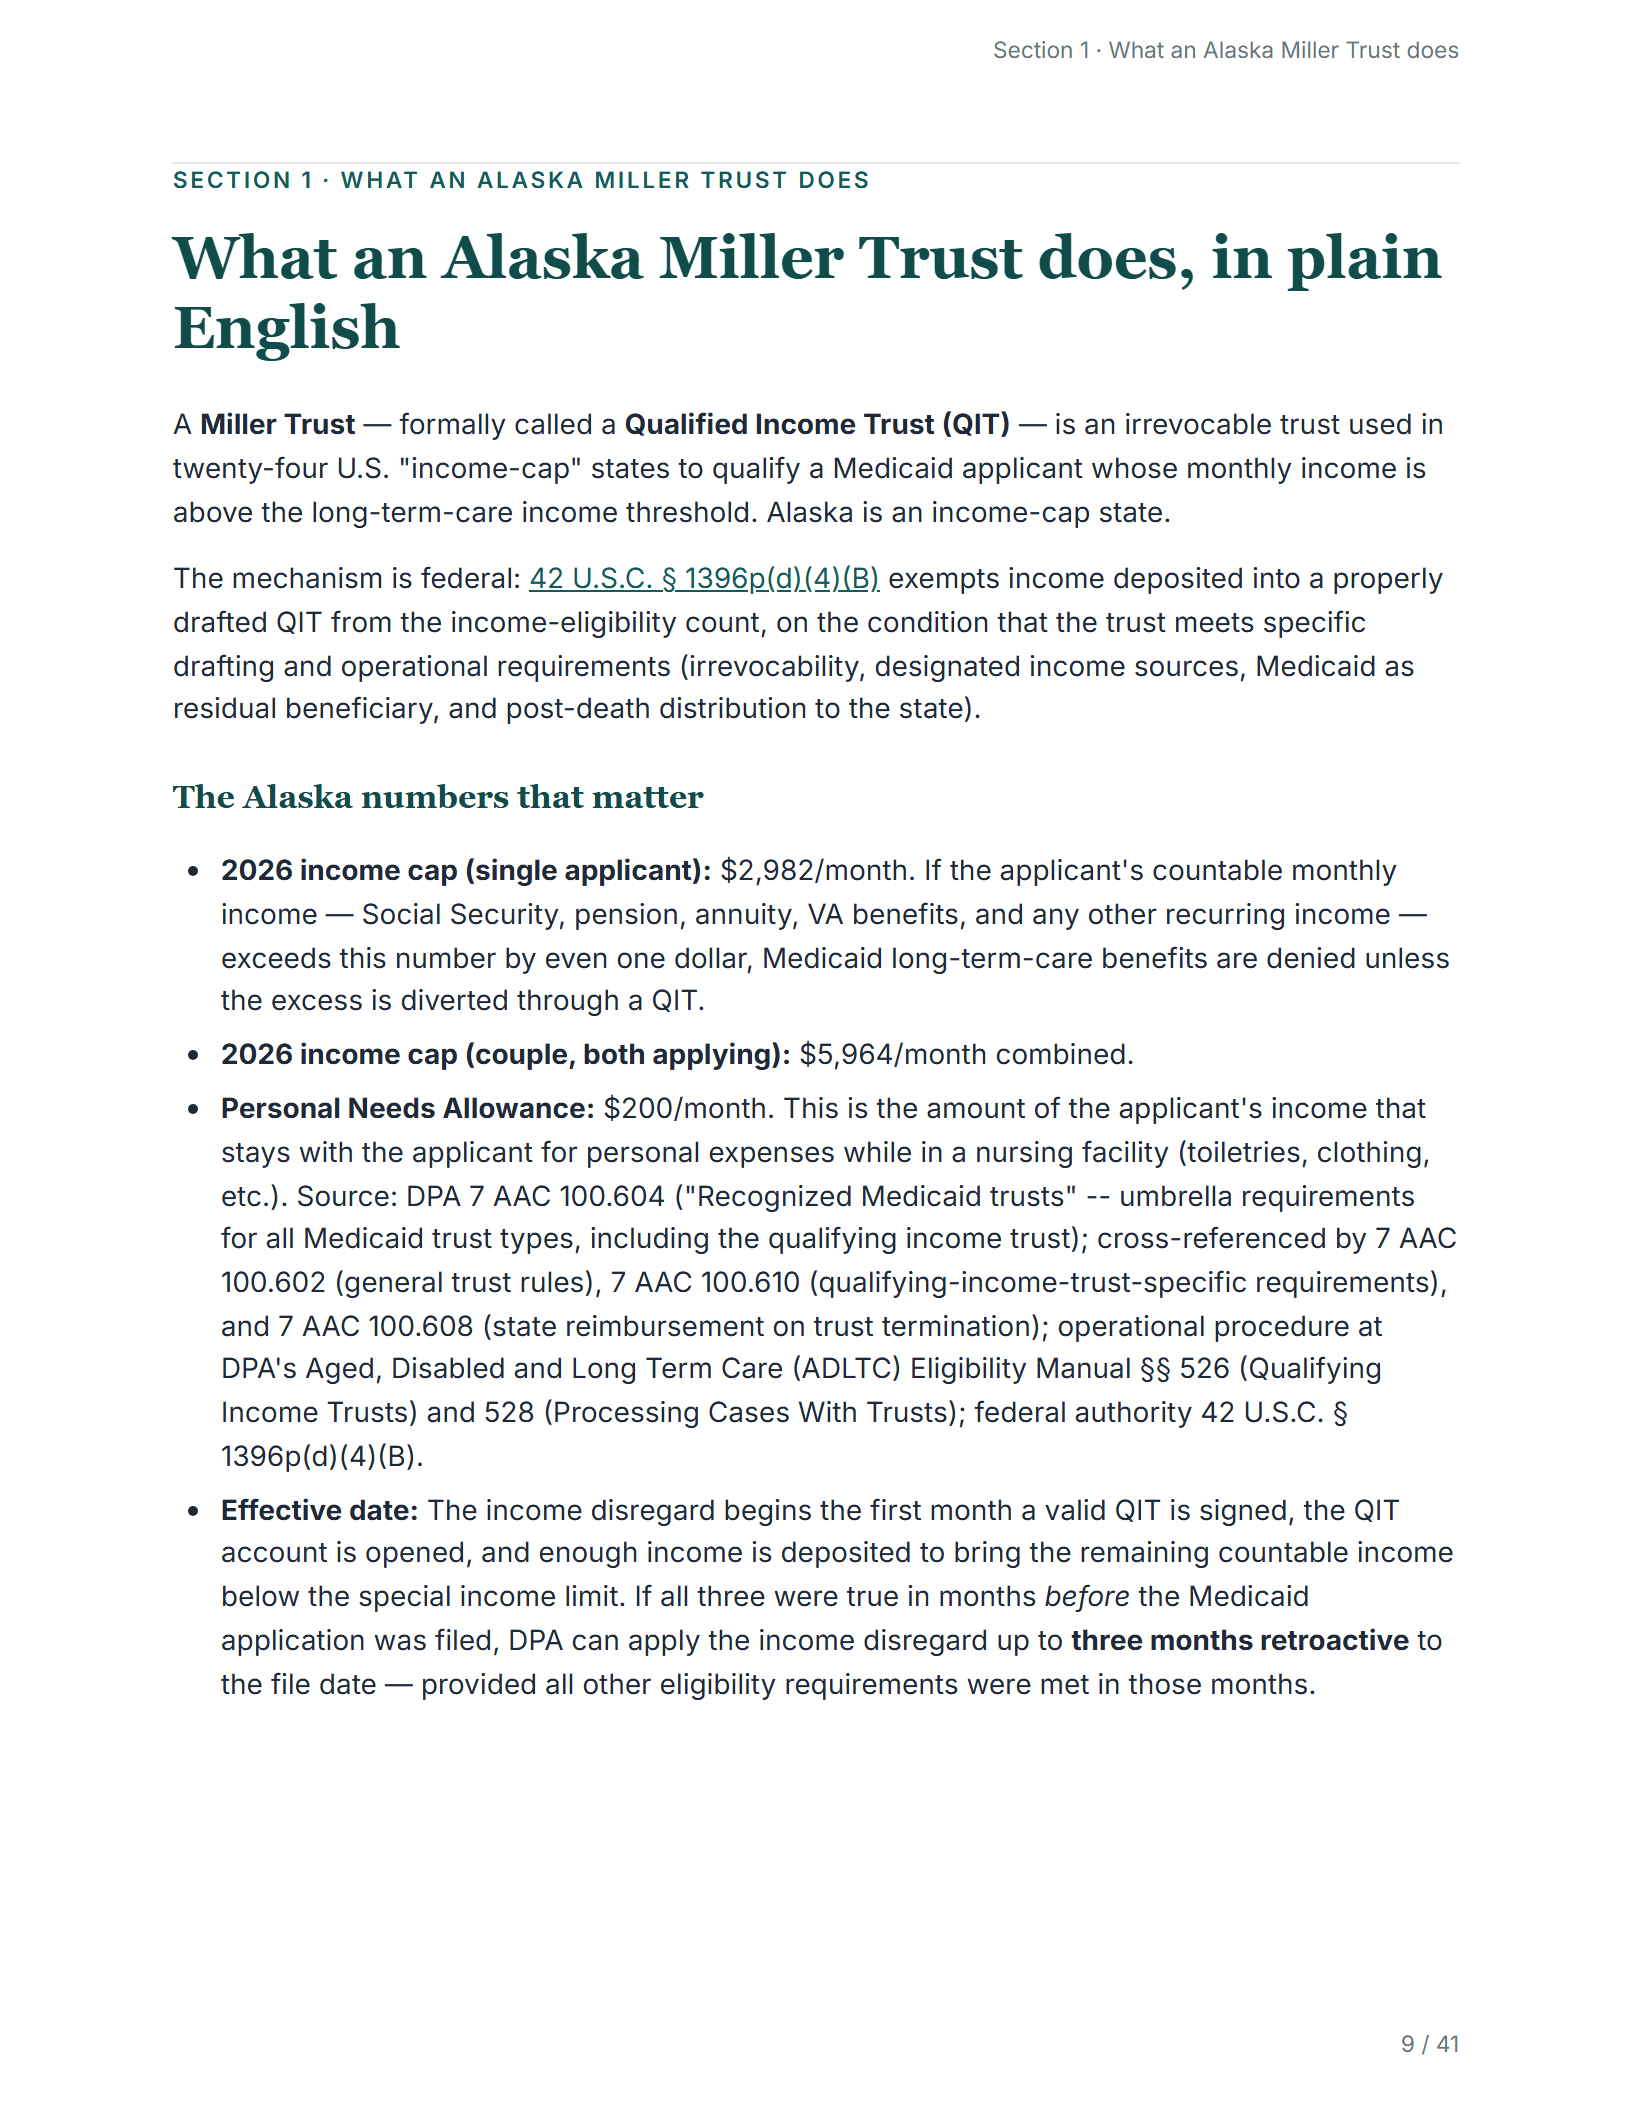
What it does, in plain English
The mechanism explained in plain language, cited to the federal statute, with your state's exact income cap and Personal Needs Allowance built in.
View page -
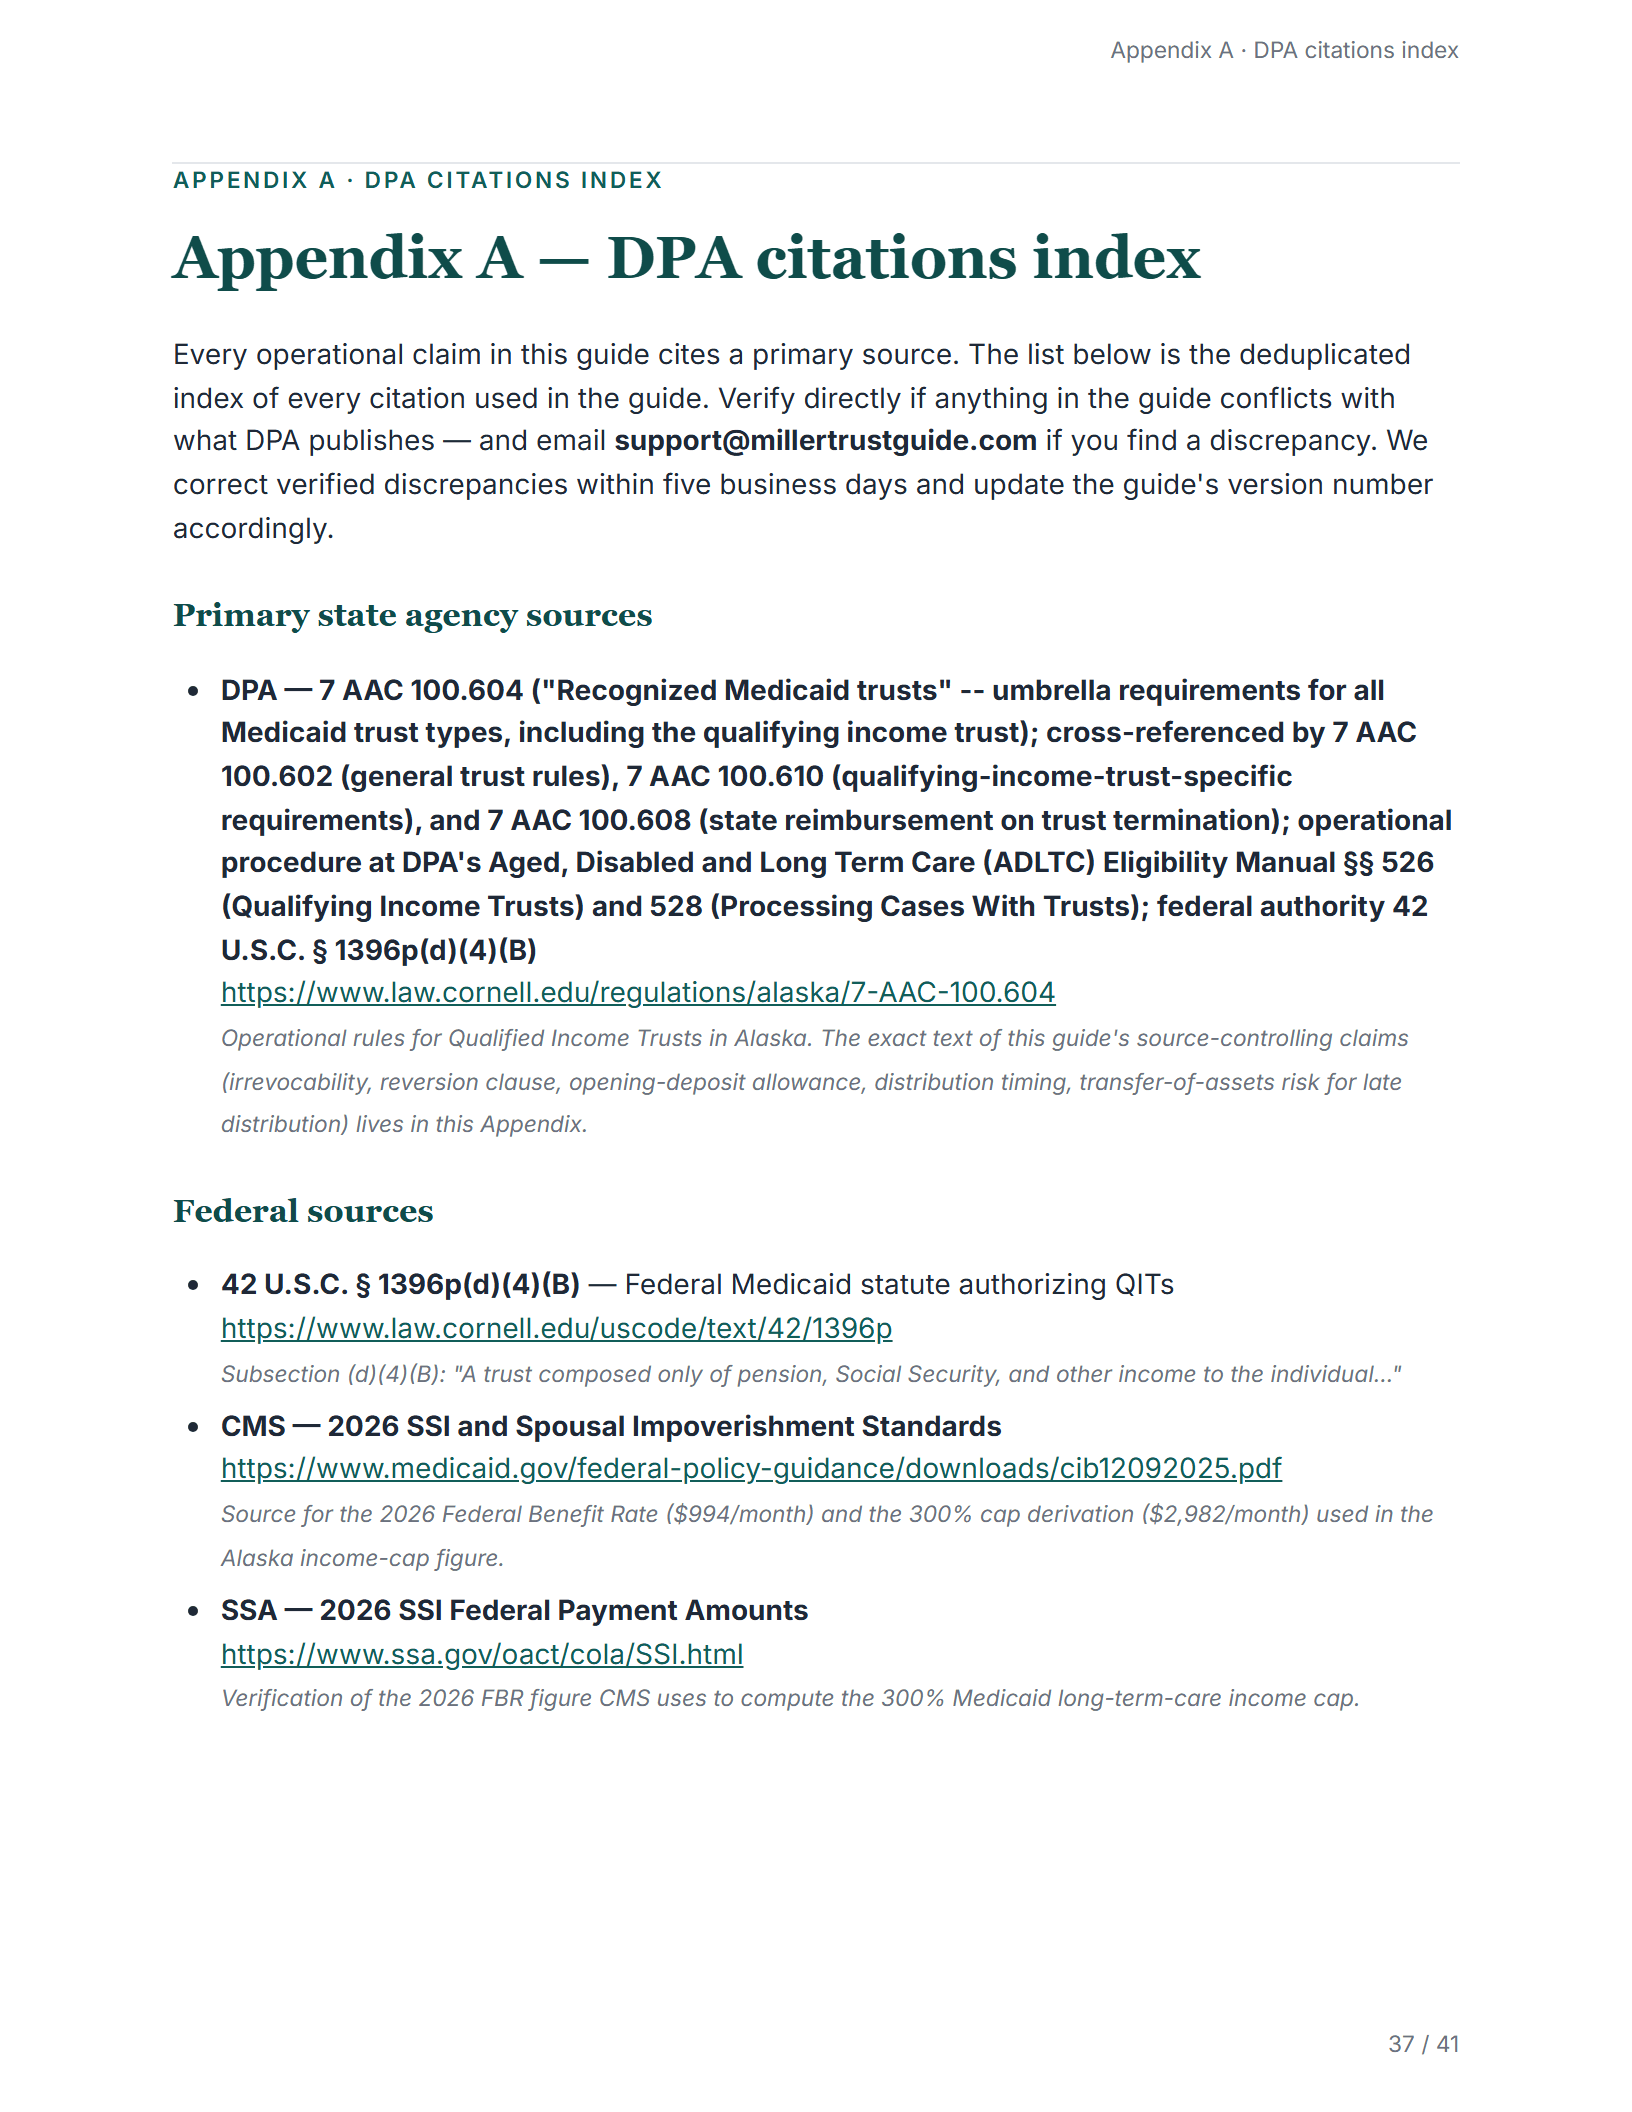
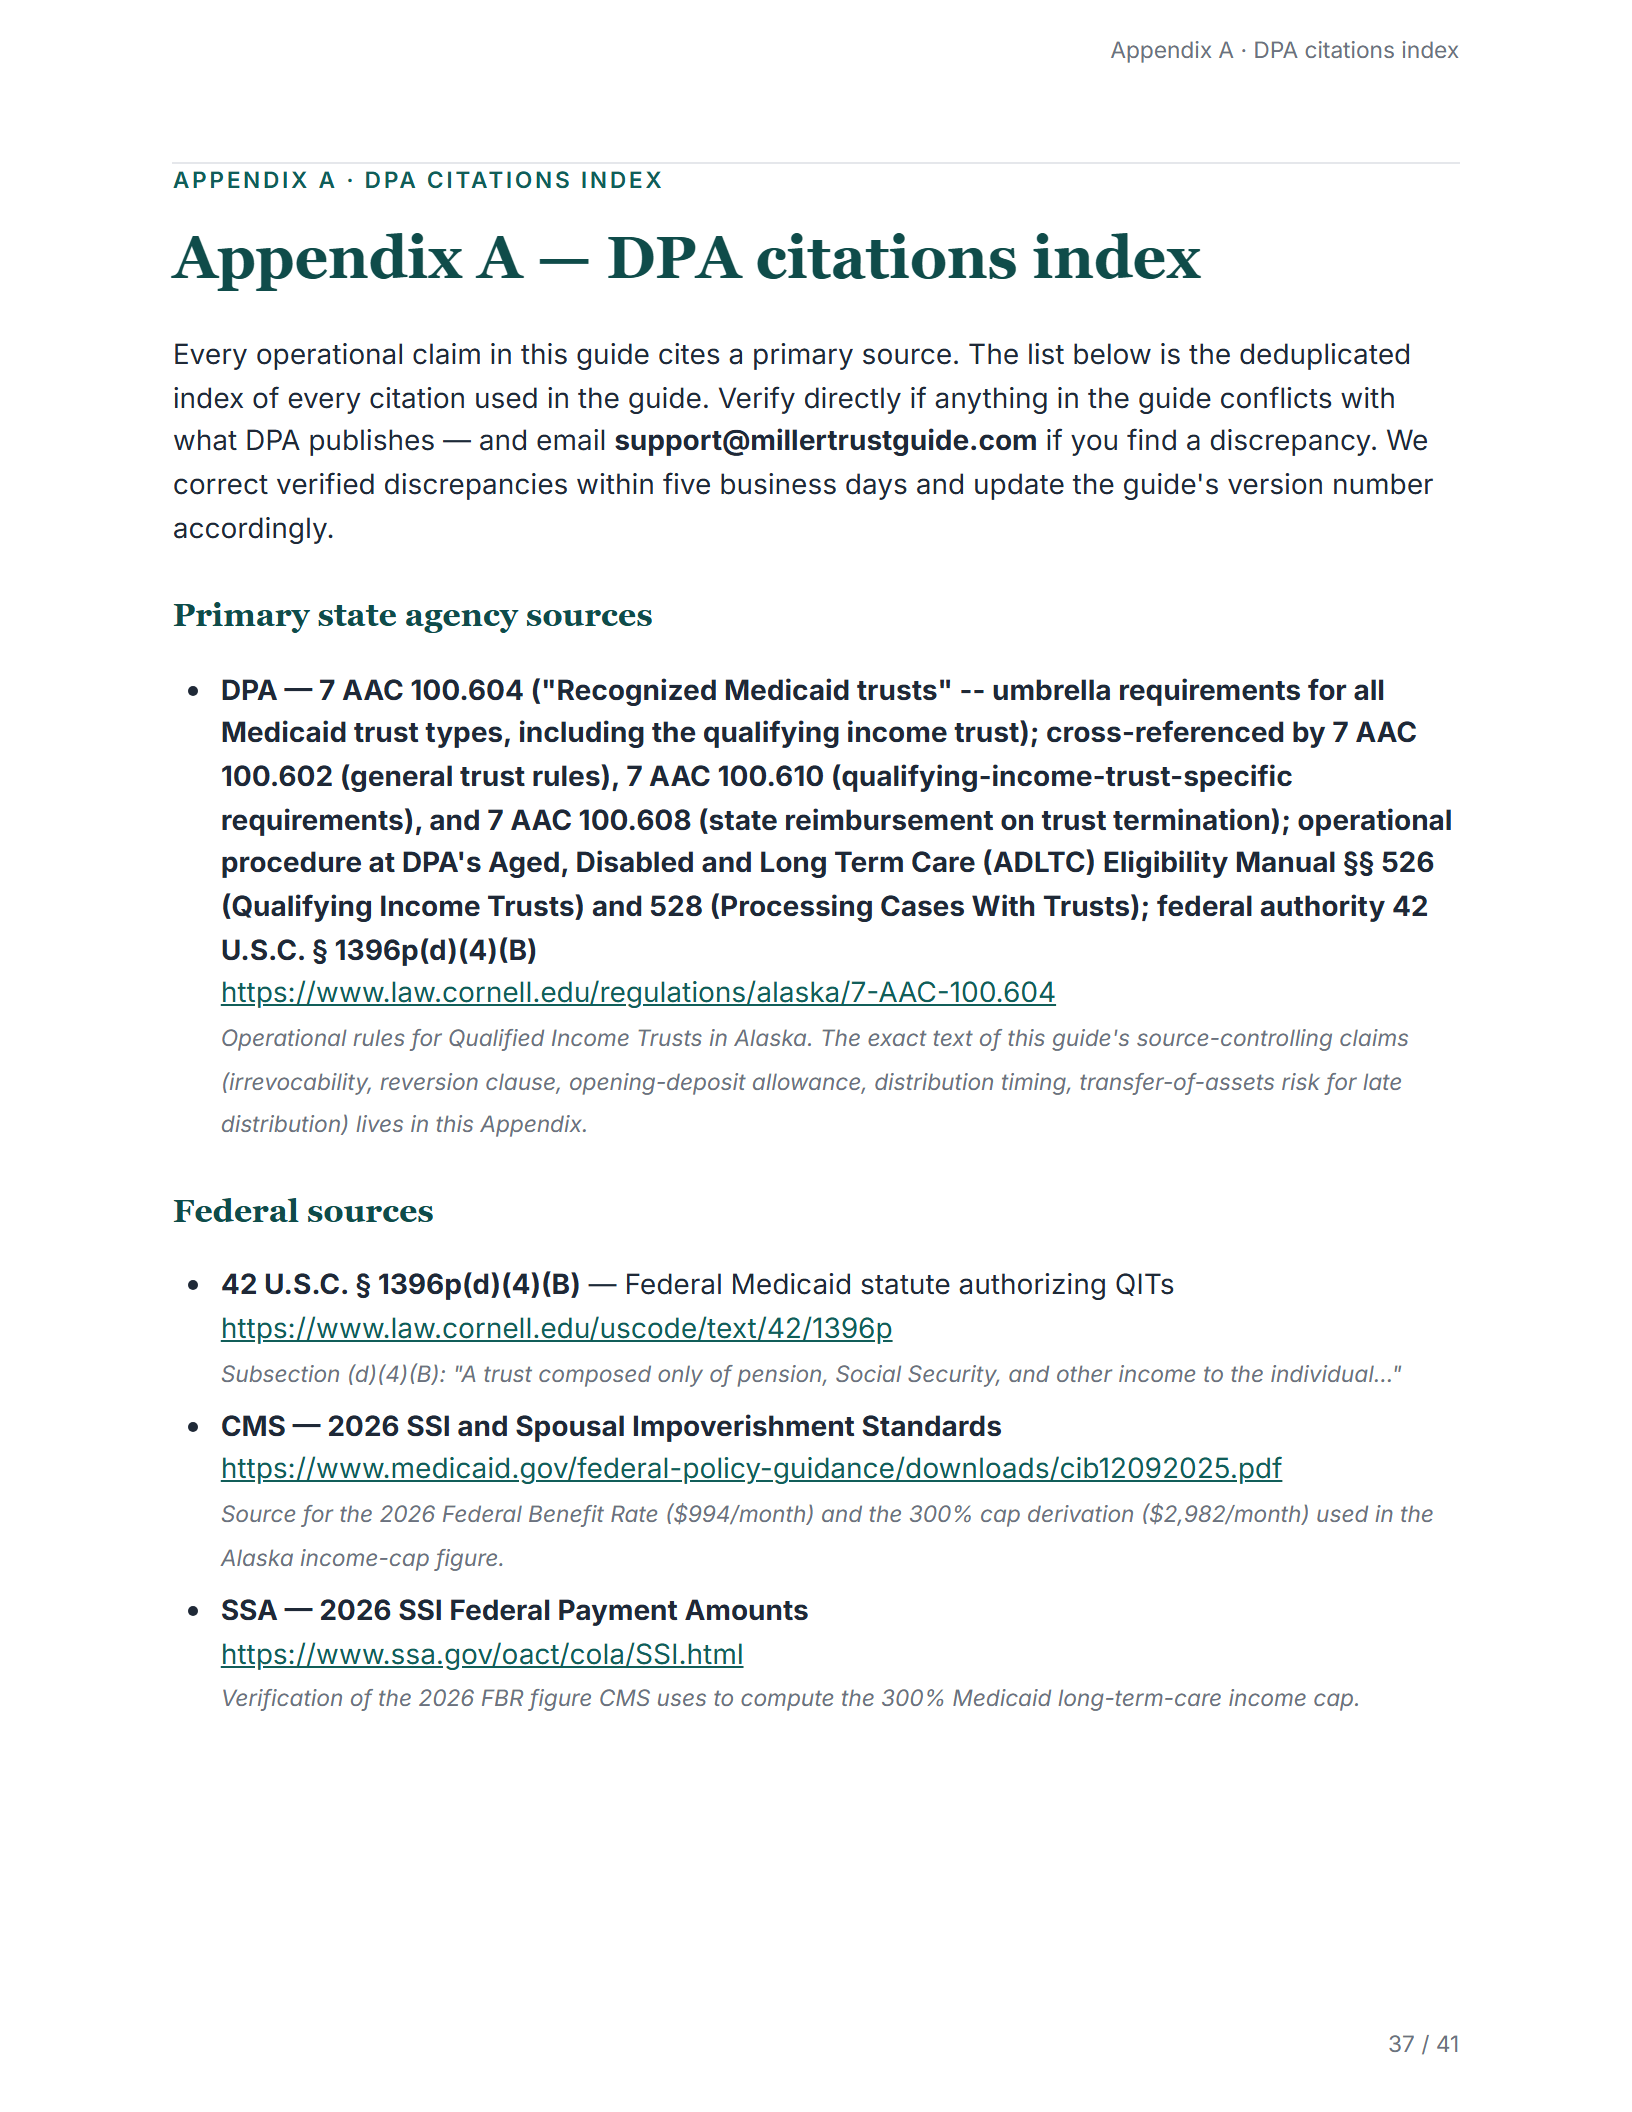
Citations index
Every operational claim sourced to a primary state-agency, CMS, SSA, or federal-statute citation.
View page
Print-friendly, readable on a phone or tablet, and designed to be taken to the bank. Every operational claim cites a primary state agency or federal source.
How this compares
Alaska doesn't publish a fill-in QIT form, so an attorney drafts the trust either way. The $97 is for the guide — the requirements checklist and everything around it — that turns the attorney's job into drafting alone, instead of research-and-drafting on your bill.
| This guide | Attorney alone (no prep) | DIY research, no guide | Doing nothing | |
|---|---|---|---|---|
| Cost | $97 + attorney's drafting fee | $1,000–2,500 (research + drafting) | $0 upfront — real risk of a rejected trust | $0, then $8,152–$8,517/mo private-pay |
| Time to qualified | Faster — drafting only | 2–6 weeks (research + drafting) | Unpredictable | Not until you act |
| Bank-refusal script | Yes | Sometimes | No | n/a |
| State agency citations | Yes | n/a | If you find them yourself | n/a |
| Updated for the current income cap | Yes | Yes | If you catch the update | n/a |
| "What to say to family" script | Yes | No | No | n/a |
| Delivery time | Instant (guide); attorney schedules separately | After consult + retainer | Instant, but unverified | n/a |
Attorney costs reflect typical Alaska elder-law retainers for a Miller Trust setup. Private-pay nursing-home figures reflect recent Alaska market averages.
The bank step
The bank refusal nobody warns you about
You walk into your branch with the signed trust. The teller calls a manager. The manager has never seen one. They ask for an EIN. They tell you to come back with an attorney. You drive home with an empty trust account and a Medicaid clock ticking.
This is the single most common reason Alaska families lose a month of benefits, and it has nothing to do with the trust itself — it is a bank-procedure problem. The guide's bank section gives you the exact language to cite at the counter, the DPA policy reference to read aloud, and a printable resolution letter you can hand to the branch manager so they can escalate inside their own bank instead of sending you away.
Refusals the guide walks you through:
- Branch asks for a tax ID (EIN) for the trust account.
- Branch is unsure what kind of account this is.
- Branch wants to know who is authorized to sign.
- Branch has never opened a qualifying-income-trust account before.
- Deciding how much income to deposit each month.
Each refusal has a corresponding response in the guide, with the DPA citation behind it.
The thing that saves a second trip: bring the printed DPA policy page to the counter — not just the signed trust. A teller who can read the rule in black and white escalates in minutes; one who only has your word for it sends you home. The guide tells you exactly which page to print and hand across.
If DPA rejects the trust, you pay nothing.
If the denial is for a reason traceable to following the guide, email the agency's stated denial reason to support@millertrustguide.com and we refund the full purchase price within one business day. Report it within 30 days of purchase if you can. If DPA hasn't decided by then, email us anyway: the guarantee still applies once you have the denial. No phone tag, no forms, no fight. Changed your mind for any other reason? You have 7 days, no questions asked. We'd rather lose the sale than make this harder on a family already dealing with enough. Full refund policy.
Avoid these
The 6 most common Alaska denial reasons
Every denial reason below cites DPA policy. The full guide explains each one in context and the order in which to verify them before submitting the Medicaid application.
Trust doesn't meet all recognized-Medicaid-trust requirements -- treated as a general trust instead
Trust not registered with an Alaska court, or registration not verified
Non-income asset placed in the trust
Beneficiary retains access to or control over the trust account
Missing or defective state remainder-beneficiary (payback) clause
Bank statements show discrepancies, or income isn't actually being deposited
Before you go to the Alaska bank
Most wasted trips are a bank-procedure problem, not a trust problem. This free one-pager has the questions to ask on the phone before you drive to a branch — emailed now. We'll also send 4 short follow-ups over the next 10 days (what the bank will ask, why denials are paperwork not eligibility, what other buyers found, when to call an attorney) — then we stop. No ongoing newsletter.
The author
Who's behind this
I'm James Whitfield. I built this guide to close the gap between an attorney-drafted document and a funded Medicaid trust (the short version is up top). I'm not an attorney. I'm a researcher who has now read every DPA policy section that covers Qualified Income Trusts, and I publish what I learned with a citation on every claim. I won't advise you on your specific situation, draft anything, or review a document you or your attorney have drafted; for advice on your situation, you need an Alaska-licensed attorney.
Questions
Frequently asked questions
Is the Alaska Qualifying Income Trust Guide legal advice?
Does Alaska provide an official Qualifying Income Trust form?
What does the guide include?
Do you provide the trust document itself?
Who needs a Qualifying Income Trust in Alaska?
How much of my income has to go into the trust?
What is Alaska's Personal Needs Allowance?
Is Social Security counted before or after the Medicare Part B premium for Alaska's income cap?
Once money is in the trust, what is the order of monthly payments out?
Can I be my own trustee in Alaska?
Does an Alaska Qualifying Income Trust need an EIN?
Does the trust really need to be registered with a court?
What if my bank refuses to open the trust account?
What happens to the trust after the person on Medicaid passes away?
Do you offer a refund?
Will you talk to me on the phone about my situation?
Which banks will open a Qualified Income Trust (QIT) bank account in Alaska?
When does Alaska Medicaid coverage begin after the Qualified Income Trust is set up?
Can you set up an Alaska Miller Trust without a lawyer?
Can an attorney, paralegal, or care manager use this guide for a client?
Do I need a Miller Trust in Alaska?
What if DPA changes its requirements or the income cap after I buy?
Ready to start?
$97, one time. Instant download. Money-back if DPA rejects your QIT for any reason traceable to following the guide, or for any other reason within 7 days.
The guide itself is instant — the requirements checklist and everything around it, ready before your first call. You walk into that first attorney call with the research and fact-gathering already done.
One last step — confirm below and it's instant from there.
Secure checkout by Stripe · Instant download · Money-back guarantee
One-time charge, no subscription. It shows on your card statement as MILLERTRUSTGUIDE.COM.
Want them to see the whole case? Send them what you just read.
Not ready to buy yet?
Free 5-email series: the funding-month rule, what really happens at the Alaska bank, why most denials are paperwork not eligibility, who manages the trust each month, and the one honest sign it's time to call an attorney instead. Then we stop. No ongoing newsletter, no sales list.
Keep reading
Step-by-step Alaska guides
New to this? What Is a Miller Trust? covers the plain-English basics — what it is, why states use different names for it, and how it differs from a Medicaid Asset Protection Trust. Below are the free operational walkthroughs that go deeper on the questions Alaska families ask most.
Free operational walkthroughs
- How to Set Up a Qualifying Income Trust in Alaska: Step by Step
- How Long Does It Take to Set Up a Qualifying Income Trust in Alaska?
- How Much Does It Cost to Set Up a Qualifying Income Trust in Alaska?
- How Much Does a Nursing Home Cost in Alaska?
- What to Say at the Bank When Opening a Qualifying Income Trust Account in Alaska
- Who Can Be the Trustee of a Qualifying Income Trust in Alaska?
- Do You Need an EIN for a Qualifying Income Trust in Alaska?
- What Happens to a Qualifying Income Trust When the Beneficiary Dies in Alaska?
Primary sources
State agency sources
Last verified against DPA on August 29, 2026. Email support@millertrustguide.com if anything below conflicts with what DPA currently publishes — we correct verified discrepancies within five business days.
Every claim here cites a primary DPA or federal document — see them
Primary state agency sources
- [1] Policy manual: DPA policy manual (section 7 AAC 100.604 ("Recognized Medicaid trusts" -- umbrella requirements for all Medicaid trust types, including the qualifying income trust); cross-referenced by 7 AAC 100.602 (general trust rules), 7 AAC 100.610 (qualifying-income-trust-specific requirements), and 7 AAC 100.608 (state reimbursement on trust termination); operational procedure at DPA's Aged, Disabled and Long Term Care (ADLTC) Eligibility Manual §§ 526 (Qualifying Income Trusts), 528 (Processing Cases With Trusts), and 570 (Post Eligibility Treatment of Income (Cost-of-Care), incl. gross income counting and the ranked 6-item COC deduction order); federal authority 42 U.S.C. § 1396p(d)(4)(B)). This is the source for the required-provisions checklist — Alaska publishes no separate fill-in template.
Federal sources
- 42 U.S.C. § 1396p(d)(4)(B) — federal Medicaid statute authorizing QITs. https://www.law.cornell.edu/uscode/text/42/1396p
- CMS — 2026 SSI and Spousal Impoverishment Standards. https://www.medicaid.gov/federal-policy-guidance/downloads/cib12092025.pdf . Source for the 2026 Federal Benefit Rate and the 300% cap derivation used in the Alaska income-cap figure.
- SSA — 2026 SSI Federal Payment Amounts. https://www.ssa.gov/oact/cola/SSI.html . Verification of the 2026 FBR figure CMS uses to compute the 300% Medicaid long-term-care income cap.