Tennessee Qualified Income Trust Requirements Guide — Qualify a Family Member for Medicaid Before the Next Billing Cycle
For adult children, spouses, and the attorneys, paralegals, and care managers who help them — before another $9,429–$10,038 month of private-pay care goes by.
A Tennessee Qualified Income Trust (Miller Trust) is an irrevocable trust used to qualify a Medicaid applicant whose monthly income exceeds the Tennessee long-term-care income cap of $2,982 per month (effective May 1, 2026 (TennCare ABD Trusts Policy 110.055 revision)). Tennessee does not publish a fill-in QIT form — the trust must be drafted (by an attorney, or by you where permitted) to meet TennCare's published requirements (ABD Trusts Policy 110.055 §4.h). Medicaid eligibility begins the month the trust is signed and funded — there is no retroactive effect, and every month of delay is another month of full private-pay care ($9,429–$10,038/mo in Tennessee). This guide is the requirements checklist and operational walkthrough most families need: $97, instant download, money-back if TennCare rejects the trust for a reason traceable to following the guide.
Tennessee doesn't publish a fill-in Qualified Income Trust form, so an attorney drafts it — this is the playbook that keeps that engagement to drafting alone instead of research-plus-drafting: the exact requirements checklist, cited to TennCare's own published policy, plus the funding and bank-account mechanics once the trust is signed. Informational only — not legal advice. Every requirement is drawn straight from TennCare's own published policy, with the citation behind each claim.
From the author
I built this after spending weeks helping a family member set up a Miller Trust. Two attorneys quoted $1,500 and $2,200 with a six-week wait — most of that billed for research we could have handed them ourselves; and the bank refused to open the account twice after the trust was signed. That second refusal is the one that got to me — the trust was already signed, already correct, and we were still stuck over a bank's own unfamiliarity with it. The gap between "an attorney drafted something" and a funded account that actually starts Medicaid coverage is where families lose a month they can't get back — and closing that gap is the whole reason this guide exists.
James Whitfield Researcher, not an attorney
- Built on TennCare's own .gov template
- Every claim cited to TennCare policy
- Secure checkout by Stripe
- Money-back if the trust is rejected
What buyers say
A review from a different state — because it's real, and we'd rather show a genuine reader than fill this page with something invented. Retired attorney & CPA is exactly the kind of reader who'd catch it if this guide were sloppy, which is why we lead with it. We only publish verified customers who gave permission — no invented reviews, no stock quotes.
Your Setup Kit turned out to be extremely useful. It got us to the New Jersey QIT template right away, and that was big. We used the Kit to work through the template and the practical questions about how a QIT actually works, and we were able to draft it, get it executed, open a bank account, and submit it with the application in just two or three days. It was an essential need for us, and the Kit helped us accomplish it very quickly.
Not the only one deciding? Send them this page before you dive in.
$9,429–$10,038 a month, Tennessee private-pay care
Why this can't wait: until the trust is set up correctly, an over-income applicant can't be approved for Medicaid — so the private-pay bill keeps landing on your family, and your family member's place in care can depend on it. Coverage begins the calendar month the QIT is signed and funded — there is no back-dating — and Tennessee private-pay care runs $9,429–$10,038 a month, so every 30 days of delay is a five-figure check out of pocket.
The 2026 Tennessee income cap
- Income cap, single applicant
- $2,982/mo
- Personal needs allowance
- $70/mo
- Tennessee private-pay care
- $9,429–10,038/mo
Setting up a Miller Trust in Tennessee starts with one number — the income cap. The Tennessee 2026 Medicaid long-term-care income limit is $2,982/month for a single applicant. If your family member's countable monthly income exceeds this limit, a properly drafted, signed, and funded QIT diverts the excess and brings countable income below the cap. The applicant's Personal Needs Allowance in Tennessee is $70/month. Source: TennCare ABD Trusts Policy 110.055 §4.h [1].
What's in the Tennessee guide
10 operational sections and 3 reference appendices. Here are the six pieces buyers tell other buyers made the difference:
“If I'm hiring a lawyer anyway, why do I need this?”
Because Tennessee doesn't publish a fill-in form, the attorney has to draft the trust either way — the question is whether they research TennCare's requirements on your bill, or you hand them the requirements up front. This guide is the research: the 8-item checklist, the funding rule, the bank-refusal script, and the 6 TennCare denial traps with the citation behind each — everything that turns a research-and-draft engagement into drafting alone.
If your spouse is the one entering care: this guide covers the Qualified Income Trust — the income side of qualifying — in full. If you're the spouse staying at home (the "community spouse"), the guide also walks you through the trust itself, and Section 9 orients you on the separate resource-allowance rules that protect your home and savings. Those resource rules are fact-specific, so for them you'll likely still want a Tennessee elder-law attorney — but the guide's job is to make that a short, cheaper meeting instead of a $1,000–$2,500 one: you walk in with the trust already set up, the resource questions already identified, and the documents already gathered, so you're paying for answers, not for someone to explain the basics to you.
How it works in Tennessee
- Confirm income is over the $2,982 cap Gross monthly income, from every source.
- Have the trust drafted to TennCare's requirements Tennessee doesn't publish a fill-in form.
- Name a trustee and open the trust account A dedicated bank account titled to the trust.
- Fund it in the same calendar month Eligibility starts that month, never earlier.
Full step-by-step walkthrough →
The funding-month rule
- September Trust not funded Private pay: $9,429–$10,038 for the month.
- October Sign, open, deposit Trust signed, account opened and income deposited, all this month. Eligible from October.
- November onward Deposit every month The income goes into the trust account every month to keep eligibility.
There is no back-dating. Funding in October can't cover September.
What it actually looks like
Sample pages from the guide
Real pages from the Tennessee guide PDF. Click any page to enlarge.
-
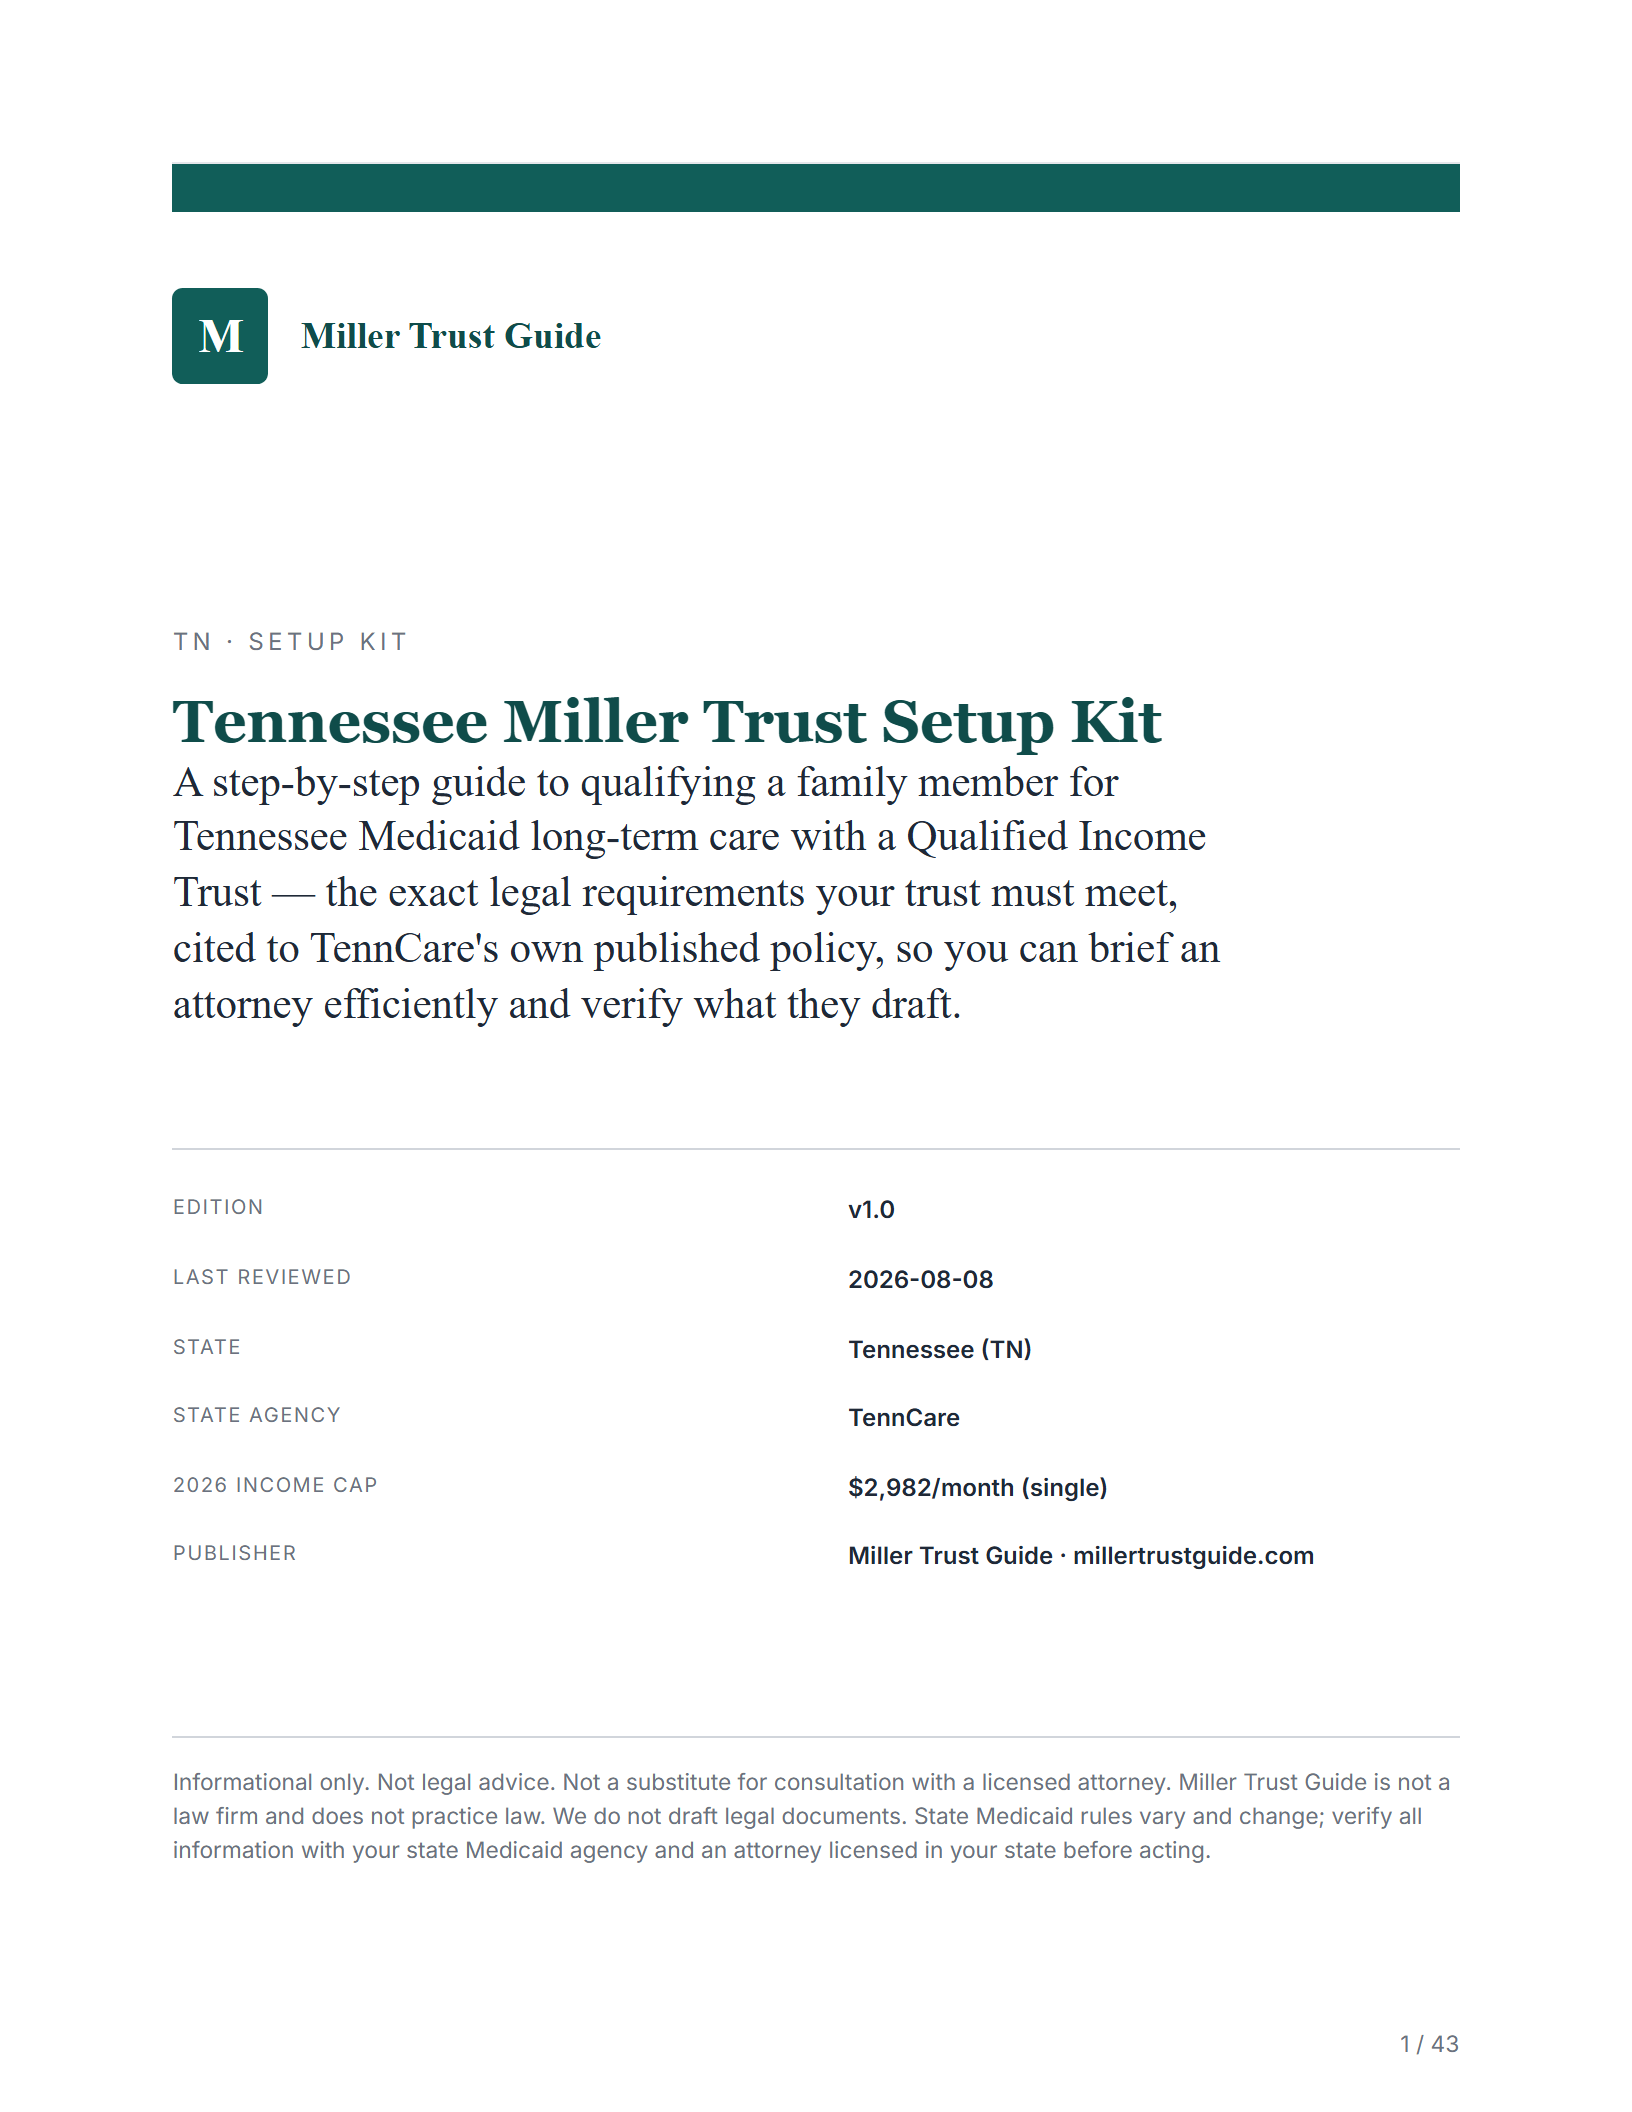
Cover & key facts
Version, last-reviewed date, the 2026 income cap, and the disclaimer — all on page 1.
View page -
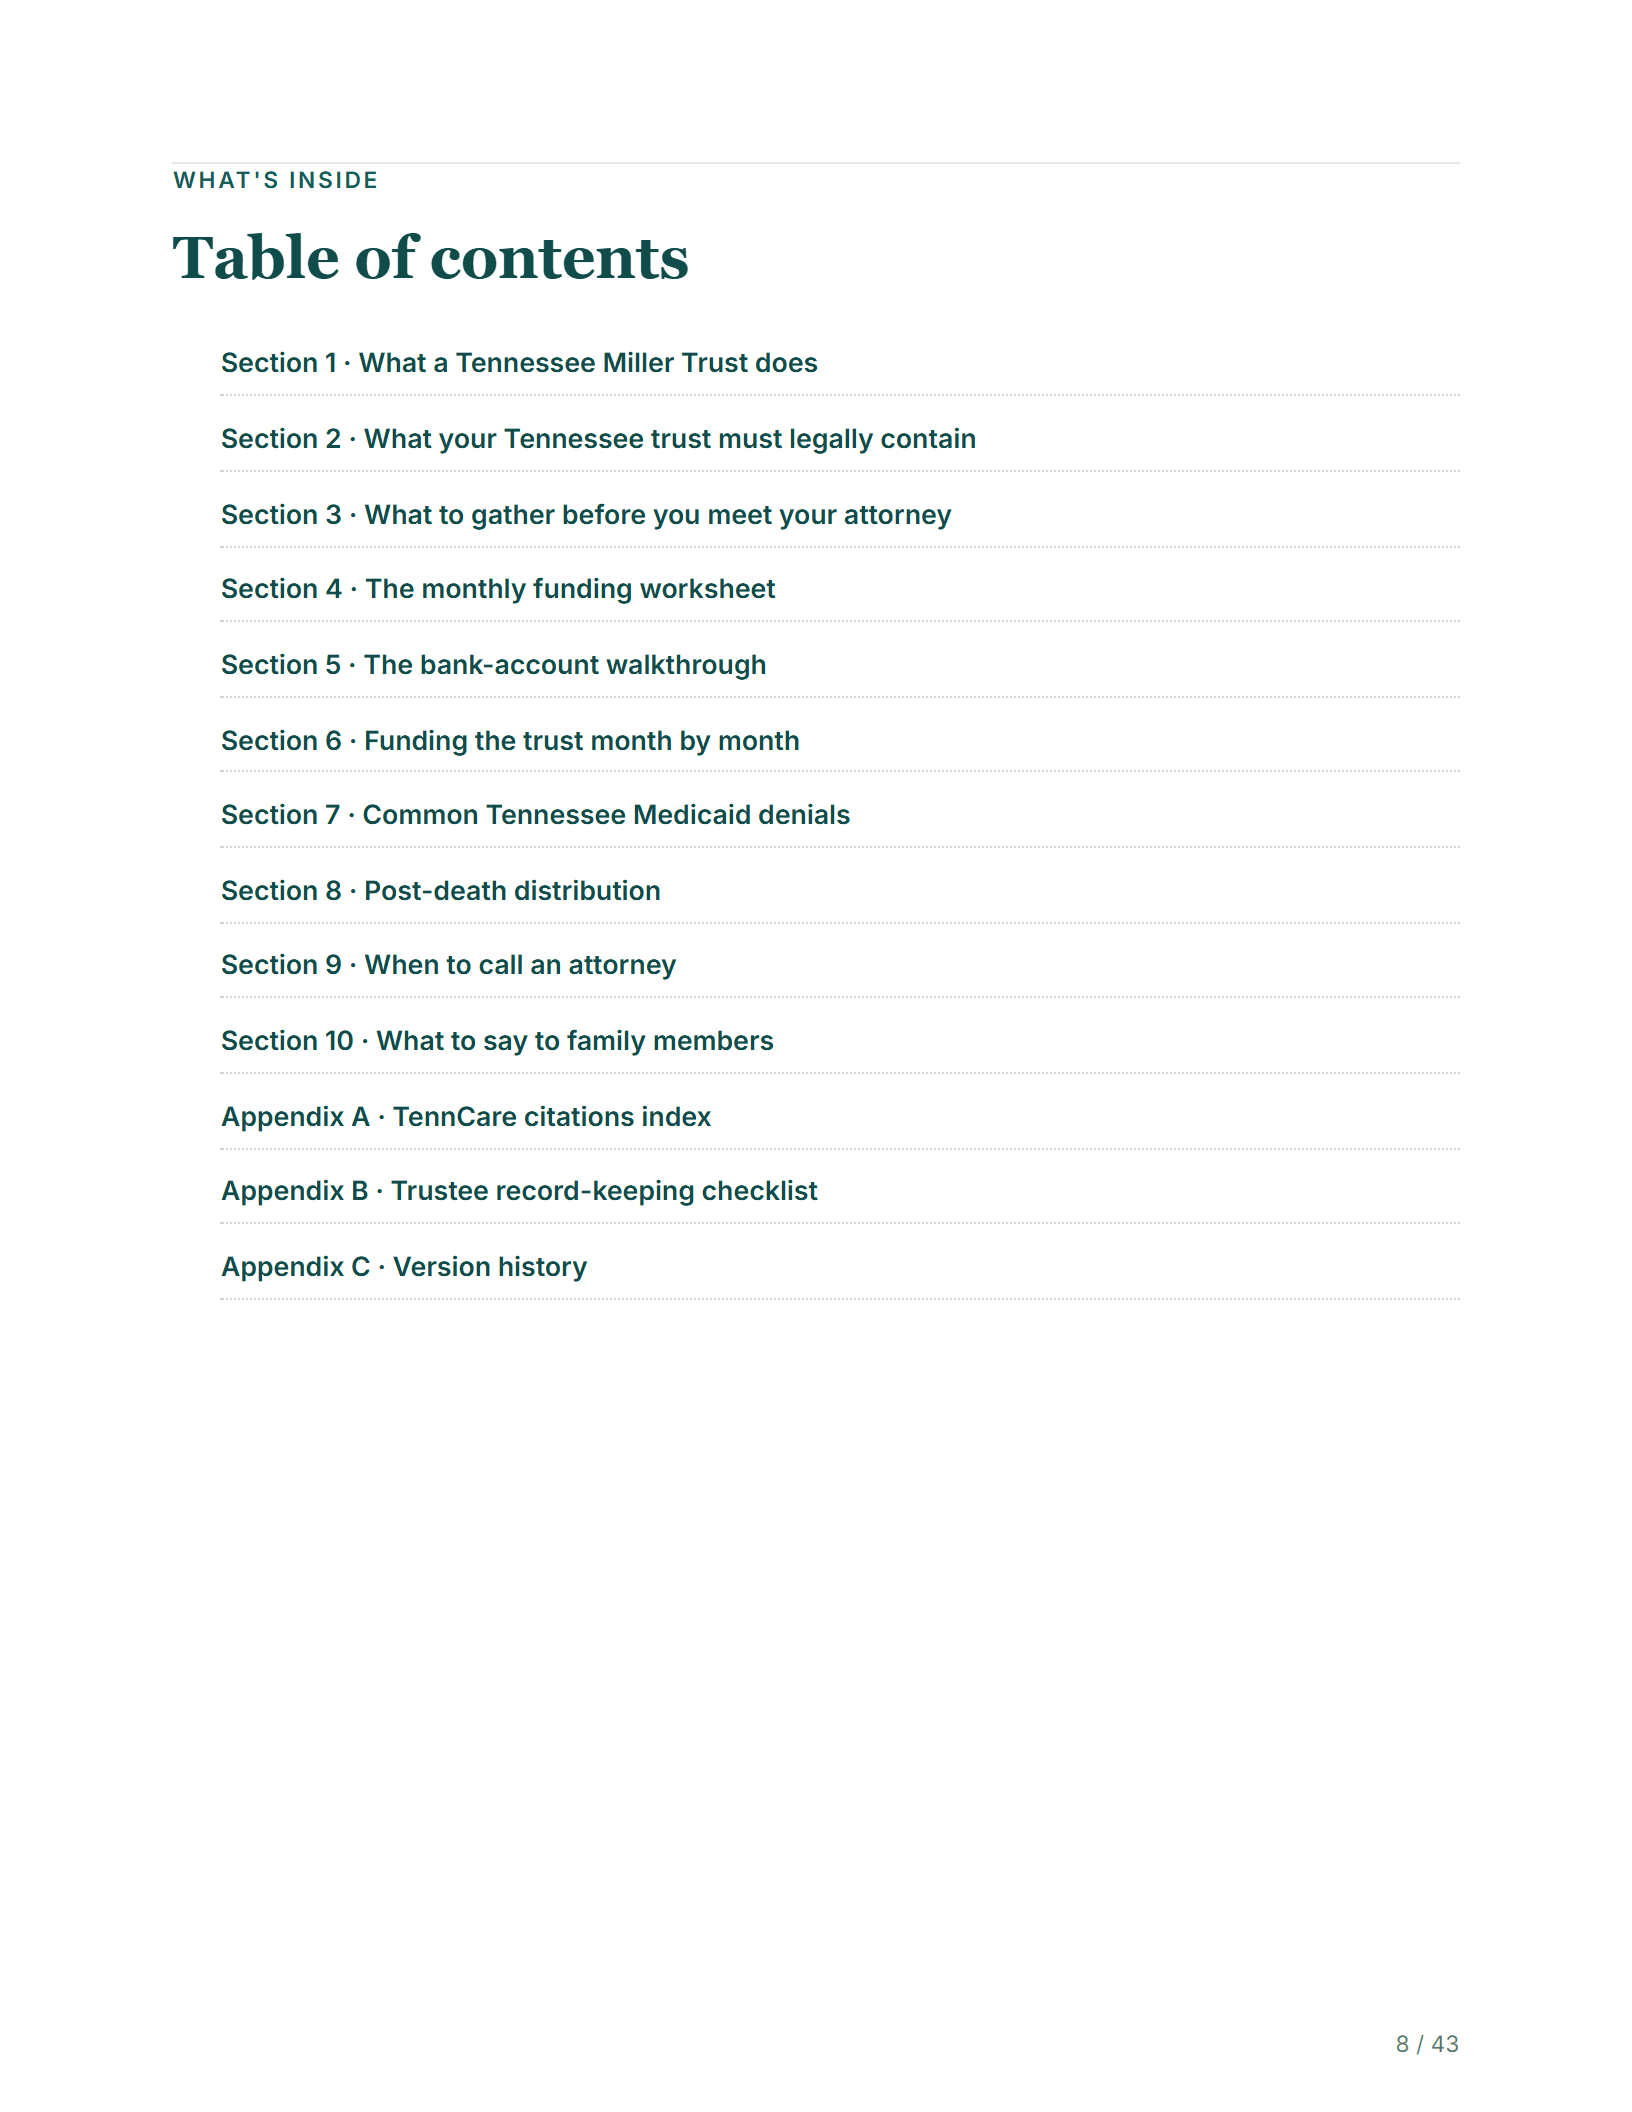
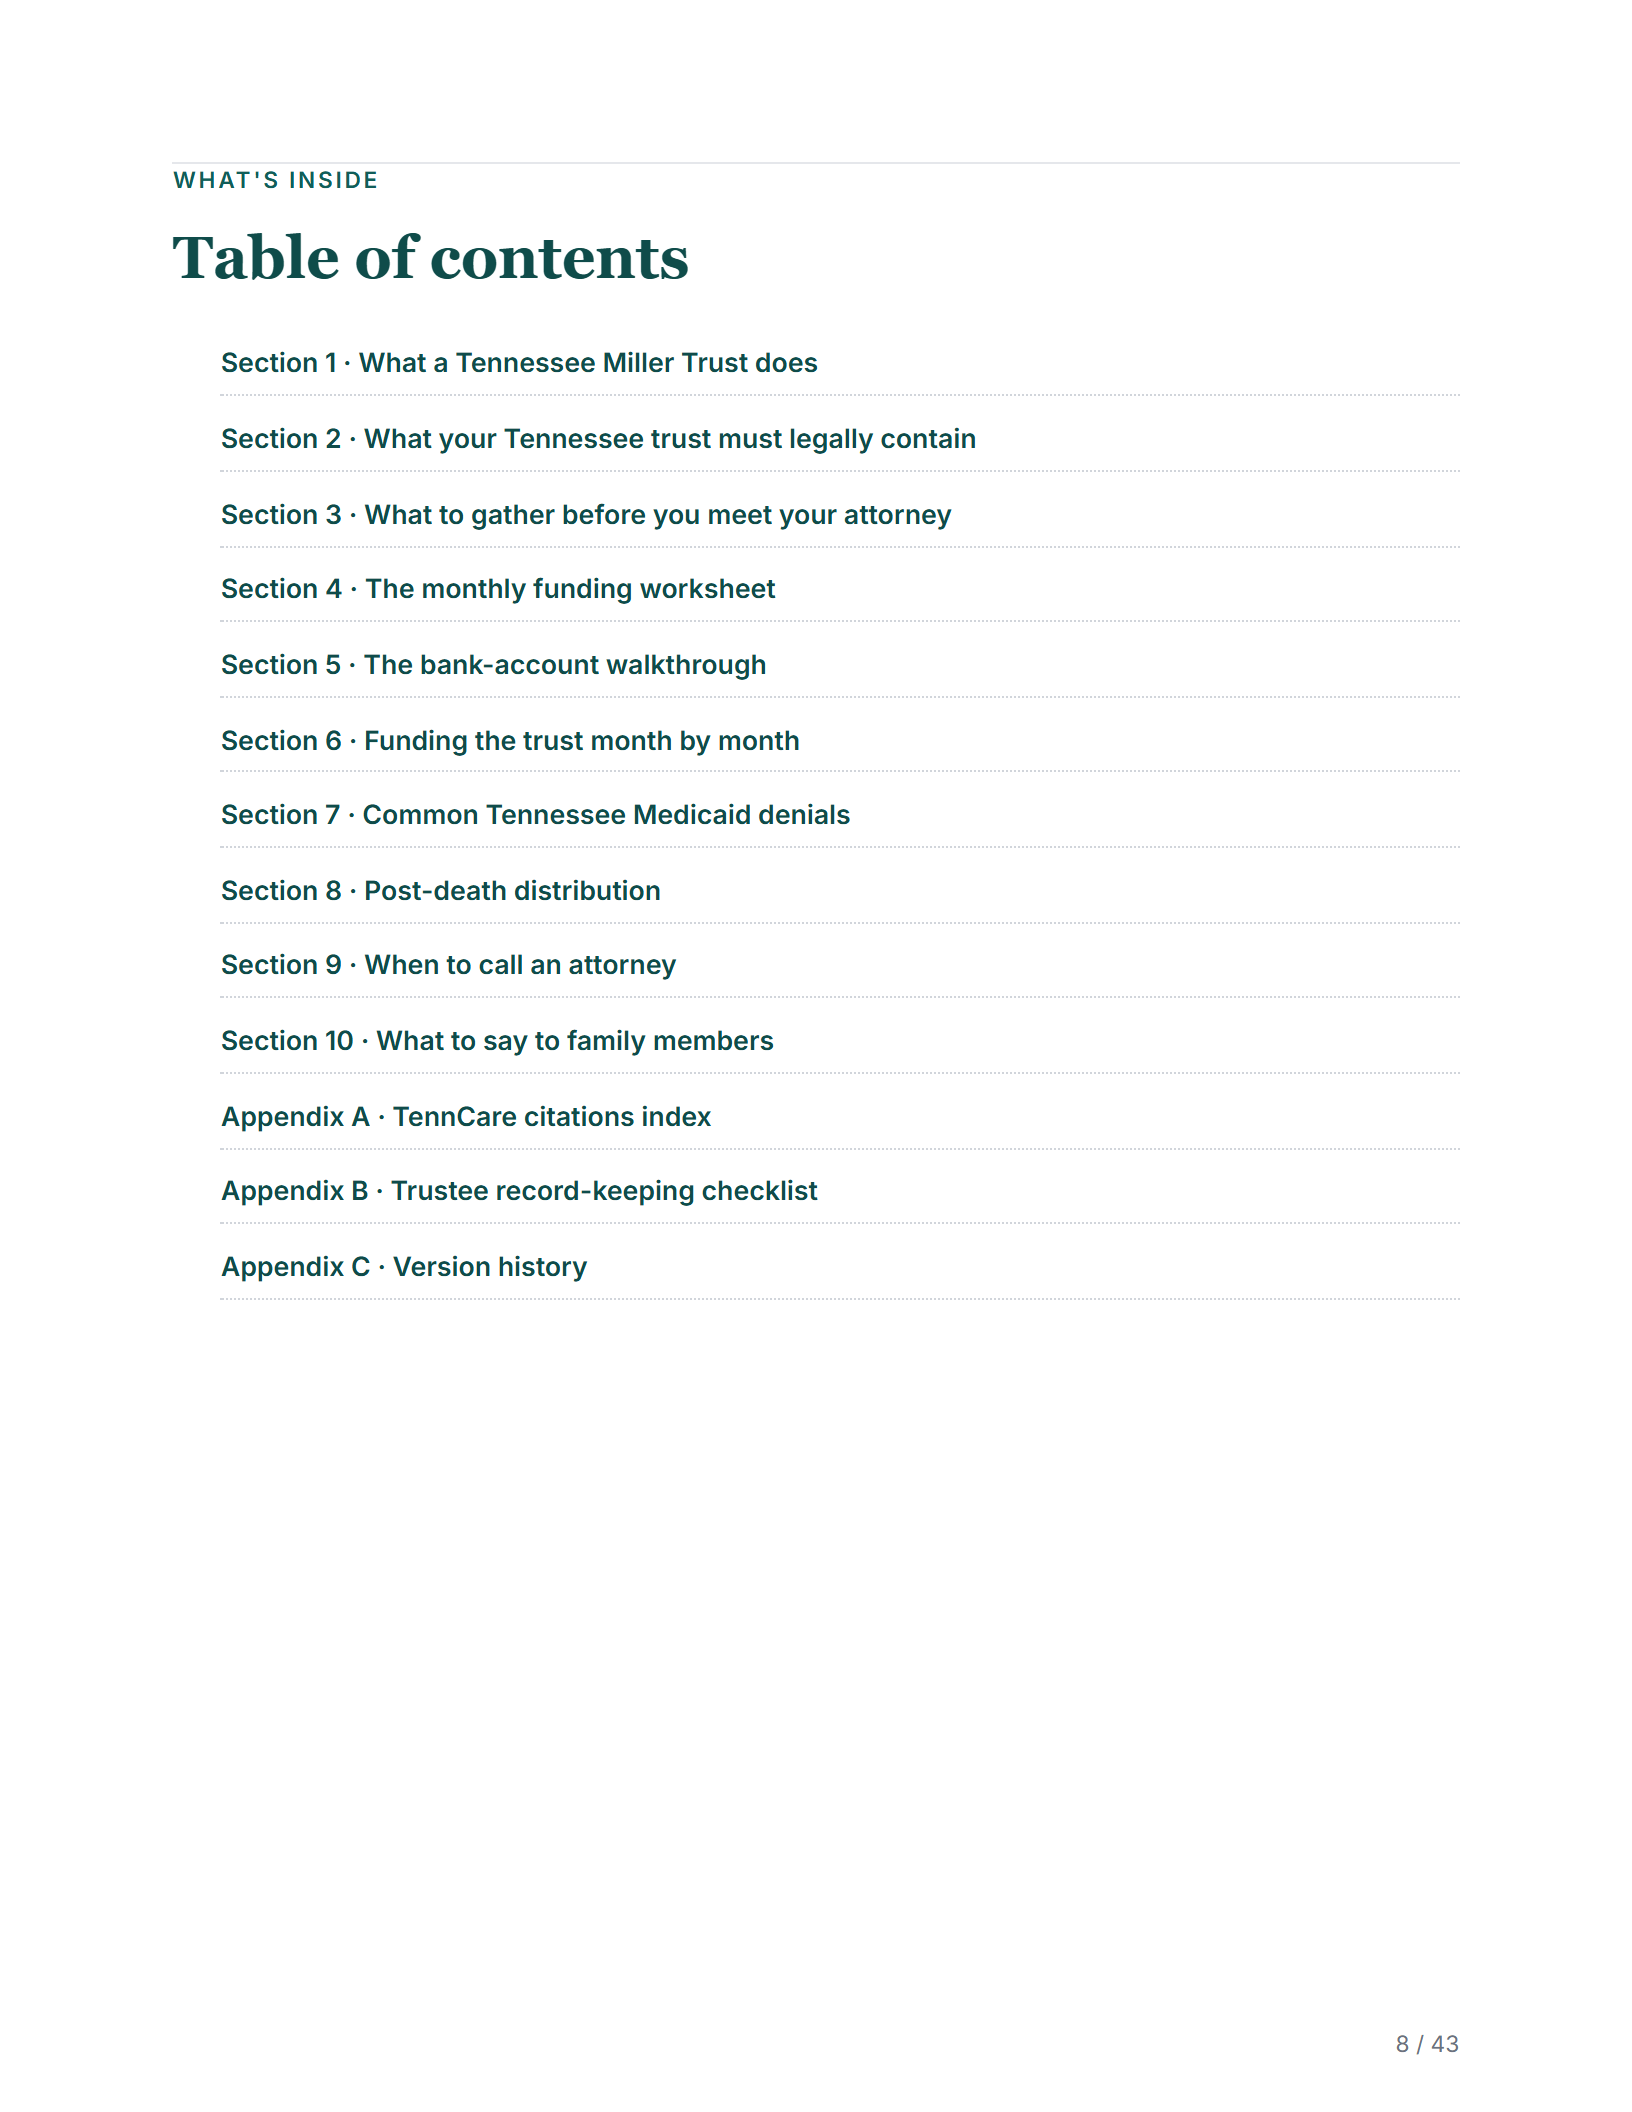
Table of contents
Ten operational sections plus three reference appendices. Every section in the order you'll use it.
View page -
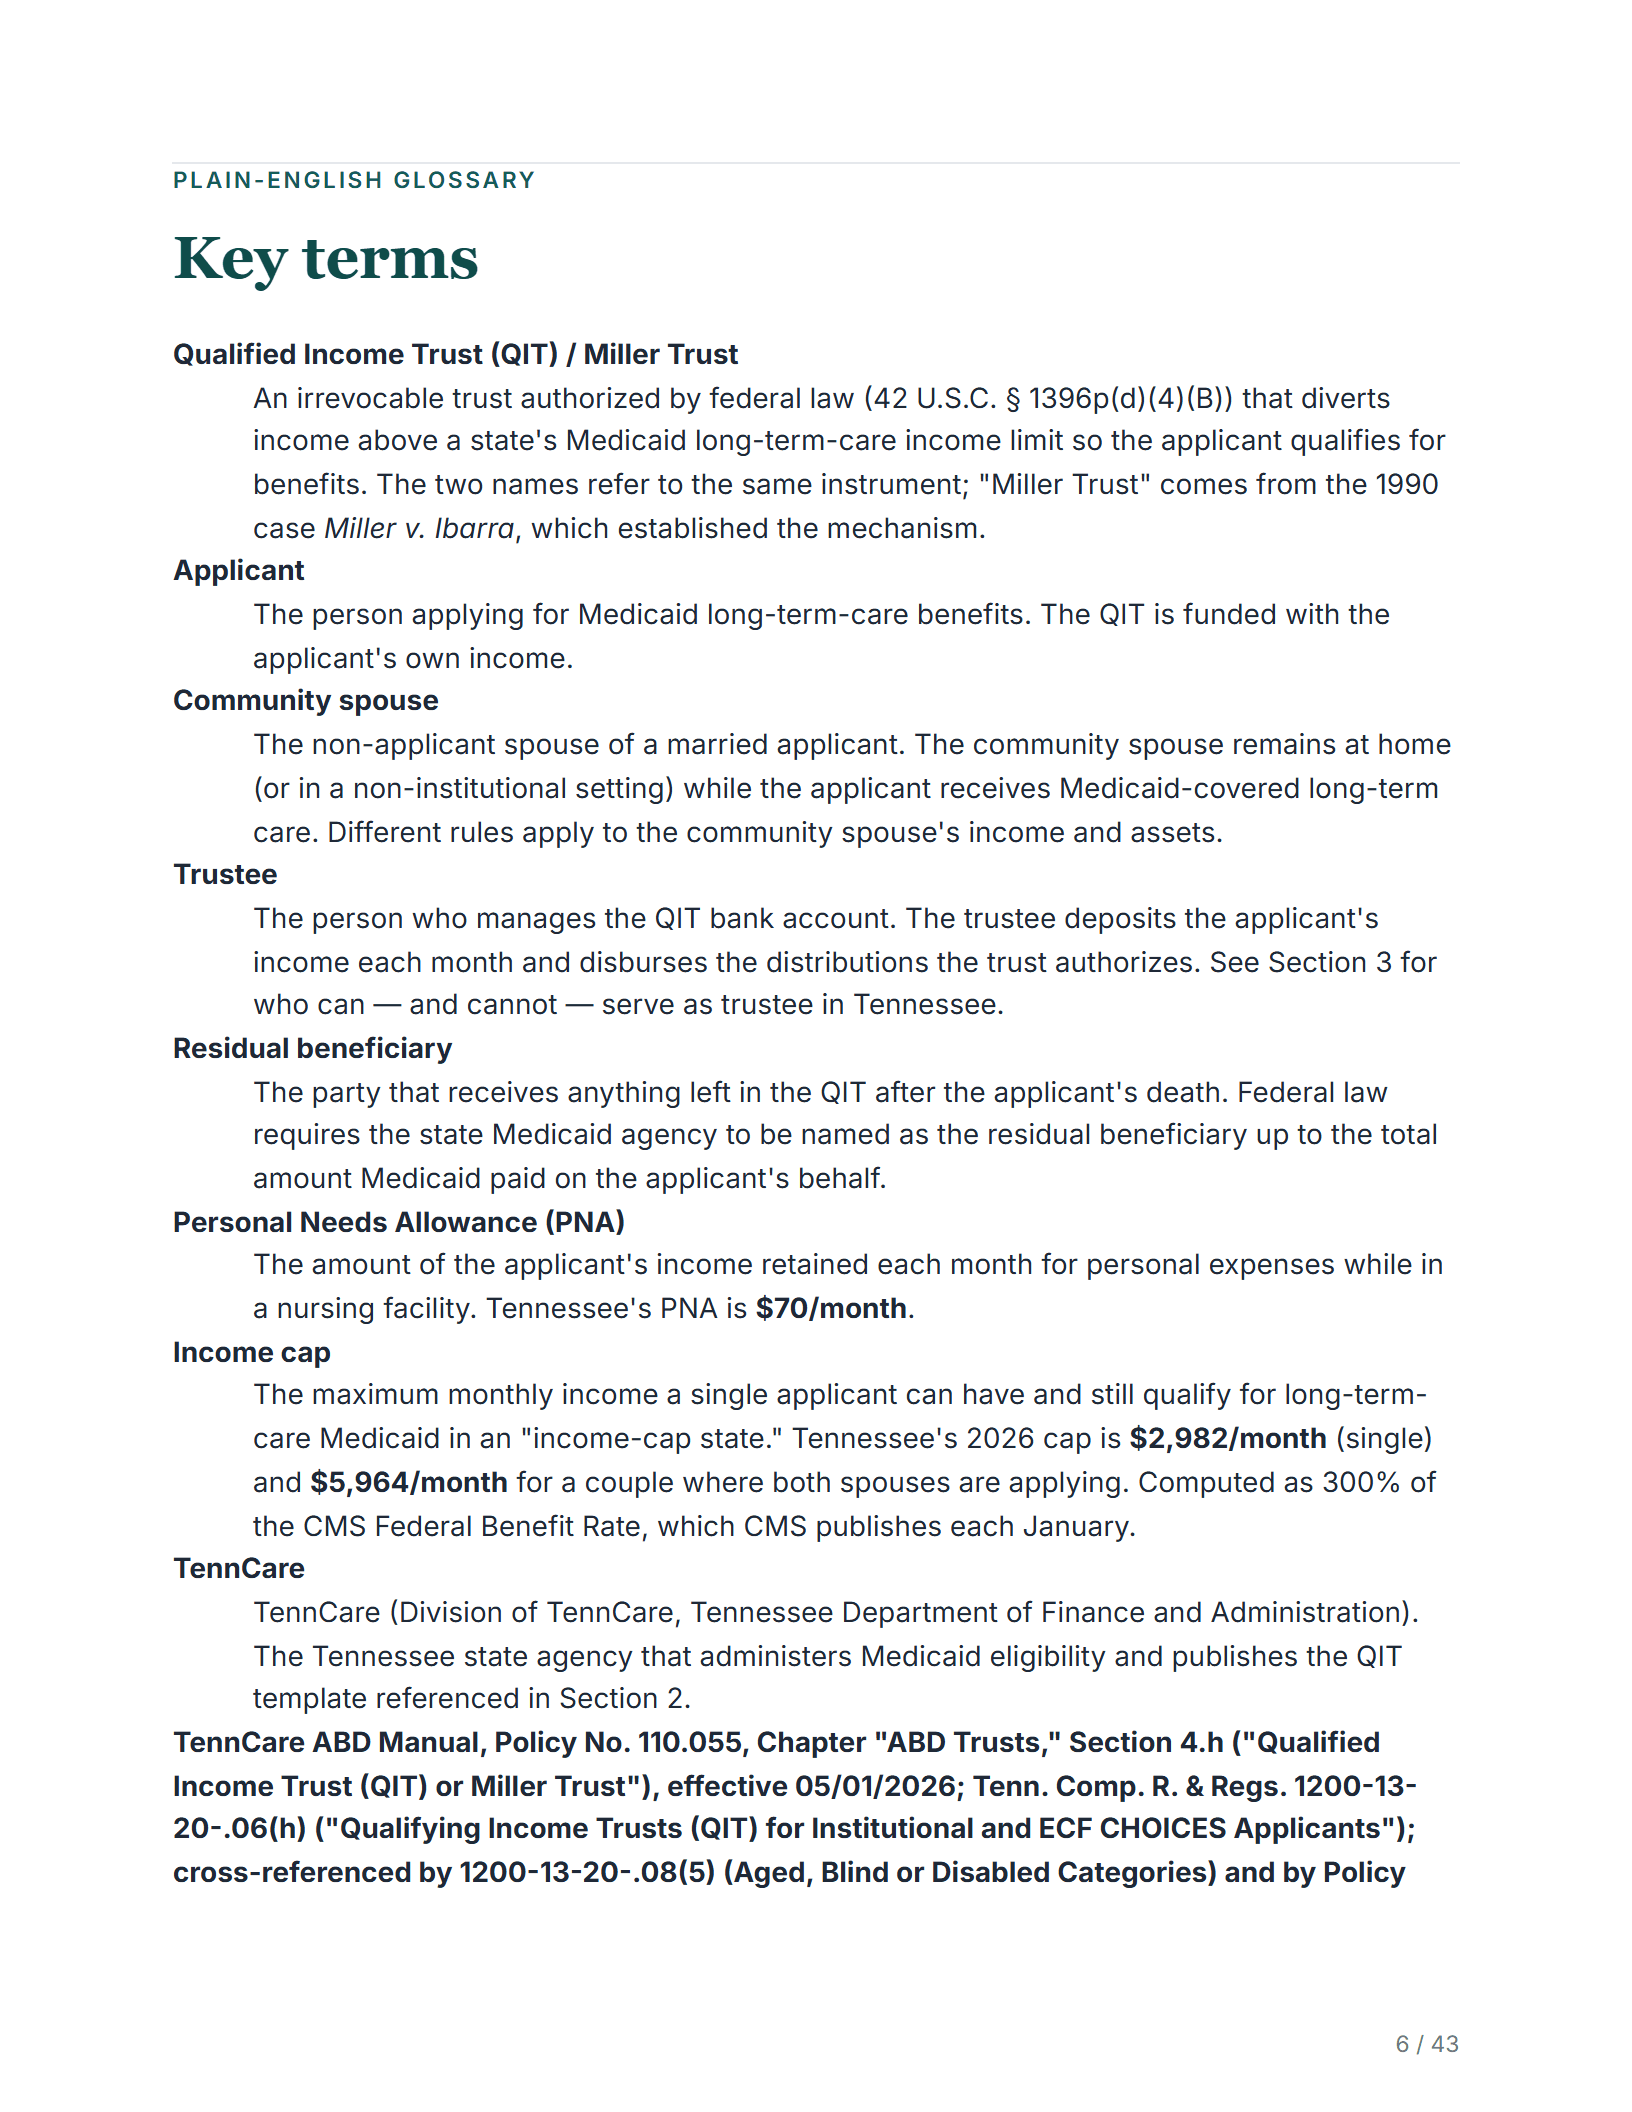
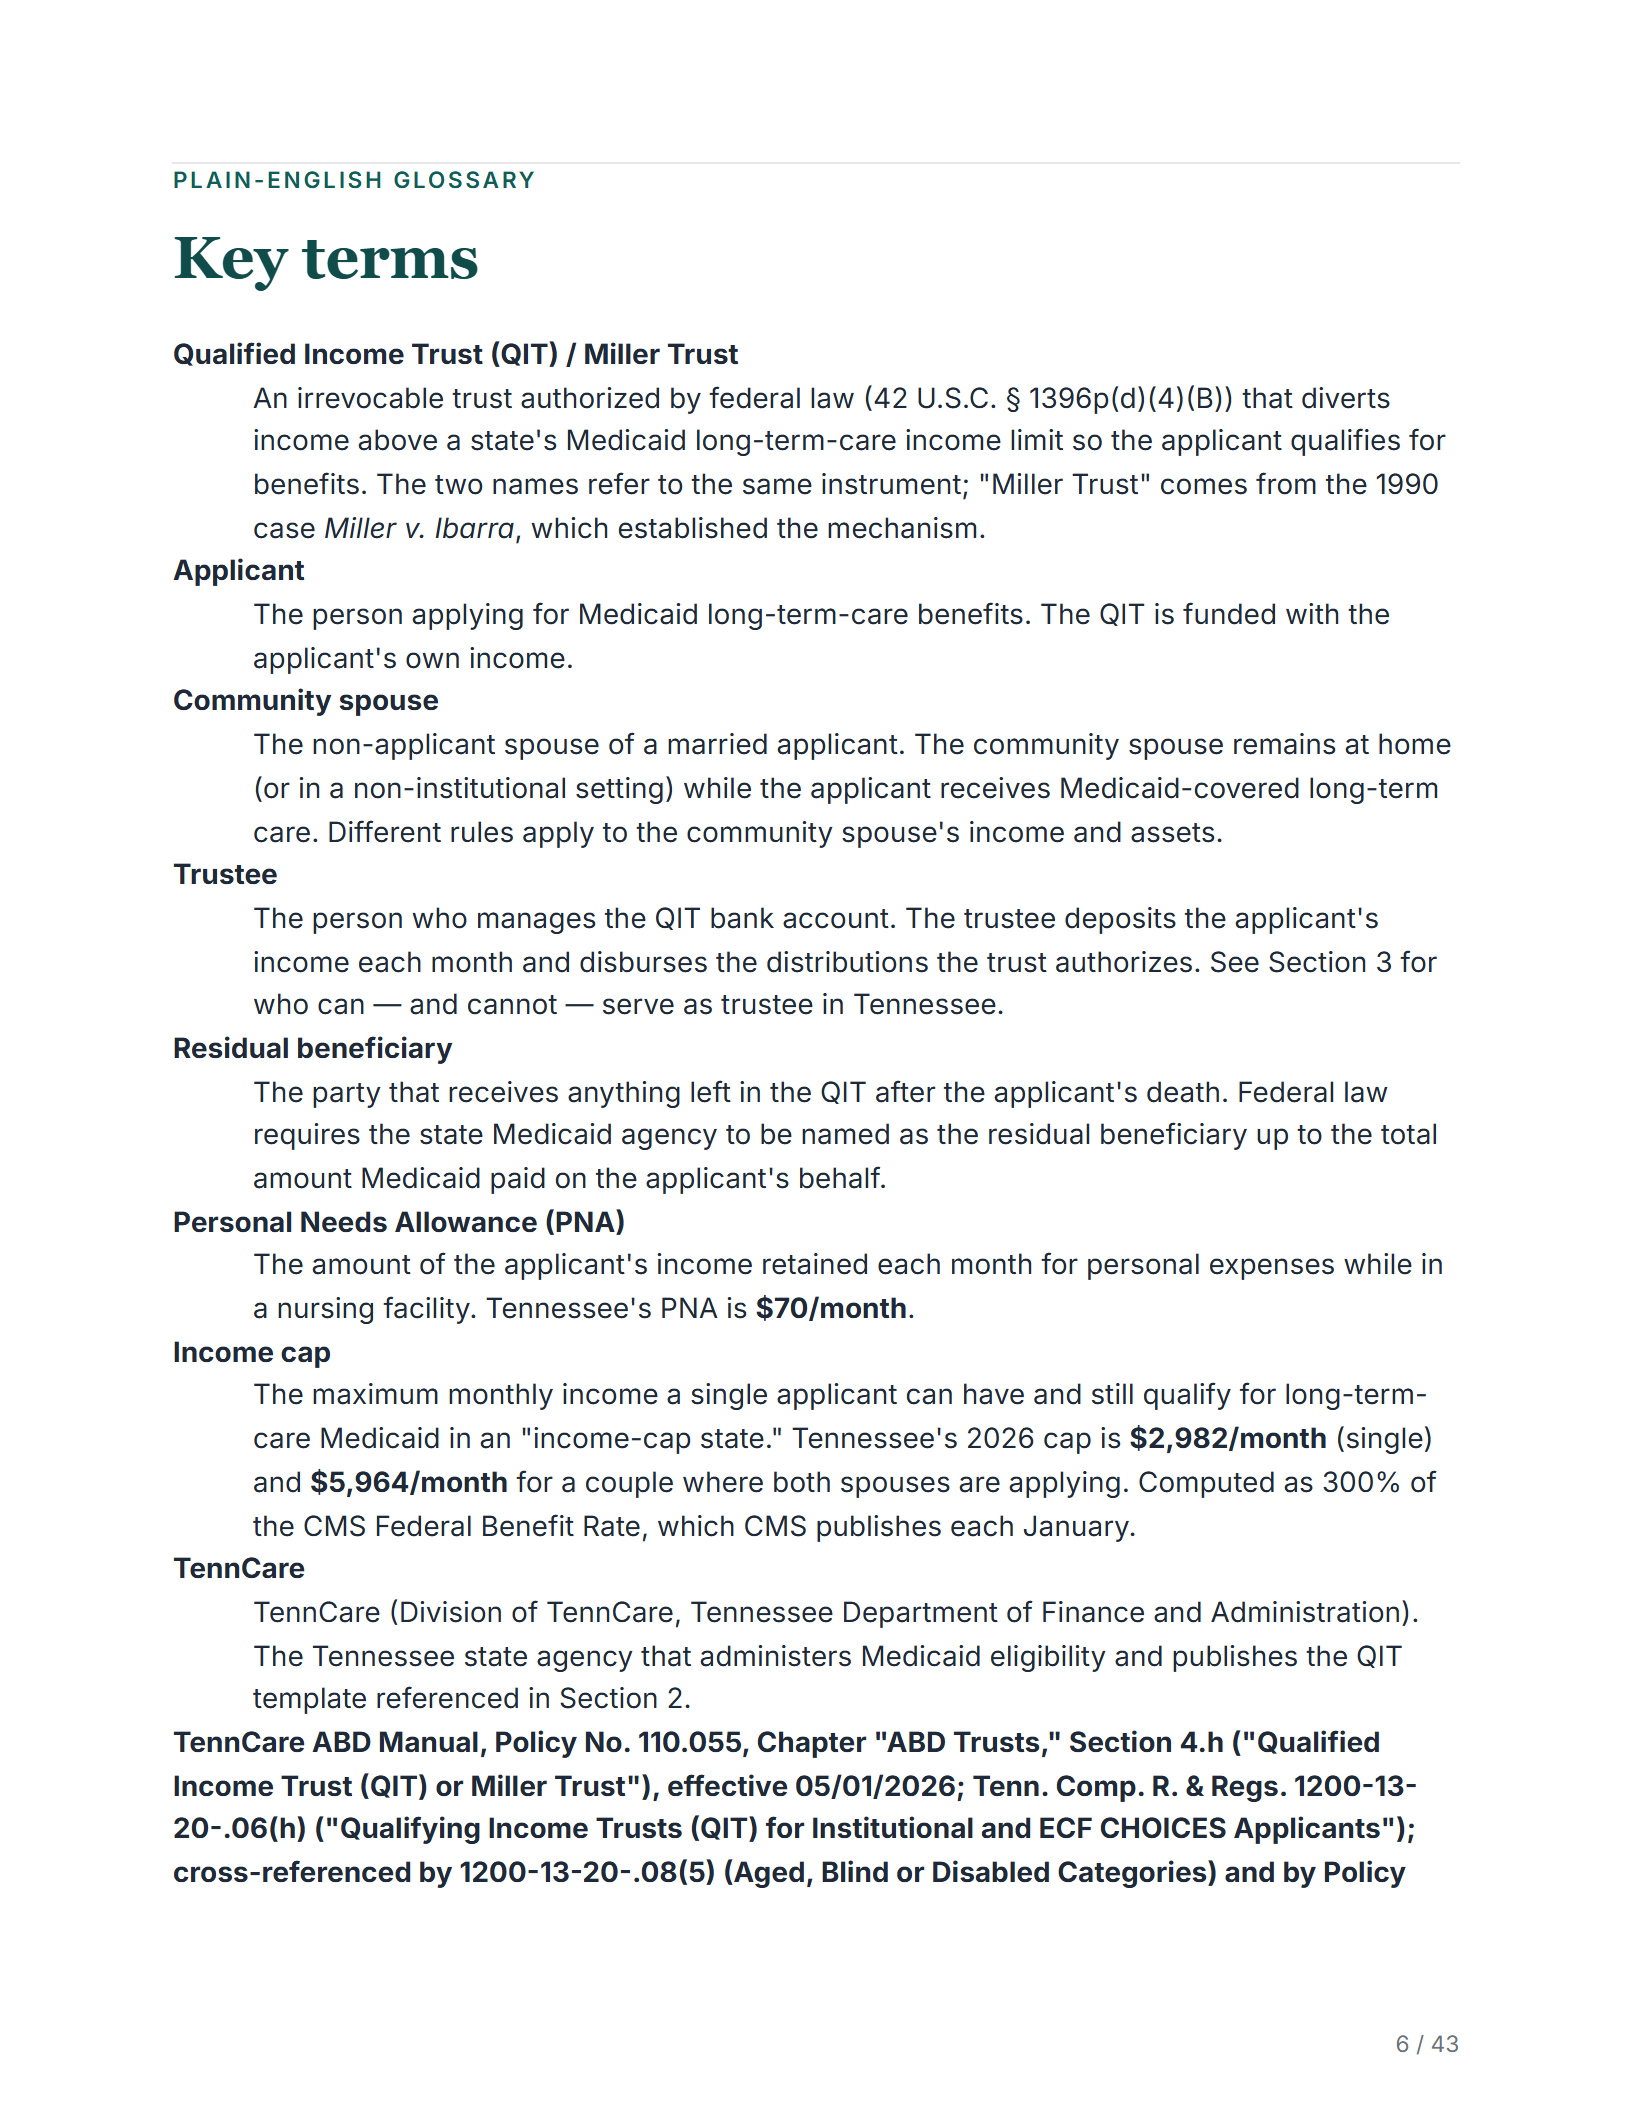
Plain-English glossary
Eleven key terms translated for a non-attorney reader. The vocabulary the rest of the kit assumes.
View page -
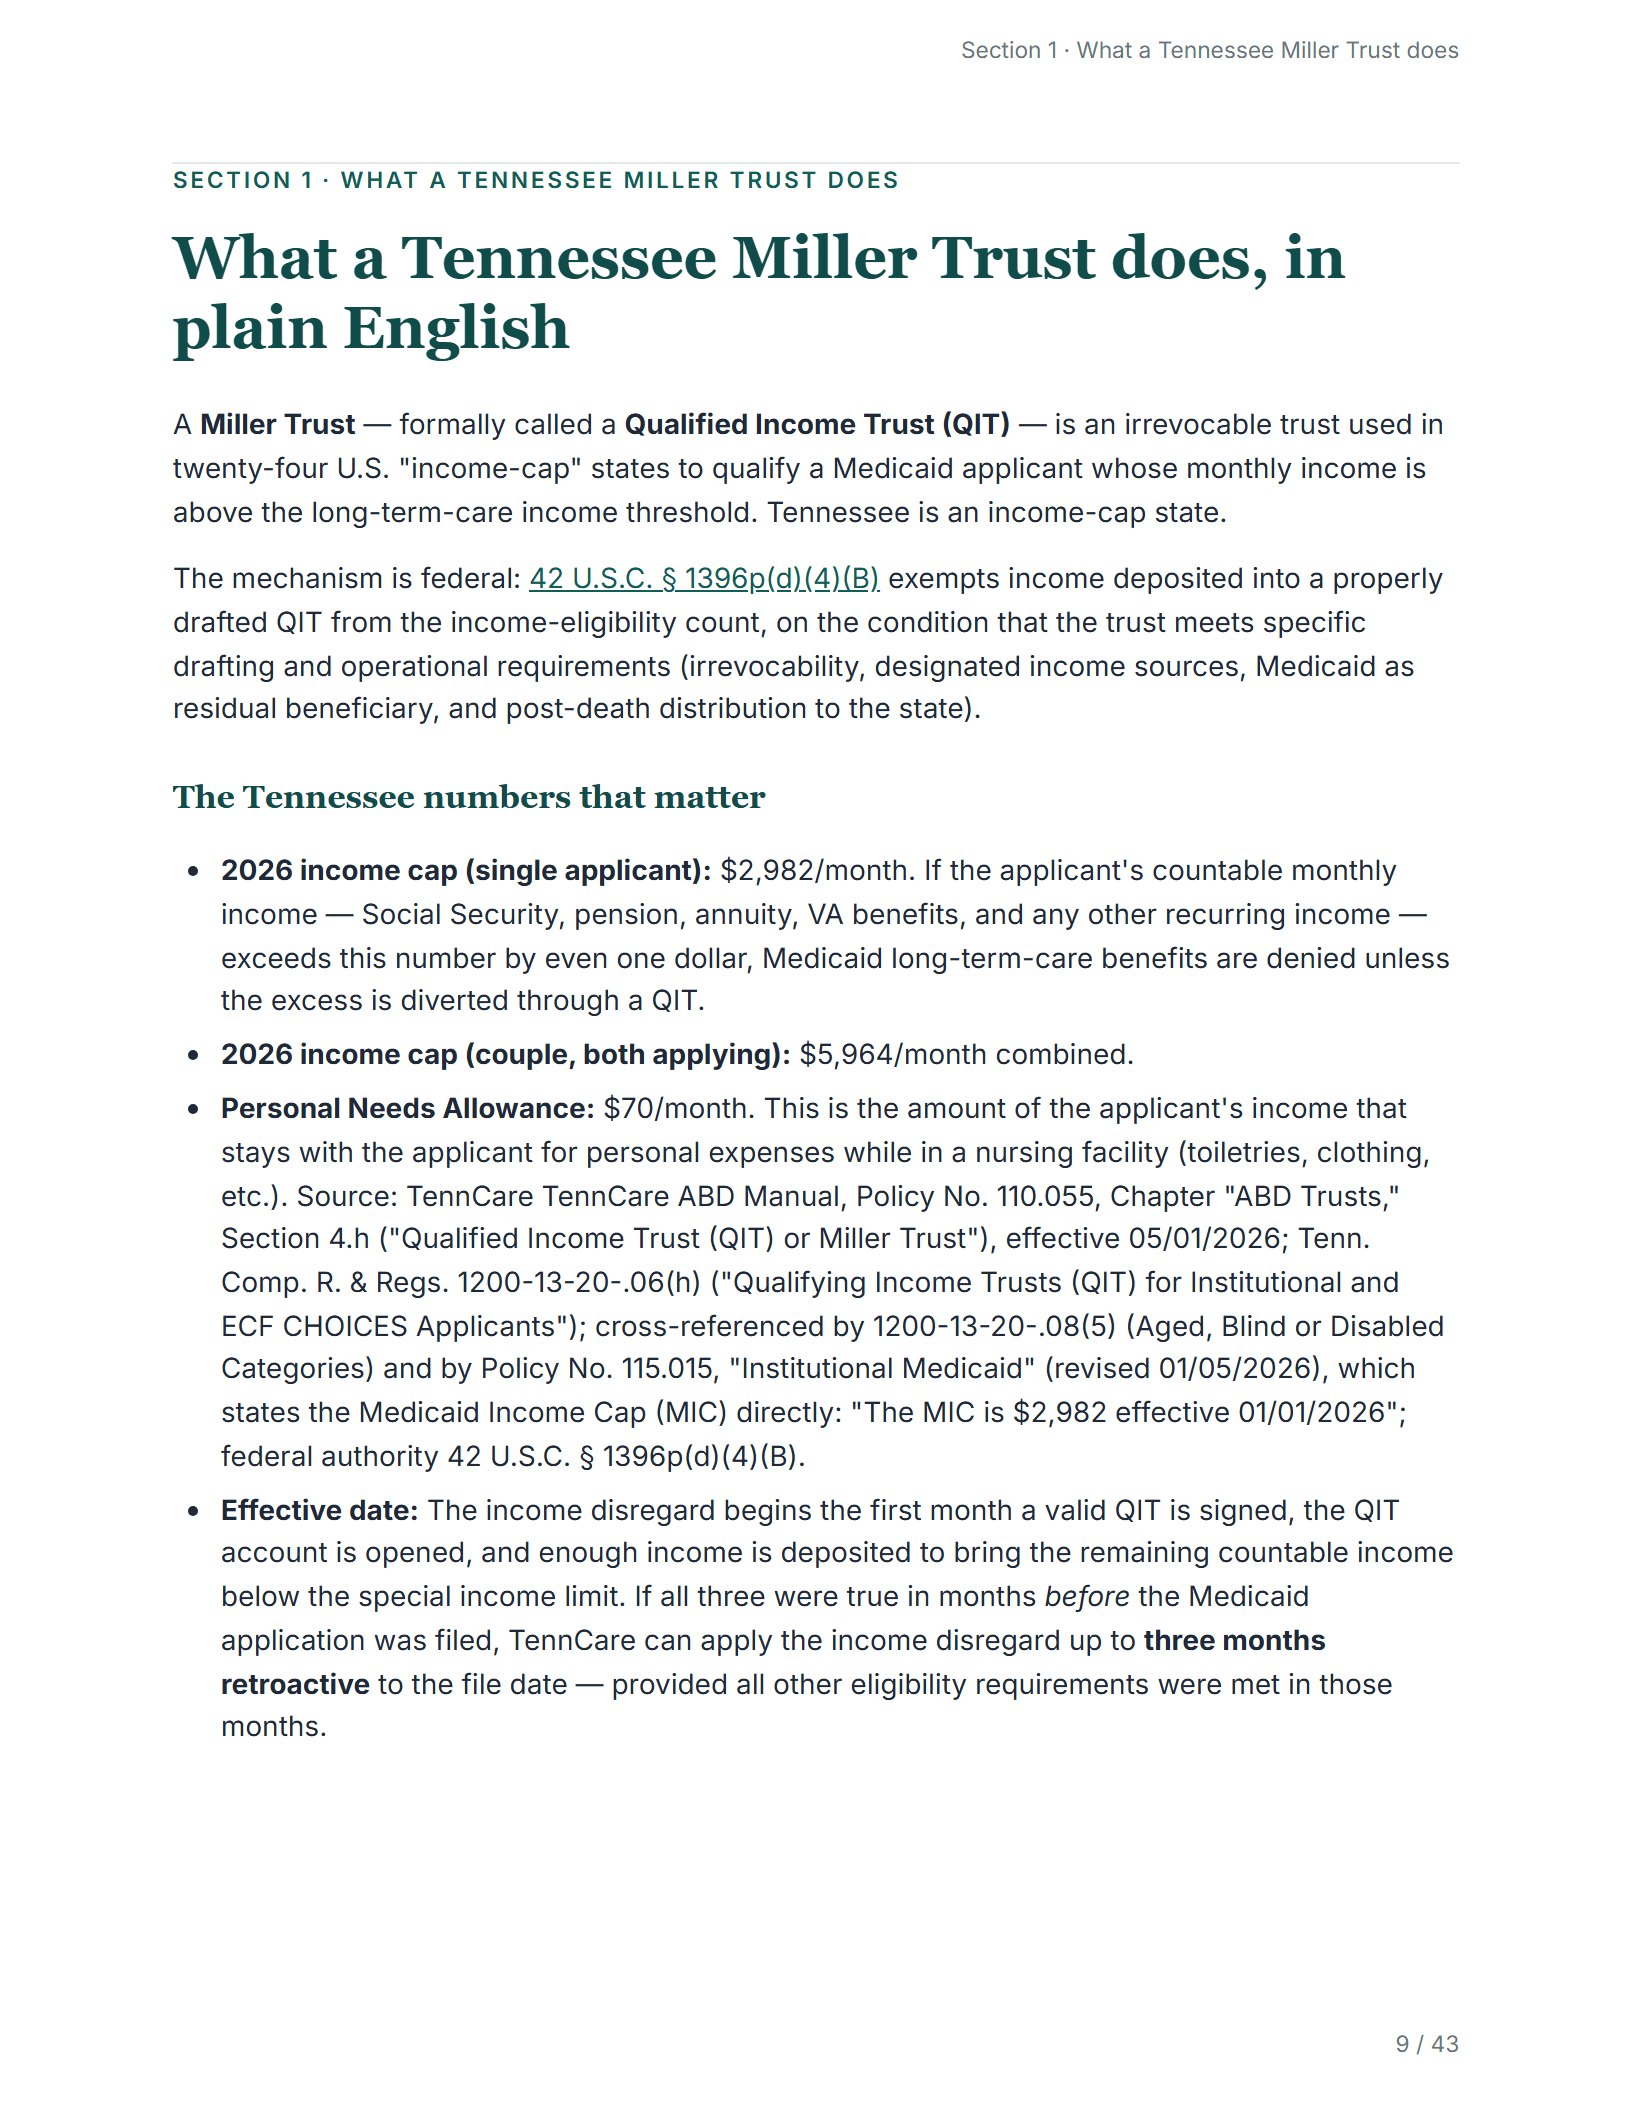
What it does, in plain English
The mechanism explained in plain language, cited to the federal statute, with your state's exact income cap and Personal Needs Allowance built in.
View page -
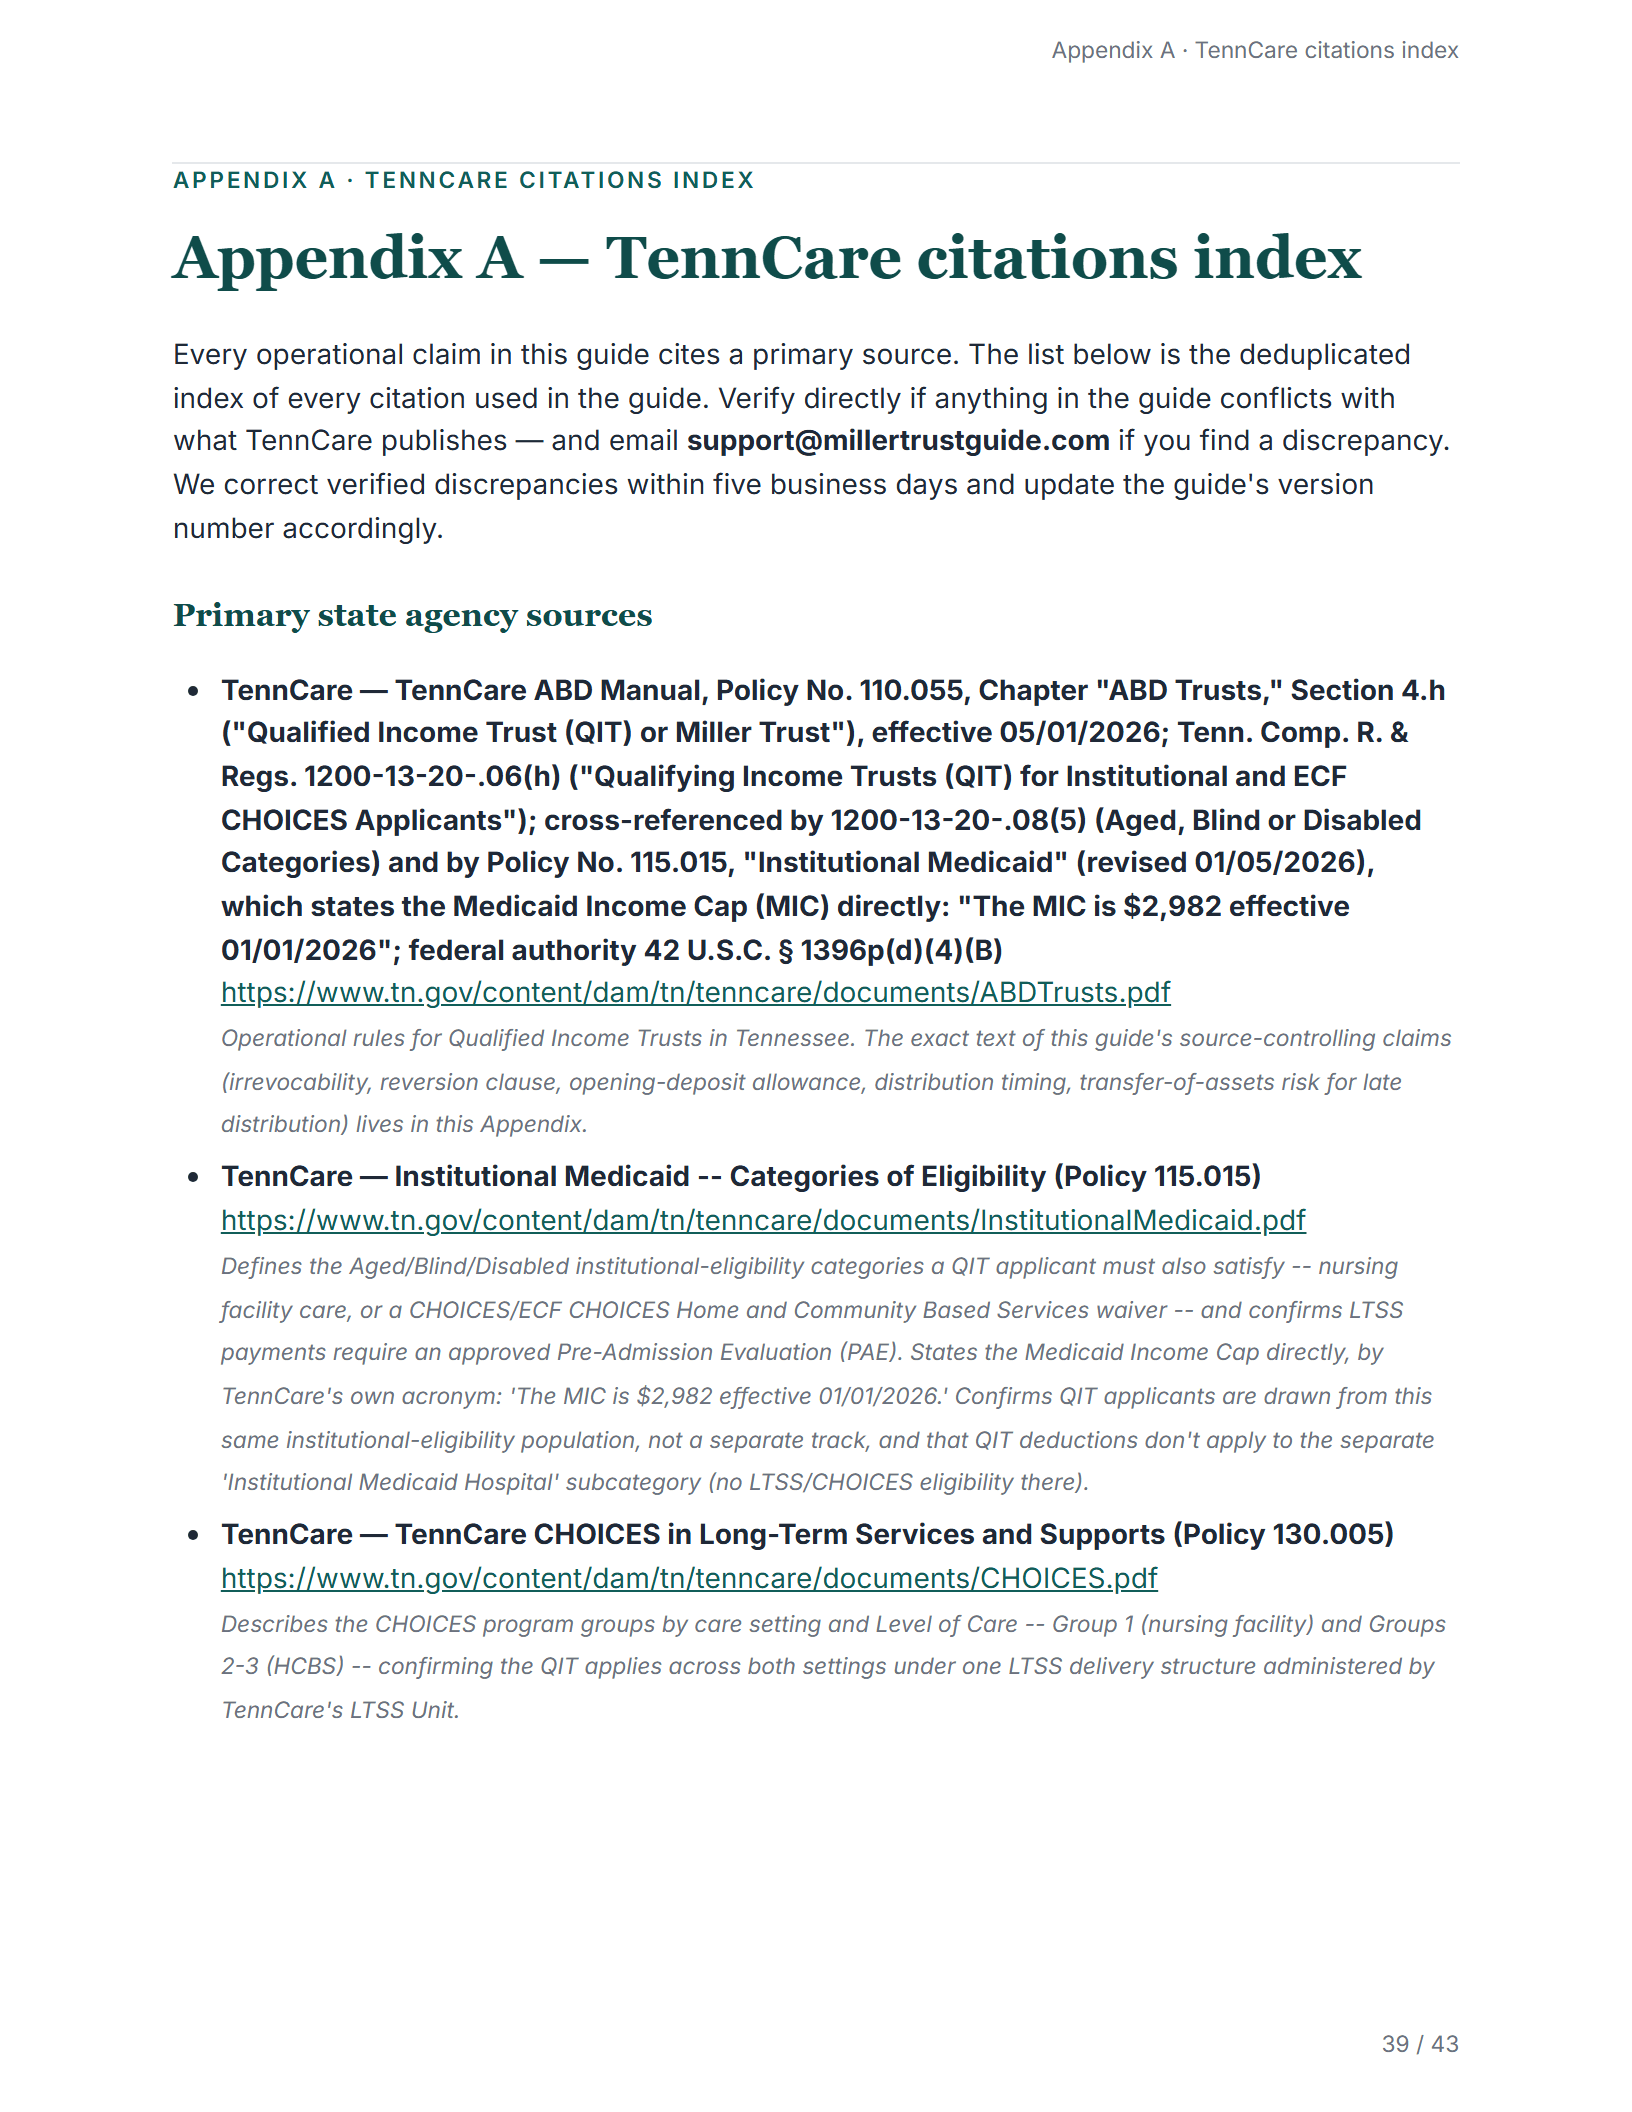
Citations index
Every operational claim sourced to a primary state-agency, CMS, SSA, or federal-statute citation.
View page
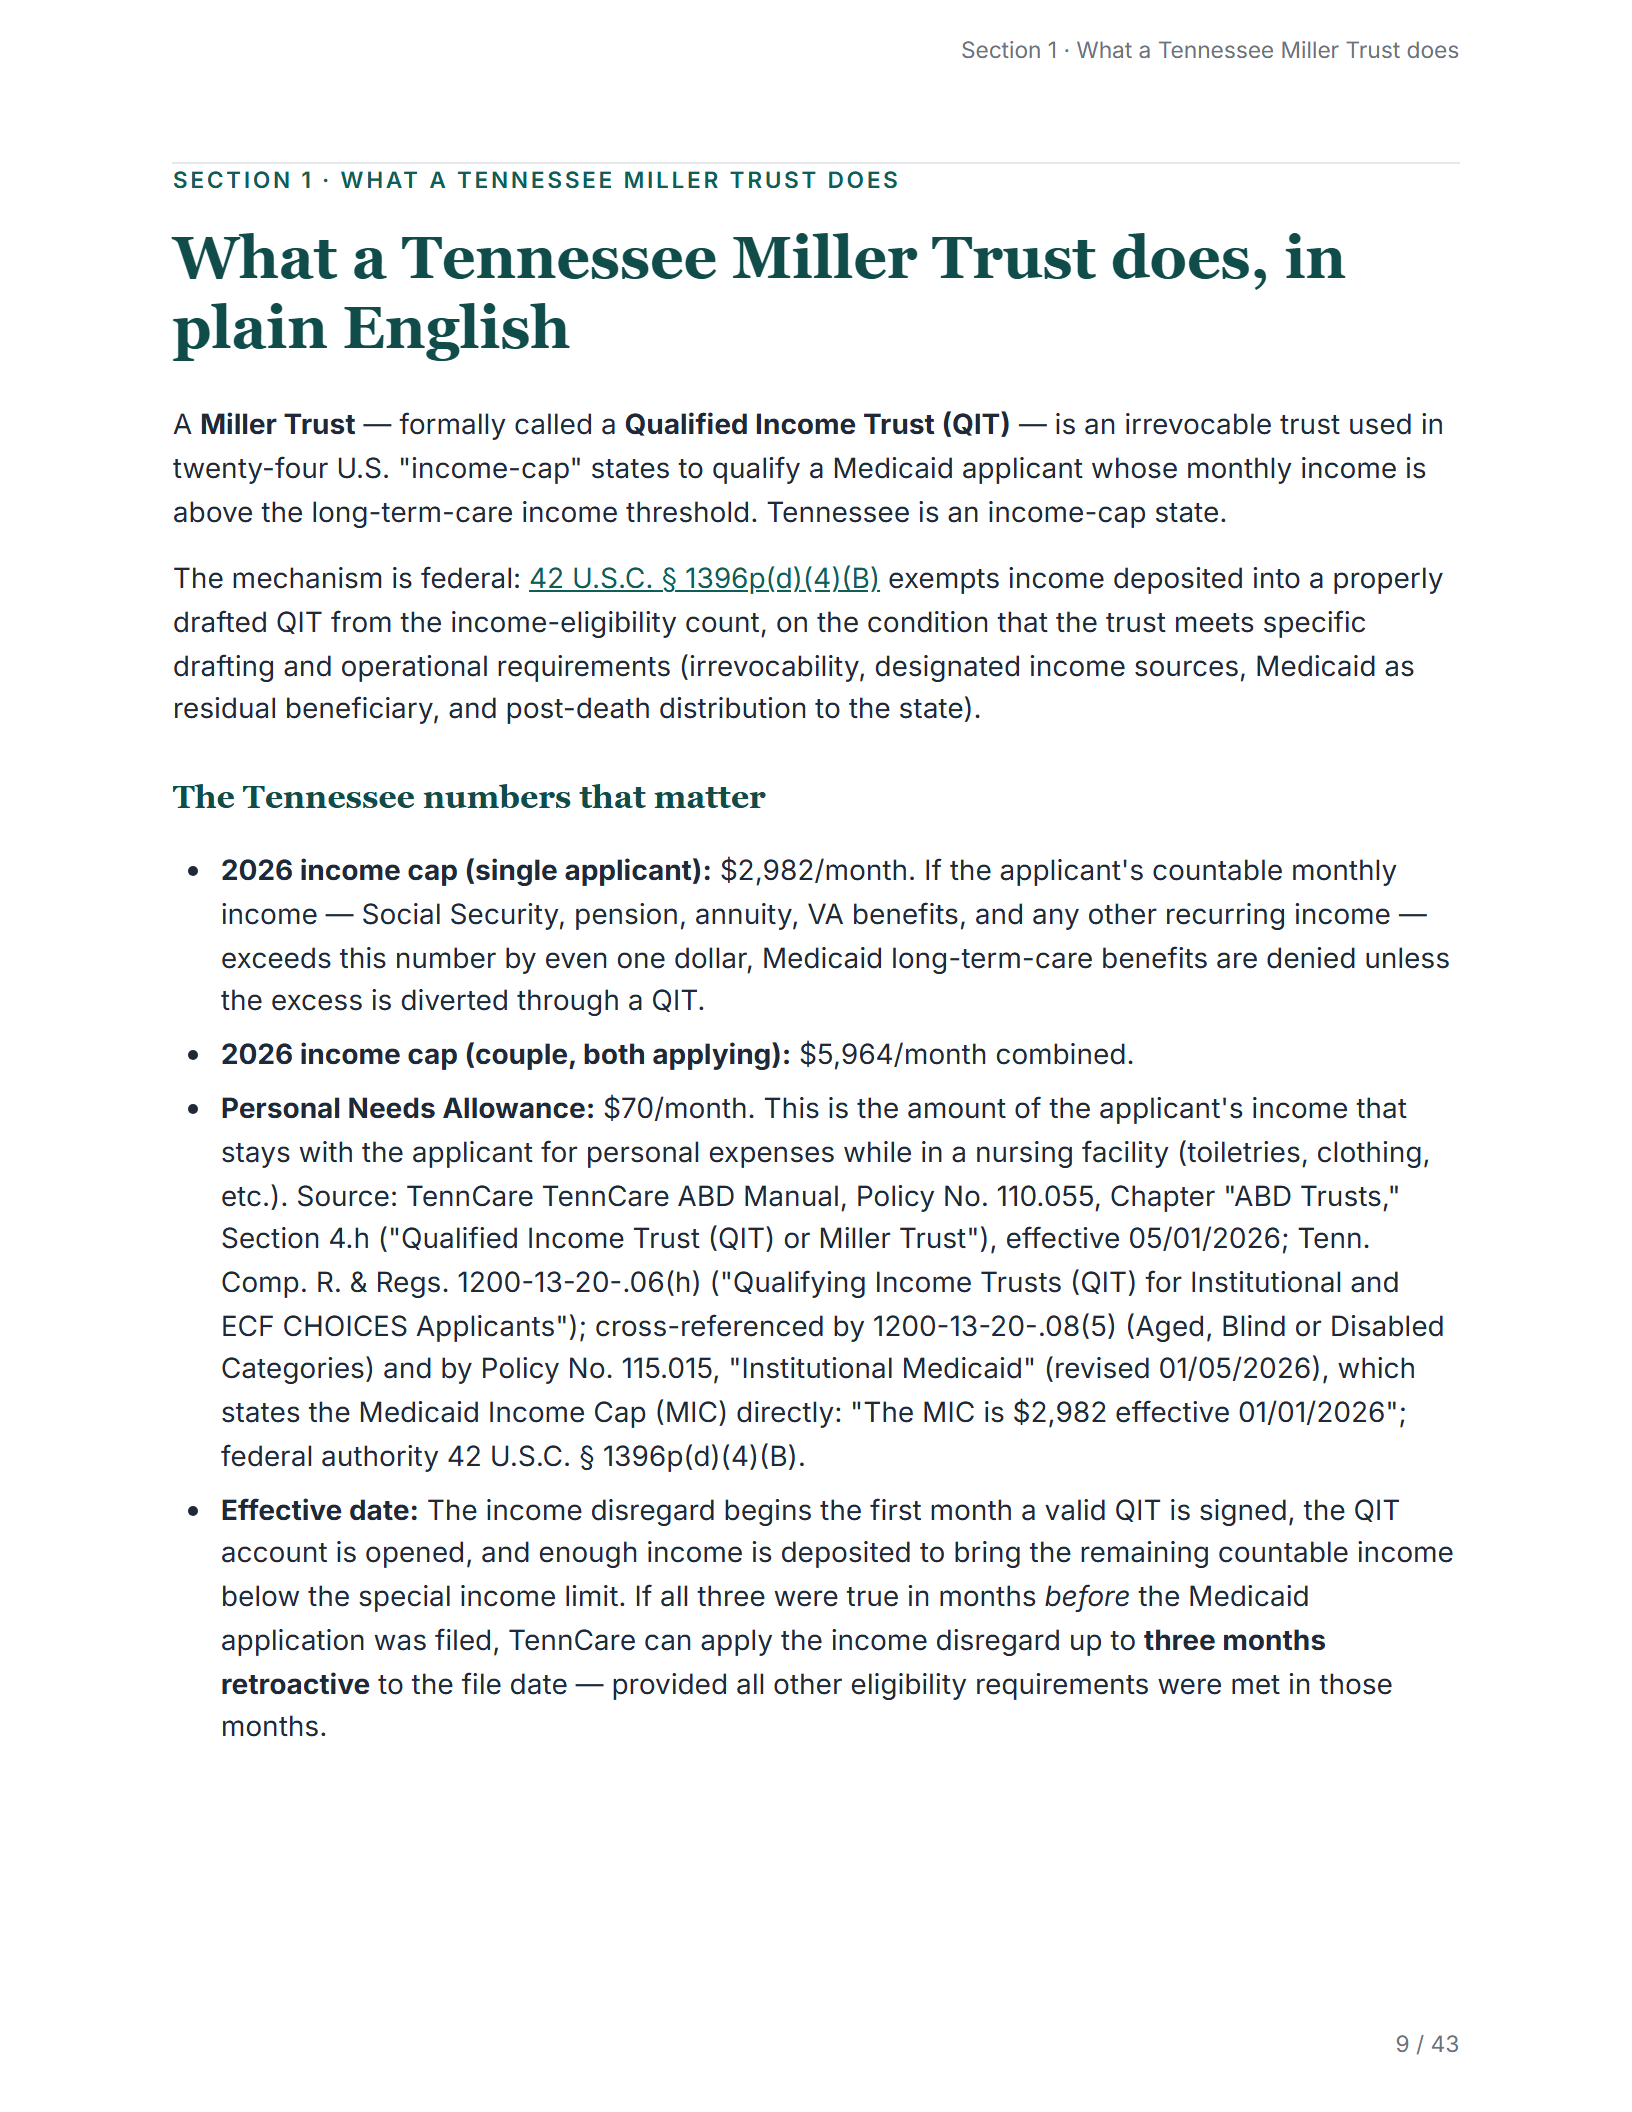
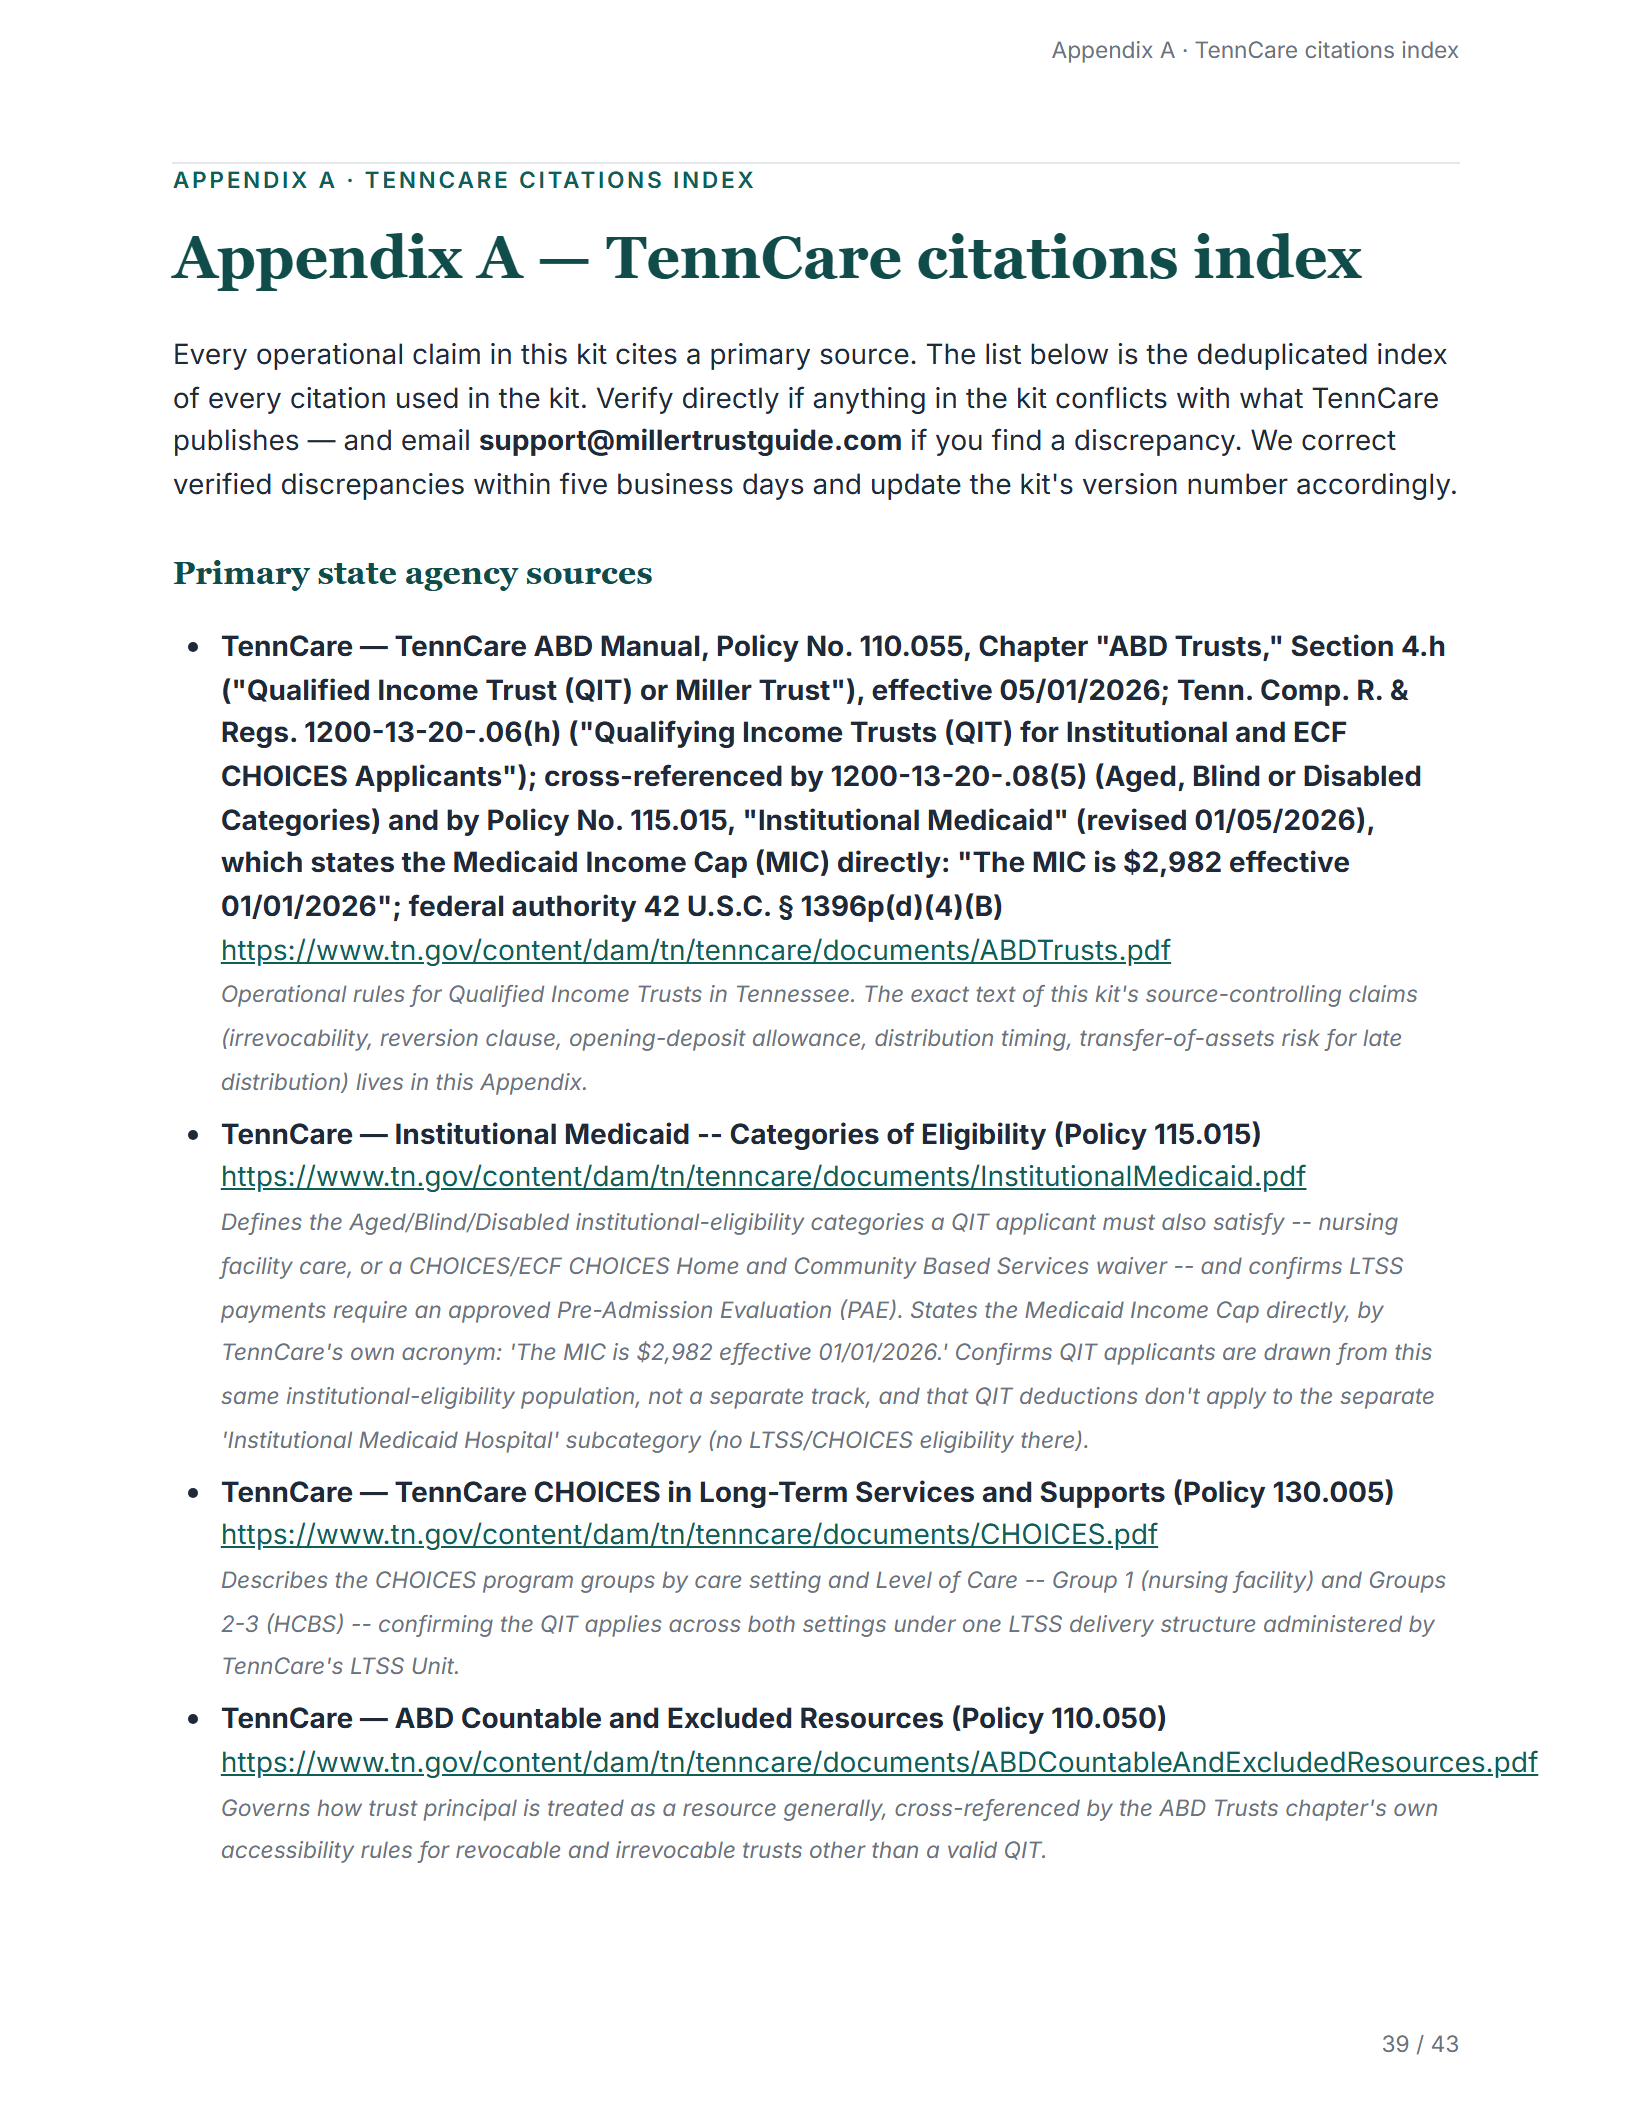
Print-friendly, readable on a phone or tablet, and designed to be taken to the bank. Every operational claim cites a primary state agency or federal source.
How this compares
Tennessee doesn't publish a fill-in QIT form, so an attorney drafts the trust either way. The $97 is for the guide — the requirements checklist and everything around it — that turns the attorney's job into drafting alone, instead of research-and-drafting on your bill.
| This guide | Attorney alone (no prep) | DIY research, no guide | Doing nothing | |
|---|---|---|---|---|
| Cost | $97 + attorney's drafting fee | $1,000–2,500 (research + drafting) | $0 upfront — real risk of a rejected trust | $0, then $9,429–$10,038/mo private-pay |
| Time to qualified | Faster — drafting only | 2–6 weeks (research + drafting) | Unpredictable | Not until you act |
| Bank-refusal script | Yes | Sometimes | No | n/a |
| State agency citations | Yes | n/a | If you find them yourself | n/a |
| Updated for the current income cap | Yes | Yes | If you catch the update | n/a |
| "What to say to family" script | Yes | No | No | n/a |
| Delivery time | Instant (guide); attorney schedules separately | After consult + retainer | Instant, but unverified | n/a |
Attorney costs reflect typical Tennessee elder-law retainers for a Miller Trust setup. Private-pay nursing-home figures reflect recent Tennessee market averages.
The bank step
The bank refusal nobody warns you about
You walk into your branch with the signed trust. The teller calls a manager. The manager has never seen one. They ask for an EIN. They tell you to come back with an attorney. You drive home with an empty trust account and a Medicaid clock ticking.
This is the single most common reason Tennessee families lose a month of benefits, and it has nothing to do with the trust itself — it is a bank-procedure problem. The guide's bank section gives you the exact language to cite at the counter, the TennCare policy reference to read aloud, and a printable resolution letter you can hand to the branch manager so they can escalate inside their own bank instead of sending you away.
Refusals the guide walks you through:
- Branch asks for a tax ID (EIN) for the trust account.
- Branch is unsure what kind of account this is.
- Branch has never opened a Qualified Income Trust account before.
- Branch wants to know who is authorized to sign.
- Branch questions why certain fees can't be deducted from the account.
Each refusal has a corresponding response in the guide, with the TennCare citation behind it.
The thing that saves a second trip: bring the printed TennCare policy page to the counter — not just the signed trust. A teller who can read the rule in black and white escalates in minutes; one who only has your word for it sends you home. The guide tells you exactly which page to print and hand across.
If TennCare rejects the trust, you pay nothing.
Email the agency's stated denial reason to support@millertrustguide.com within 30 days of purchase and we refund the full purchase price within one business day. No phone tag, no forms, no fight. Changed your mind for any other reason? You have 7 days, no questions asked. We'd rather lose the sale than make this harder on a family already dealing with enough. Full refund policy.
Avoid these
The 6 most common Tennessee denial reasons
Every denial reason below cites TennCare policy. The full guide explains each one in context and the order in which to verify them before submitting the Medicaid application.
Trust is revocable, or the grantor retains modification power
Income outside the Trust still exceeds the income limit
Missing or defective State-of-Tennessee payback clause
Trust pays a disallowed expense
Trust income isn't distributed under the required monthly process
Trust benefits someone other than the individual and the State
Before you go to the Tennessee bank
Most wasted trips are a bank-procedure problem, not a trust problem. This free one-pager has the questions to ask on the phone before you drive to a branch — emailed now. We'll also send 4 short follow-ups over the next 3 weeks (why most denials are paperwork not eligibility, the trustee role, when to call an attorney) — then we stop. No ongoing newsletter.
The author
Who's behind this
I'm James Whitfield — the person who hit the gap between an attorney-drafted document and a funded Medicaid trust (the short version is up top) and built this guide to close it. I'm not an attorney. I'm a researcher who has now read every TennCare policy section that covers Qualified Income Trusts, and I publish what I learned with a citation on every claim. I won't advise you on your specific situation, draft anything, or review a document you or your attorney have drafted; for advice on your situation, you need a Tennessee-licensed attorney.
Questions
Frequently asked questions
Is the Tennessee Qualified Income Trust Kit legal advice?
Does TennCare provide an official Qualified Income Trust form?
What does the kit include?
Do you provide the trust document itself?
Who needs a Qualified Income Trust in Tennessee?
How much of my income goes into the trust?
What if my bank refuses to open the trust account?
Can I be my own trustee in Tennessee?
Does a Tennessee Qualified Income Trust need an EIN?
What can the trust actually pay for?
Is Social Security counted before or after the Medicare Part B premium for Tennessee's income cap?
What is TennCare's official order for deducting income before patient liability is calculated?
Do you offer a refund?
Will you talk to me on the phone about my situation?
Do you need an EIN to open a Tennessee Miller Trust account?
Who can serve as trustee of a Tennessee Miller Trust?
Which banks will open a Qualified Income Trust (QIT) bank account in Tennessee?
When does Tennessee Medicaid coverage begin after the Qualified Income Trust is set up?
What happens to the money in a Tennessee Miller Trust when the beneficiary dies?
Can you set up a Tennessee Miller Trust without a lawyer?
Can an attorney, paralegal, or care manager use this guide for a client?
Ready to start?
$97, one time. Instant download. Money-back if TennCare rejects your QIT for any reason traceable to following the guide, or for any other reason within 7 days.
The guide itself is instant — the requirements checklist and everything around it, ready before your first call. Most Tennessee families move from that first attorney call to a funded trust account faster than they expected, because the research and fact-gathering are already done.
One last step — confirm below and it's instant from there.
Secure checkout by Stripe · Instant download · Money-back guarantee
Want them to see the whole case? Send them what you just read.
Not ready to buy yet?
Free 5-email series: the funding-month rule, what really happens at the Tennessee bank, why most denials are paperwork not eligibility, who manages the trust each month, and the one honest sign it's time to call an attorney instead. Then we stop. No ongoing newsletter, no sales list.
Keep reading
Step-by-step Tennessee guides
New to this? What Is a Miller Trust? covers the plain-English basics — what it is, why states use different names for it, and how it differs from a Medicaid Asset Protection Trust. Below are the free operational walkthroughs that go deeper on the questions Tennessee families ask most.
Free operational walkthroughs
- How to Set Up a Qualified Income Trust in Tennessee: Step by Step
- How Long Does It Take to Set Up a Qualified Income Trust in Tennessee?
- How Much Does It Cost to Set Up a Qualified Income Trust in Tennessee?
- How Much Does a Nursing Home Cost in Tennessee?
- What to Say at the Bank When Opening a Qualified Income Trust Account in Tennessee
- Who Can Be the Trustee of a Qualified Income Trust in Tennessee?
- Do You Need an EIN for a Qualified Income Trust in Tennessee?
- What Happens to a Qualified Income Trust When the Beneficiary Dies in Tennessee?
Primary sources
State agency sources
Last verified against TennCare on 2026-08-08. Email support@millertrustguide.com if anything below conflicts with what TennCare currently publishes — we correct verified discrepancies within five business days.
Every claim here cites a primary TennCare or federal document — see them
Primary state agency sources
- [1] Policy manual: TennCare policy manual (section TennCare ABD Manual, Policy No. 110.055, Chapter "ABD Trusts," Section 4.h ("Qualified Income Trust (QIT) or Miller Trust"), effective 05/01/2026; Tenn. Comp. R. & Regs. 1200-13-20-.06(h) ("Qualifying Income Trusts (QIT) for Institutional and ECF CHOICES Applicants"); cross-referenced by 1200-13-20-.08(5) (Aged, Blind or Disabled Categories) and by Policy No. 115.015, "Institutional Medicaid" (revised 01/05/2026), which states the Medicaid Income Cap (MIC) directly: "The MIC is $2,982 effective 01/01/2026"; federal authority 42 U.S.C. § 1396p(d)(4)(B)). This is the source for the required-provisions checklist — Tennessee publishes no separate fill-in template.
- Institutional Medicaid -- Categories of Eligibility (Policy 115.015): TennCare — Institutional Medicaid -- Categories of Eligibility (Policy 115.015) . Defines the Aged/Blind/Disabled institutional-eligibility categories a QIT applicant must also satisfy -- nursing facility care, or a CHOICES/ECF CHOICES Home and Community Based Services waiver -- and confirms LTSS payments require an approved Pre-Admission Evaluation (PAE). States the Medicaid Income Cap directly, by TennCare's own acronym: 'The MIC is $2,982 effective 01/01/2026.' Confirms QIT applicants are drawn from this same institutional-eligibility population, not a separate track, and that QIT deductions don't apply to the separate 'Institutional Medicaid Hospital' subcategory (no LTSS/CHOICES eligibility there).
- TennCare CHOICES in Long-Term Services and Supports (Policy 130.005): TennCare — TennCare CHOICES in Long-Term Services and Supports (Policy 130.005) . Describes the CHOICES program groups by care setting and Level of Care -- Group 1 (nursing facility) and Groups 2-3 (HCBS) -- confirming the QIT applies across both settings under one LTSS delivery structure administered by TennCare's LTSS Unit.
- ABD Countable and Excluded Resources (Policy 110.050): TennCare — ABD Countable and Excluded Resources (Policy 110.050) . Governs how trust principal is treated as a resource generally, cross-referenced by the ABD Trusts chapter's own accessibility rules for revocable and irrevocable trusts other than a valid QIT.
- Post-Eligibility Treatment of Income (Policy 125.020): TennCare — Post-Eligibility Treatment of Income (Policy 125.020) . The actual source of TennCare's ranked, numbered deduction order applied to total income when calculating patient liability (a broader, differently-scoped list than the QIT-specific allowable-payments list in ABD Trusts §4.h.v) -- and the rule that the Medicare Part B/C/D premium deduction is barred entirely for individuals who are SSI-eligible, an SSI Pickle/DAC pass-along, or enrolled in a Medicare Savings Program (QMB, SLMB, QI, or QDWI).
Federal sources
- 42 U.S.C. § 1396p(d)(4)(B) — federal Medicaid statute authorizing QITs. https://www.law.cornell.edu/uscode/text/42/1396p
- CMS — 2026 SSI and Spousal Impoverishment Standards. https://www.medicaid.gov/federal-policy-guidance/downloads/cib12092025.pdf . Source for the 2026 Federal Benefit Rate and the 300% cap derivation used in the Tennessee income-cap figure.
- SSA — 2026 SSI Federal Payment Amounts. https://www.ssa.gov/oact/cola/SSI.html . Verification of the 2026 FBR figure CMS uses to compute the 300% Medicaid long-term-care income cap.